8 mins read
One card per vendor catches waste and limits the damage when a card is compromised. But three business operators found it also brings approval queues, card sprawl and suppliers that will not take cards.
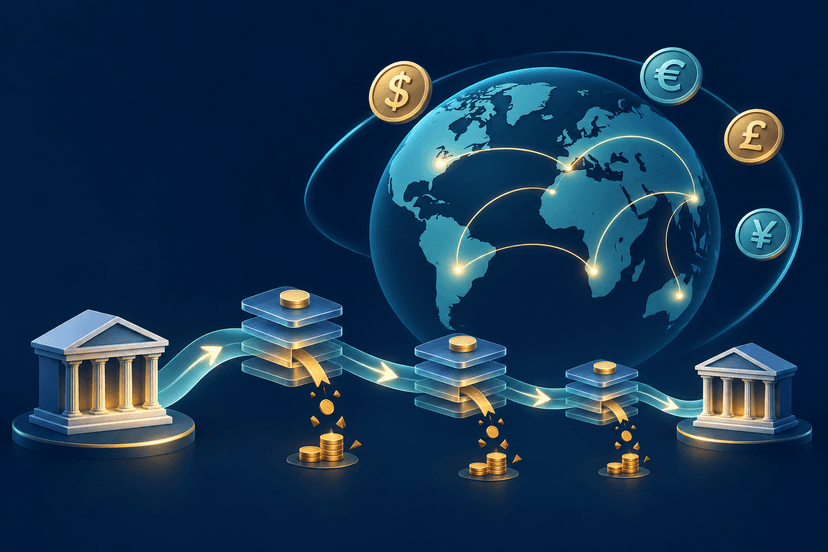
For years, many small businesses ran their software and supplier bills through one company credit card. It was simple until something went wrong. Virtual cards changed that model. A finance team can now issue a separate card number for each vendor, with its own limit and owner. Spend management platforms have built large businesses on that idea.
So we asked industry leaders one question: what has moving to virtual cards or a spend management platform changed for your finance team, and what did not go as planned? We wanted specific results over feature lists. Three respondents answered, all running or advising smaller businesses. Below, we set their replies against the wider market.
Fintechbits analysis
Why virtual cards are booming
Investors see a large market in spend control. In October, Ramp reportedly raised $1.85 billion at a $60 billion pre-money valuation, up from $44 billion in June, The Paypers reported, citing Bloomberg. The company said in June that it served 70,000 businesses. Meanwhile, software bills keep growing. Zylo’s 2025 SaaS Management Index found SaaS spend reached $4,830 per employee, up 21.9% in a year. It also estimated that organisations waste about $21 million a year on unused licences, although those are enterprise averages from a vendor that sells licence tools.
That growth in subscriptions is where virtual cards earn their keep. Every recurring charge is a chance for a price rise, a duplicate payment or a forgotten tool to slip through.
Security is the other draw. A card number stored with dozens of online vendors is exposed every time one of them is breached. With virtual cards, a leaked number only works with one merchant and only up to its limit, and finance can cancel it without touching anything else. In addition, many platforms let firms lock a card to a single merchant or issue a single-use number for a one-off purchase. That is why our first respondent talks about blast radius rather than convenience.
Smaller blast radius, named owners
Our first respondent builds and sells e-commerce businesses and now advises Shopify stores on preparing for a sale.
“We started using virtual cards because they cut our ‘blast radius’ from every vendor to just one.
Faster card issuance was nice, but the real win was getting rid of the shared, high-limit credit card. If that card was compromised, someone in finance had to update the card on file for a dozen or more subscriptions. A shared card also hid things: a duplicate charge or a small price rise on a subscription went unnoticed.
Now each vendor has its own virtual card, with a limit equal to the expected invoice plus a margin. If there’s a suspicious charge from AWS, an ad platform or a SaaS tool, finance cancels that one card and deals with one vendor.
Giving every card a named owner is what brought our costs down. One of our first reviews found a $6 a month Mailchimp subscription that had had no active user for four years. That’s nearly $300 wasted, because people were reconciling the statement, not reading it. Now, when a card is issued, the register records the vendor, the business owner and the purpose. Any charge must come from that vendor and stay within the limit.
The downside was that virtual cards got out of hand quickly. We ended up with too many and lost track of which was used for what, so we set rules: cards only for subscriptions, travel or vendor payments, and every card named in a set format.
Pre-funding also backfired. If a credit card gives you better terms, loading a virtual card in advance costs you a month of credit. We now use virtual cards only for low-value charges that are hard to reconcile, not large ones that are easy to match.”
John Mac, Founder, Exit Evidence
His figures add up. Six dollars a month over four years comes to $288. However, his larger point is about ownership, not the card itself. Virtual cards only cut waste when someone is responsible for each one and reviews what it pays for. His pre-funding warning matters too. Some virtual cards draw on a prepaid balance, while a credit card gives weeks of free credit. As a result, the cheapest setup depends on how each card is funded.
Visibility is not the same as savings
Our second respondent was the most cautious about the results.
“The main change is that there are no surprise charges at the end of the month. Each subscription sits on its own card with a limit, so if a vendor raised its price or double charged us, we could see straight away that the payment hadn’t gone through. Before, we’d only catch that at reconciliation. Receipts got easier too, because each card belonged to a specific vendor and owner, so we could match the cost to the right person.
Approvals didn’t go as planned. We expected limits would remove manual approval, but there were lots of requests to raise limits, and they all piled up with one person. Some vendors also wouldn’t accept a virtual card number, so we kept a physical card for those, and that was never fully resolved. Overall, I’m not sure whether the platform is reducing what we spend or just making it easier to see.”
Ankit Sarawagi, Curator, CFO Matrix
His doubt is the fair test for virtual cards. A declined charge shows a problem, but someone still has to act on it. Meanwhile, tight limits move work from reconciliation to approvals. If every limit increase goes to one person, that person becomes the bottleneck. Therefore, firms should set approval rules by amount and vendor type before issuing cards, not after the queue builds.
Start with subscriptions
Our third respondent runs an international apparel business with a long list of online services and suppliers.
“If you’re starting out, begin with subscriptions, because they’re the easiest place to use virtual cards. Set up a card for each subscription with a sensible limit. If it’s charged more than expected, or it’s a subscription you forgot you still had, the payment is simply declined and you know straight away. It also makes month-end much easier, because you can see what’s what.
The downside is the setup work. You have to update the card details for every subscription and service, and if you miss one, you may not notice until it silently fails next time round. Some businesses, especially smaller ones or those abroad, will also only accept bank transfer.”
Conor Smart, Director, Arklavo
His point on bank transfers shows the limit of virtual cards. Many suppliers, especially overseas, prefer account-to-account payments to avoid card fees. Faster business transfers are making that route easier, as our report on Stripe’s instant B2B transfers showed. Suppliers also have new ways to get paid early, as our piece on C2FO’s instant pay described.
How to make virtual cards work
Taken together, the answers point to a short set of rules for virtual cards. First, start with subscriptions and recurring software. Next, give every card a named owner, a purpose and a limit close to the expected bill. Then set naming rules and approval thresholds before card numbers multiply. Finally, review spend by owner each month, because a declined charge only helps if someone reads it.
The same principle runs through finance automation more widely. Tools that surface data still need people to act on it, as our report on Intuit’s AI tools for small businesses explored.
What to watch next
Several trends will shape virtual cards in 2027. Spend management platforms are adding AI features that flag unused subscriptions. Watch whether they deliver real savings or just more alerts. Fresh funding at Ramp will also push rivals to compete on price and features. Meanwhile, more AI tools are billing by usage, which makes fixed card limits harder to set.
Above all, our respondents agree on the trade-off. Virtual cards make spending visible and contain the damage when something goes wrong. The savings come only when every card has an owner who looks at what it pays for.
FintechBits covers payments, banking and fintech developments for readers in the US and UK. This article is for information only and is not financial advice. Views expressed are those of the FintechBits editorial team.