6 mins read
Stripe launched Stripe pay on 27 October 2026, a tool that lets a business find another company by its Stripe profile handle and send it money instantly and for free from the Stripe Dashboard or the Stripe CLI, according to Stripe’s announcement on X. Fintechbits checked Stripe’s own documentation and availability table and found that instant transfers on Stripe are listed as a preview in only the United States and the United Kingdom, with each transfer capped at 50,000 USD, GBP or USDC. Both sides also need a Stripe financial account, so the free transfer works only inside Stripe’s own network.
What Stripe pay does
Stripe pay is a send-money button for businesses that already keep a balance with Stripe. The Stripe CLI reference describes it as a plugin that “sends instant business-to-business transfers”, and says the sender needs a funded financial account while the recipient needs a financial account linked to its Stripe profile. A business picks the recipient by handle, such as @recipient, or by a profile network ID, enters an amount and a currency, and reviews the transfer before it goes.
The Dashboard route is the same idea with buttons. Stripe’s documentation says a business clicks Send on the Treasury page, enters a profile or adds a recipient by email and country, then reviews and sends. Stripe’s post on X promised that businesses can “send funds for free”, and Stripe’s money management availability page repeats the point, describing “free instant transfers within the Stripe network”.
The fine print behind the free Stripe pay transfer
The free part is real, but it comes with limits that the launch post leaves out. The Stripe pay CLI supports three currencies only: usd, gbp and usdc. Each transfer must be between 1 and 50,000 in the chosen currency, according to the limits table in Stripe’s documentation, which also labels the feature a public preview.
The country list is the bigger constraint. Stripe’s availability table lists “Instant transfers on Stripe” as preview in the United States and the United Kingdom, with no entry for the eurozone, Canada, Australia or any other market Stripe tracks. A German or Singaporean business on Stripe cannot use Stripe pay from that table’s evidence, however many suppliers it has on Stripe.
Stripe has also put checks around the step that moves money. In agent or JSON mode, the command returns a confirmation_required response before any money moves, and it only sends after the user confirms the recipient, amount, currency and source account. Where an account requires approval, the CLI hands back an approval link, and resumable approval requests expire after five minutes. A dry-run flag validates the whole flow without sending anything.
How Stripe pay compares with Wise, Mercury and FedNow
Free transfers between accounts on the same platform are not new. Wise Business says it is “totally free to send the same currency” from one Wise Business account to another. Mercury’s pricing page says ACH payments and domestic wires are free to send and receive. Wise’s free route has the same catch as Stripe pay, since both ends need a Wise Business account. Mercury’s free ACH and wires reach any US bank account.
The public rails are cheap too. The Federal Reserve’s FedNow 2026 fee schedule charges participating banks $0.045 per credit transfer, with a discount that removes that fee for up to 2,500 transfers a month in 2026. Stripe pay cannot beat the banking system on price by much. Its advantage is addressing: a handle replaces bank details, and the money lands instantly because it never leaves Stripe’s ledger.
Fintechbits analysis
Why Stripe pay is a bet on a business directory
The interesting part of Stripe pay is the directory behind it. Every business that creates a Stripe profile and a financial account becomes reachable by handle, and every transfer gives the next business a reason to open one. Venmo handles grew the same way among consumers, and Stripe is trying it with companies that already settle card revenue through Stripe.
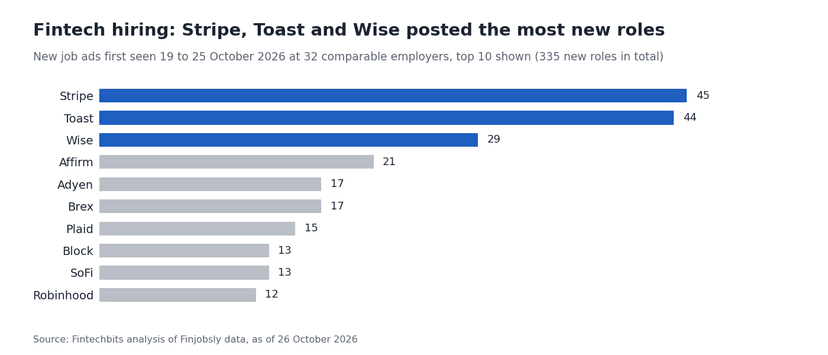
The design of the CLI points at where Stripe thinks the volume will come from. A tool with agent mode, dry runs and a forced confirmation step is built for software, including AI agents, paying suppliers on a company’s behalf. Stripe has been pushing hard into financial accounts and agent payments, and its hiring reflects the scale of that push: Stripe posted 45 new roles in one week in October, the most of any employer in Fintechbits’ October hiring pulse.
Reach is the weak spot. A free transfer that only works between two Stripe financial accounts, in two countries, in preview, is a closed loop. For a business whose supplier banks elsewhere, Stripe pay does nothing that an ACH payment or a payout platform does not already do.
Frequently asked questions
Is Stripe pay free?
Stripe says Stripe pay transfers are free. Its post on X says businesses can “send funds for free”, and its availability page describes free instant transfers within the Stripe network.
Who can use Stripe pay?
Both the sender and the recipient need a Stripe profile and a Stripe financial account, according to the Stripe CLI reference. Stripe’s availability table lists the feature as a preview in the United States and the United Kingdom only.
How much can a business send with Stripe pay?
Each transfer must be between 1 and 50,000 in USD, GBP or USDC, according to the limits table in Stripe’s instant transfers documentation. The CLI also limits the recipient memo to 22 ASCII characters.
What to Watch Next
The number to watch is the country list on Stripe’s availability page. If the instant transfers row moves from preview to general availability and adds the eurozone, where the same table already shows SEPA top-ups in preview, Stripe pay becomes a real alternative to Wise for business payments across borders. If it stays a two-country preview into 2027, it will mostly serve companies that already run their treasury on Stripe.