5 mins read

Parafin forward flow capacity grew again on July 21, 2026, when the embedded finance infrastructure company announced an agreement with a top New York-based alternative asset manager. Up to $300 million of loans originated through the platform will be purchased into a rated vehicle. The buyer is not named.
What the Parafin Forward Flow Agreement Covers
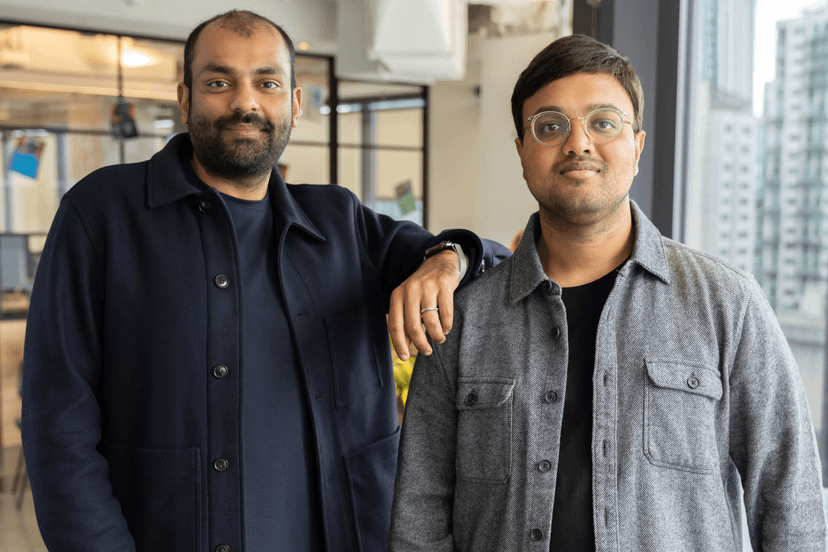
Parafin powers lending inside platforms including Amazon, Walmart, DoorDash, and Gusto, underwriting largely on sales data the platform already holds. Founded in 2020 by Sahill Poddar, Vineet Goel, and Ralph Furman, the company is backed by Ribbit Capital, Thrive Capital, GIC, Notable Capital, and Redpoint Ventures.
The mechanics are capital markets plumbing rather than product news. An asset manager agrees up front to buy a defined volume of loans as they are originated, which hands Parafin funding certainty and hands the buyer a steady supply of assets matching an agreed credit profile. This Parafin forward flow facility sits alongside recently announced partnerships with Goldman Sachs and EverBank, plus a renewed commitment from First Citizens, giving the company several separate channels rather than one balance sheet.
How This Parafin Forward Flow Deal Differs From the First
The first agreement came in September 2025, when Cross River Bank committed through its Principal Finance Group to purchase up to $360 million in aggregate assets. Parafin described that deal as its inaugural off-balance-sheet commitment, which makes the new one the second.
The structural difference matters more than the headline figures. This transaction routes assets into a rated vehicle, meaning the purchasing entity issues notes carrying a credit rating. That opens the door to conservative institutional investors who cannot hold unrated paper, and it signals institutional-grade credit packaging rather than a bilateral side arrangement. A Parafin forward flow deal into a rated structure is a step up in sophistication from a bank purchase commitment, not simply a second helping of the same thing.
The Parafin Forward Flow Volume Story
Alongside the deal, Parafin said it has surpassed 50,000 unique businesses funded across three products: working capital, buy-now-pay-later, and a credit card. That footprint is meaningfully larger than most embedded lending startups reach, and it is the precondition for forward flow working at all. Nobody commits nine figures against origination volume that might not materialize.
The supporting numbers back it. Parafin has extended more than $8 billion in offers across platforms including Worldpay and Mindbody. Its partnership with Fullsteam passed $125 million in financing, and a program with 360 Payments reached $100 million. Plenty of small business lenders announce one forward-flow deal as a proof point and then go quiet. Doing a second, into a more demanding structure, is the better signal.
Fintechbits analysis
Why the Unnamed Buyer Is Not the Parafin Forward Flow Story
It is tempting to read something into the anonymity. Resist it. Buyer non-disclosure is common in forward-flow arrangements, and industry coverage of this specific transaction treated it as unremarkable. Reading reluctance or reputational distance into a standard confidentiality term would be speculation the release does not support.
The structure tells you far more than the name would. A rated vehicle requires a rating agency to examine the collateral, the servicing, and the loss assumptions before notes get issued. That process is a more demanding test of the Parafin forward flow book than any single buyer willingness to appear in a press release. Poddar said the agreement “demonstrates the strong credit quality of Parafin assets.” A rating is how that claim gets checked by somebody other than Parafin.
Parafin Forward Flow Sits Inside a Wider Capital Wave
One caution on the exceptionalism. This deal arrived during a run of similar announcements across non-bank small business lending. Trade coverage in the same window noted Lendistry taking a bank warehouse from East West, Forward Financing moving into a variable funding note and a rated securitization, and Northbase securing a private credit revolver from Oaktree.
Different structures, same underlying signal. Institutional capital is competing to fund non-bank small business credit right now, meeting each originator wherever it sits in the capital stack. That does not diminish what Parafin built. It does suggest the funding environment deserves some credit alongside the loan book, and that terms available today may not persist if credit conditions turn.
The Honest Read on This Parafin Forward Flow Deal
The volume is the story, not the mechanics. Fifty thousand businesses funded across three products, embedded inside platforms as large as Amazon and DoorDash, is a real operating footprint. Layering a second nine-figure facility on top of the Cross River commitment, alongside Goldman, EverBank, and First Citizens, indicates institutional capital willing to commit repeatedly rather than once.
What the release withholds is anything about performance. No loss rates. No delinquency figures. No weighted average yield or advance rate. Credit quality is asserted by the chief executive and implied by the structure, never demonstrated with a number.
What to Watch on Parafin Forward Flow Next
Chasing the buyer identity is the wrong pursuit, since anonymity here is routine and the name would tell you little. Watch the rating instead.
If the vehicle issues rated notes, a rating agency will publish its assessment of collateral quality, expected losses, and structural protections. That is an independent judgment on precisely the credit quality Poddar asserts, produced by a party with no incentive to flatter. A public securitization would be the natural next step after that, following the path Forward Financing has already taken. Either event would give outsiders their first real look inside a Parafin forward flow portfolio, replacing company assertions with numbers somebody else is accountable for.
Sources: the announcement is on BusinessWire, the Cross River agreement is detailed by Parafin, and sector context comes from FunderIntel.
Fintechbits covers embedded finance, small business credit, and lending capital markets. Nothing here constitutes financial or investment advice. All analysis represents the editorial views of Fintechbits.