8 mins read
Invoice factoring keeps getting written off as a relic of pre-fintech finance. Yet the numbers refuse to cooperate with that story. Global factoring turnover hit a record EUR 4.039 trillion in 2025, up 3.7 percent on the year, according to FCI. Meanwhile, the narrow band of US specialist firms has been shrinking for five years straight.
So we asked four industry leaders a blunt question. Is invoice factoring still relevant for small businesses, or have newer alternatives made it obsolete? Nobody called it dead. Instead, every answer landed on the same word. Situational.
Fintechbits analysis
Why the Invoice Factoring Market Looks Like Two Markets
The contradiction comes down to definitions. FCI counts total receivables purchased worldwide, including bank-owned programmes and large corporate facilities. IBISWorld measures something far narrower, the independent US specialists, and puts that industry near $3.0 billion in 2025 after roughly five years of decline. Consequently, receivables finance grows while the traditional standalone factor consolidates.
Where did the growth go? Largely into embedded products. Accounting platforms now offer get-paid-early features inside software that owners already use, and those deposits can land in under an hour. That pressure hits the smallest accounts first, which is precisely where independent invoice factoring firms used to win. Community banks are chasing the same territory, as the CSI acquisition of Qolo made clear.
Who Still Reaches for It
The heaviest users have not changed much. Trucking, staffing, construction subcontracting, manufacturing, wholesale distribution and healthcare receivables dominate the book. What links them is a long gap between doing the work and getting paid, paired with costs that will not wait. Payroll runs on Friday whether or not the customer pays on day 60.
Invoice factoring continues to be relevant in today’s economy, though it is no longer the go-to option for every small business. It can still be a great option if you are a B2B seller who offers terms, you have money tied up in unpaid invoices, and you need working capital quickly. Since newer businesses tend to not have the credit history required to qualify for bank financing, they may be well suited to use factoring as a source of cash. The classic trade-off still exists.
You receive working capital quickly. However, you must give up a portion of your invoice and, in many instances, give up a degree of control over how your customers are collected upon. Newer options do not eliminate factoring. Rather, they increase the choice available to small business owners. If your primary concern is margin compression, then factoring may not resolve your cash-flow issue. In fact, it could increase your cash-flow problems in future due to increased interest costs.
Anton Strasburg, Media Manager, FreeConference.com
That last point deserves emphasis. Factoring underwrites your customer’s credit rather than yours, which explains how a two-year-old staffing firm with blue-chip clients qualifies when a bank says no. Bank credit has tightened rather than loosened since 2023. SBA rules also got stricter in June 2025 under SOP 50 10 8, which restored the 10 percent equity injection and dropped the collateral threshold to $50,000. Fewer bank doors mean more invoice factoring enquiries.
One nuance rarely makes it into the debate. Notification factoring tells your customer to pay the factor directly. That remains the norm in trucking and staffing. Non-notification arrangements exist for firms guarding the relationship closely. Non-recourse deals go further and absorb the loss if a customer becomes insolvent. However, disputes and slow payment usually stay with you. Therefore, owners who skip these distinctions buy the wrong invoice factoring product, then blame the whole category.
The Cost Question Nobody Prints as an APR
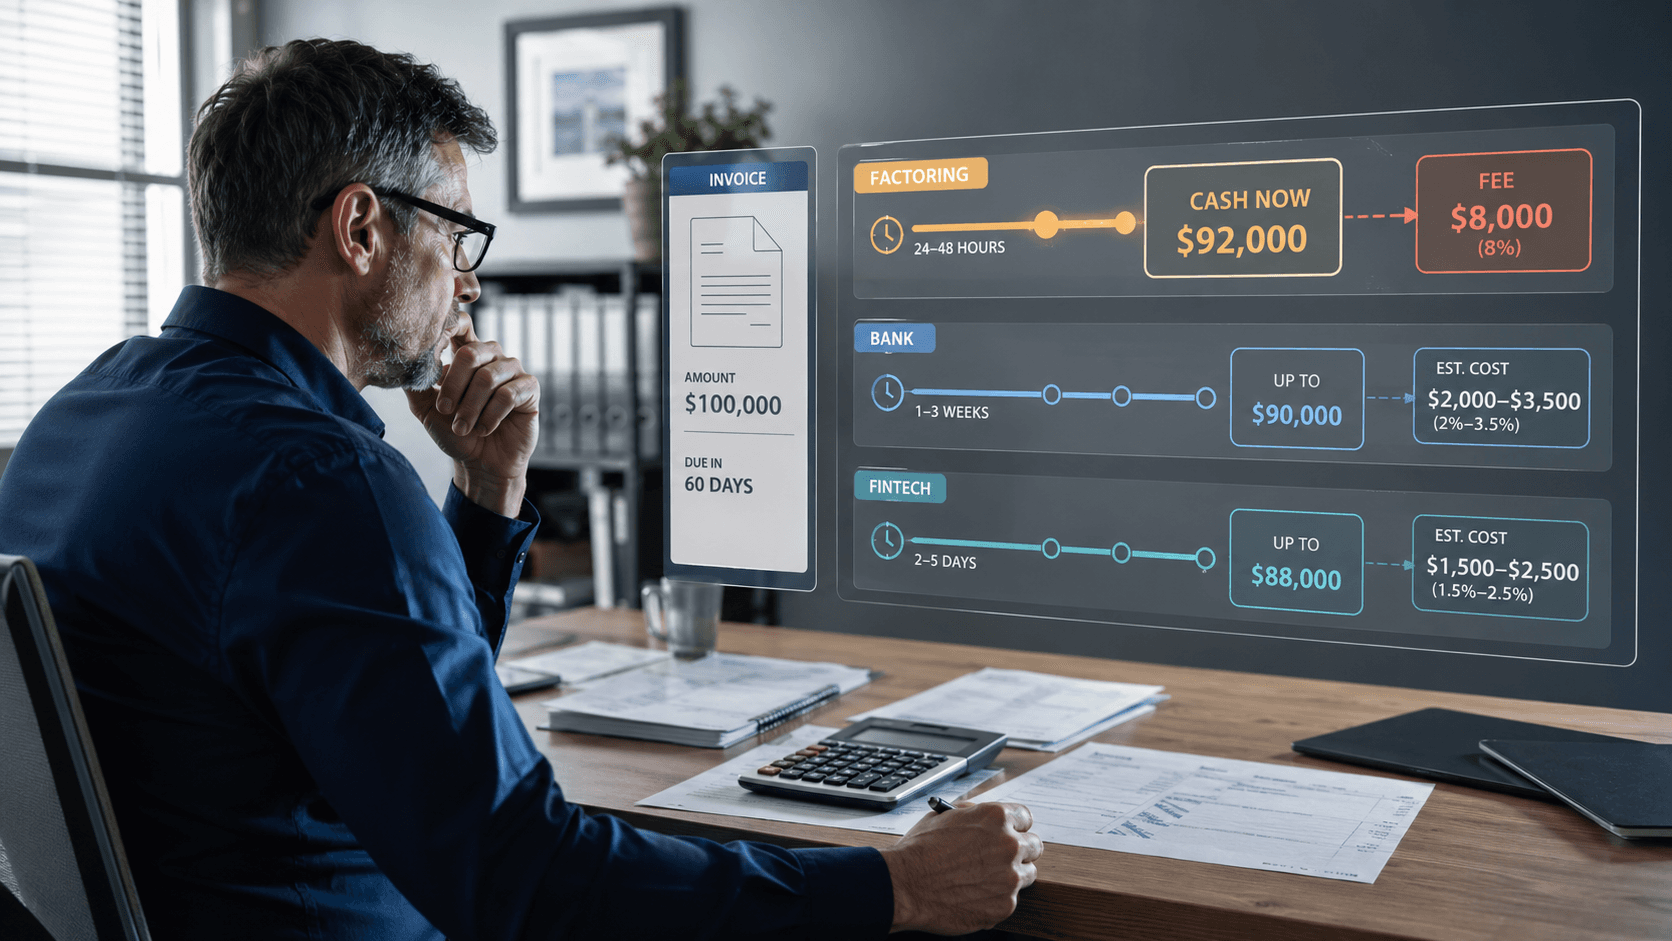
Here is where invoice factoring earns its reputation. Fees get quoted per 30 days, typically 0.5 to 3.5 percent, with advance rates between 80 and 95 percent. Convert that to an annual rate and a 2.5 percent fee on a 60-day invoice lands near 38 percent. That sits well above SBA 7(a) pricing, roughly level with online lenders, and far below most merchant cash advances.
Add-on charges do the quiet damage. Wire fees, monthly minimums, lockbox costs and termination penalties rarely appear in the headline rate, which is the same trap we mapped in our breakdown of what fintech lending really costs against a bank line.
In today’s world, invoice factoring is still relevant. However, it is used in a situational manner rather than being the default method for obtaining financing. In B2B industries with a high percentage of dependable invoices but also a high percentage of slow paying invoices, factoring can provide a quick solution to cash flow problems. Often it moves much faster than traditional small business loans, because the invoices are the collateral.
Meanwhile, business owners are now more selective, since there are more alternatives. More flexible options, such as lines of credit, are often a better fit for general working capital. Therefore, invoice factoring is not dead. Rather, it is a less than desirable choice when a business requires broad working capital, or when outsourcing collections would create friction with a sensitive customer.
Brett Smith, Founder and CEO, 7aSavvy
Automation Is the Rival Nobody Priced In
One panellist pushed the argument further, treating the product as a symptom rather than a solution.
While invoice factoring is still relevant in many businesses, it may typically reflect a broken cash cycle more than a long-term growth solution. Many businesses use it as a financing option. Yet doing so essentially puts a high-priced tax on their margin that hides deeper operational issues.
The innovation happening in this space does not involve a new financial product. Instead, it generally results from companies switching to an ERP-type system with automated document handling. When you handle invoicing, follow-up and payment reconciling manually, it is easy to see why you would want liquidity. However, once you automate those processes, the cash flow gap shrinks. If factoring has become a regular part of your business, take it as a cue to audit your internal accounts receivable processes.
Girish Songirkar, Delivery Manager, Enterprise Software Engineering, Arionerp
The logic holds up better than the evidence does. Credit Research Foundation data put median US days sales outstanding near 40 against a best-possible figure around 32. Therefore only about eight days sit inside a company’s control, and the rest is contractual terms that no workflow tool rewrites. The Hackett Group found receivables performance worsening for a second straight year despite rising technology adoption, largely because buyers keep stretching terms.
Cost matters too. Full ERP deployment starts around $25,000 in year one before implementation, and it runs for months. Few operators factoring $1,600 freight invoices are shopping for NetSuite.
Speed Remains the Actual Product
Invoice factoring does still have its place, particularly for service-based businesses that do not want to wait 30 to 90 days for cash but also cannot be plugged into traditional credit lines.
What I say to people is that new fintech options like revenue-based financing and digital lending platforms have more flexibility. Even so, factoring still represents the fastest way to turn invoices into cash, sometimes in less than 24 hours. The important distinction is that smart business owners today use factoring tactically, as a way to get through specific cash flow crunches rather than as a long-term financing solution, because the costs can add up quickly.
Scott Brown, Founder, MintWit
Sub-24-hour funding is real for established relationships, though less so for a first-time client facing underwriting. Even so, the tactical framing holds. Spot invoice factoring, where a business sells one invoice rather than pledging its whole ledger, fits how owners now behave.
What the Panel Left Out
Three things went unmentioned, and each one matters. Start with freight. Triumph Financial, the second-largest US transportation factor, received 2,835 new client applications in 2024 against 10,766 in 2021. Next comes fraud, since the Transportation Intermediaries Association logged 1,611 reports across seven categories in a six-month window to February 2025, a 65 percent jump.
Then there is disclosure law. Ten states now regulate commercial financing disclosures, and California and New York explicitly cover factoring, forcing cost statements that look a lot like consumer lending paperwork. Also absent from our panel was any owner who used factoring and walked away, which remains the hardest voice to source. The broader access gap our SME financing coverage tracked has not closed either.
The Verdict
Invoice factoring is not obsolete, and calling it a last resort is lazy. Instead, it is expensive, fast, and narrowly excellent at one job. It converts a creditworthy customer’s promise into cash today. So use invoice factoring for timing problems, and avoid it for margin problems.