7 mins read
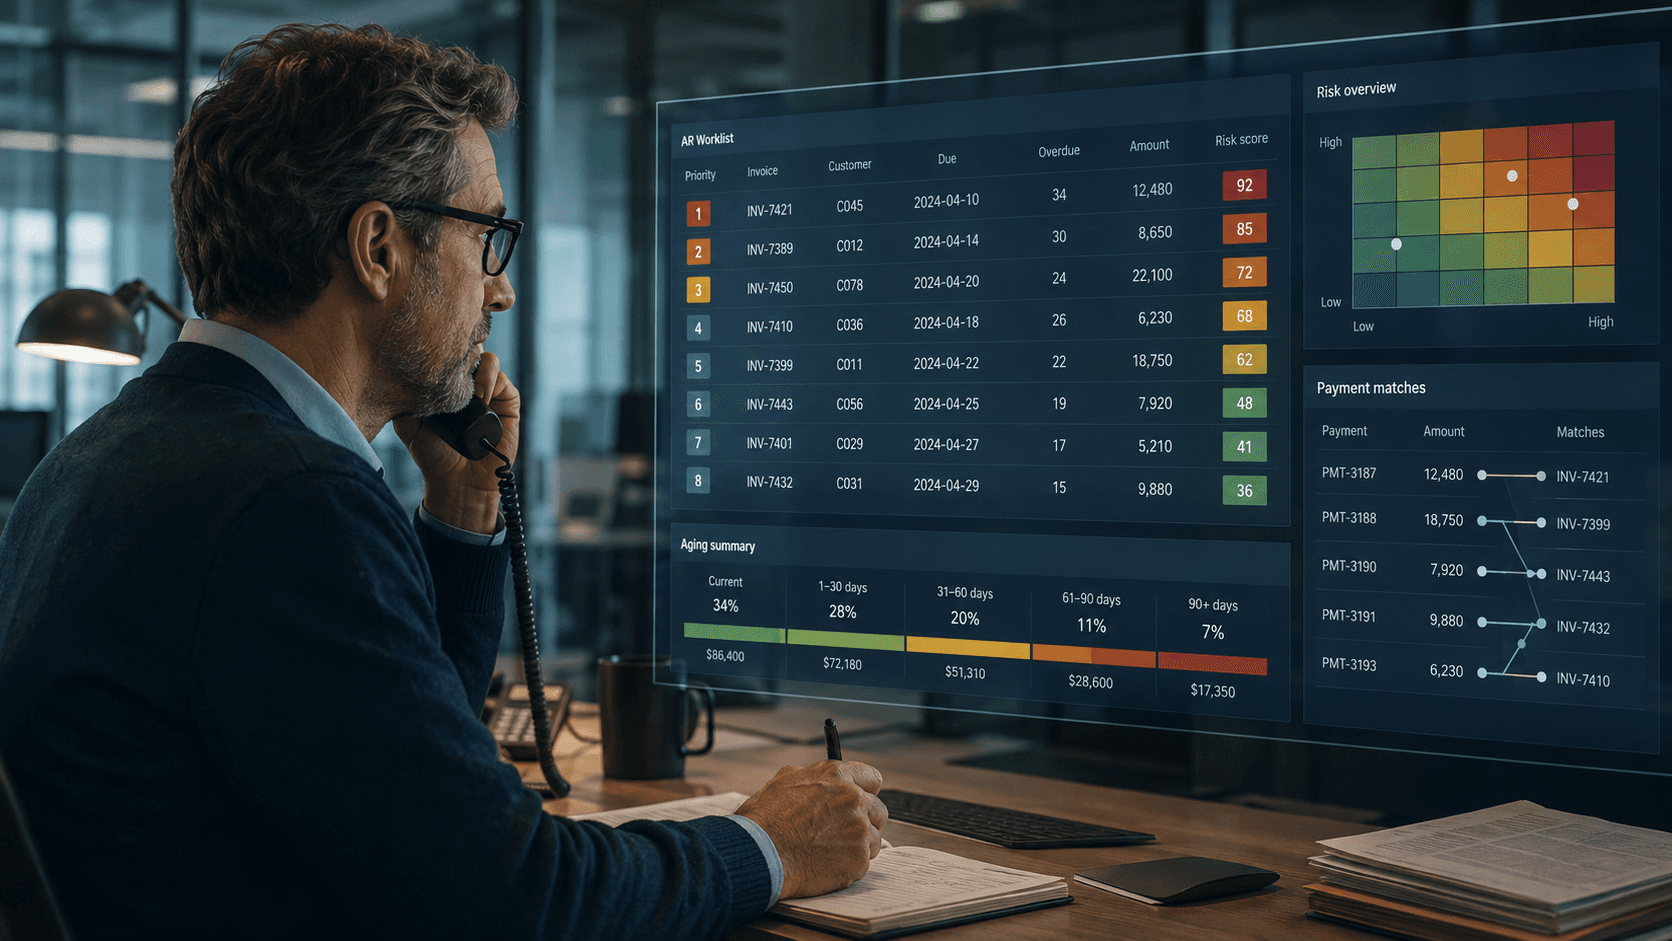
AI in accounts receivable has moved well past the pilot stage at thousands of finance teams. Cash application, dunning sequences, credit scoring, collections triage. Every one of those functions now carries a vendor promise attached to it. So we asked three industry leaders a blunt question. Where does AI in accounts receivable genuinely earn its keep, and where does the marketing outrun the result?
Their answers converged on something uncomfortable. The technology works. Yet the returns arrive far narrower than most pitch decks suggest, and the gap between the two is where finance budgets quietly disappear.
AI in Accounts Receivable Delivers Most on Matching
Start with the least glamorous function in the entire stack. Cash application means matching incoming payments against open invoices, then posting them without a human touching the record. Manual teams typically clear 60 to 75 percent of payments that way. By contrast, AI-native platforms push straight-through processing past 90 percent on structured bank files. So AI in accounts receivable earns its clearest and most defensible return right here.
That gap converts into hours very quickly. Gary Jain has watched it happen across an ecommerce and SaaS client base.
The areas where we see tangible results from applying AI in finance operations today are cash application. Matching payments to invoices could take our accounts receivable teams 6 to 10 hours per week before. Today, with AI software and automation scripts in NetSuite, it takes under 90 minutes.
Gary Jain, CEO, Ledger Labs
Notice what he avoided saying. He never claimed the technology transformed his practice. Instead, he isolated one narrow function, measured it against a real baseline, then stopped there. That discipline is rarer than it sounds.
The Wider ROI Story Runs Thin
Outside matching, the evidence gets patchy fast. The Hackett Group 2025 US Working Capital Survey found roughly $600 billion trapped in receivables across the largest 1,000 US public companies. That figure traces back to an 18-day gap in days sales outstanding between top and median performers. Meanwhile, DSO degraded for a second consecutive year. Years of spending on AI in accounts receivable have not closed that gap.
Broader research points the same direction. MIT Project NANDA reported that 95 percent of enterprise generative AI pilots delivered no measurable impact on the profit and loss statement. Only 5 percent produced serious value. So the wider case for AI in accounts receivable deserves scrutiny rather than assumption.
We have been applying AI-powered cash application and dunning sequence management with some of our ecommerce and SaaS customers for two years now. Honestly, there is a definite ROI here but very limited. Also, it is almost always overstated by the majority of teams.
Gary Jain, CEO, Ledger Labs
Prioritisation Beats Full Automation
Smaller teams often find their value somewhere unexpected. Rather than automating the collection call, they automate the decision about which call to make first. AI in accounts receivable at that scale looks less like autonomy and more like triage.
I have discovered AI’s most significant area of impact has been in helping to prioritise the accounts that we pursue. For example, the AI system can correctly flag each account based upon payment behaviour and invoice amount. It also weighs whether there has been any previous response to communications from us. This way, we can identify which accounts require a reminder, which require a phone call, and which require additional days before contact. However, I would not feel comfortable allowing AI to conduct collections without human interaction. AI is best at identifying patterns and sequences. Meanwhile, humans choose communication style, define exceptions, and use their judgment regarding customer relationships.
Mike Khorev, SEO and AI Visibility Consultant
That framing matters for anyone weighing AI in accounts receivable against a headcount decision. Pattern recognition scales cheaply and improves with volume. Relationship judgment does neither. Consequently, the safest deployments keep the machine on the sorting and the human on the conversation.
Dunning Timing Rests on Thinner Evidence
Vendors selling AI in accounts receivable pitch predictive dunning as a step change over fixed 30, 60 and 90-day reminder schedules. The controlled evidence sounds quieter. Field experiments in tax and consumer lending repeatedly show that reminder timing changes how fast people pay without changing whether they eventually pay. So earlier contact genuinely helps DSO. It does not lift ultimate recovery rates, and no proprietary model is required to send a reminder sooner.
Regarding dunning management, there is no denying that sending automated messages based on predictive algorithms increases your chance of receiving responses. That compares against standard follow-ups performed on the 30th, 60th and 90th days after invoice submission. Nevertheless, it works efficiently only in case you have clear customer data.
Gary Jain, CEO, Ledger Labs
Clean data is the binding constraint here, not the algorithm. Most teams discover that only after signing.
Invoicing Automation Solves a Different Problem
Worth separating out entirely is the front end of the billing cycle, which sits upstream of most AI in accounts receivable work.
We use AI specifically to automatically generate and send invoices to established clients. Because it is quick and automatic, it helps to accelerate our cash flow. Once we have established payment procedures, it makes the entire process fairly seamless. However, there is always some trial and error when implementing this with new clients. So we still check for errors regularly and develop custom prompts to make sure the automation process goes smoothly.
Ranjith Raghunath, CEO, CX Data Labs
Faster invoicing shortens the clock before collections even begins. However, it addresses a different bottleneck, and finance teams conflate the two constantly. An invoice that goes out three days earlier still lands in the same disputed inbox.
Credit Scoring Still Runs on Rules
Buyers of AI in accounts receivable hear the loudest claims on the credit side. They also get the weakest substance.
As far as credit scoring is concerned, I would suggest being careful about expectations from AI applications. The truth is, most small business-oriented software solutions use artificial intelligence simply as fancy terminology for describing rules-based engines. In order to achieve tangible results, you will need to perform large transactions with various types of customers.
Gary Jain, CEO, Ledger Labs
Regulators have started noticing the labelling problem. Gartner estimates that only about 130 of the thousands of vendors marketing agentic AI are genuine, describing the rest as agent washing. The same forecast expects more than 40 percent of agentic projects to be cancelled by the end of 2027.
Similarly, the SEC brought its first AI washing enforcement actions in March 2024, fining two investment advisers $400,000 for claiming capabilities they did not hold. Those same commercial incentives shape how AI in accounts receivable products get labelled.
There is a compliance dimension too. Federal consumer debt collection rules do not reach commercial debt, but state law has started to move, and lending decisions on business credit still trigger adverse action notice duties. Automating a decline does not automate the explanation you owe for it.
Where AI in Accounts Receivable Belongs Next
One pattern runs through all three conversations. Deploy AI in accounts receivable where the task stays mechanical, repetitive and measurable. Cash application qualifies on every count. Worklist prioritisation qualifies. Autonomous collections and small-business credit scoring do not, at least not on current evidence.
I recommend focusing solely on the collection management dunning and prioritisation functions until you have measurable metrics corresponding to days sales outstanding or response rate. Once you have verified clean data and your people trust the data from the automated functions, then implement the automation.
Mike Khorev, SEO and AI Visibility Consultant
Finance leaders weighing this spend should also read our coverage of the verification gap in agentic payments and how fractional CFOs assess this category of tooling. Similarly, the discipline that separates real fintech lending costs from advertised rates applies here without modification.
So measure DSO before you buy. Then measure it again ninety days later against the same definition. If nothing moved, the automation is doing something other than what the demo promised. Ultimately, AI in accounts receivable pays off on narrow, measured ground rather than across the whole function.