5 mins read
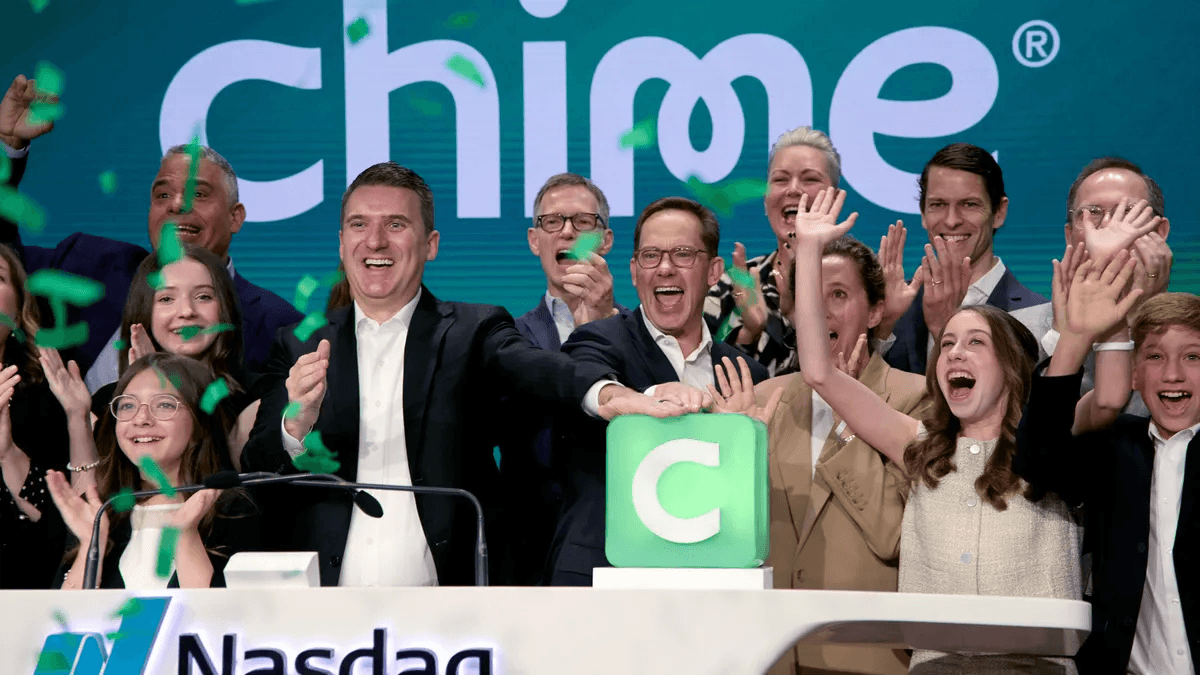
Chime Stride Bank news broke on September 8, 2026, when Chime Financial agreed to buy Stride Bank, N.A. for $590 million in cash. Stride, an Oklahoma national bank, has been Chime’s bank partner for more than seven years. The deal runs through Stride’s parent, Central Service Corporation. As a result, Chime’s most important vendor relationship becomes a wholly owned subsidiary renamed Chime Bank, N.A.
What the Chime Stride Bank Deal Includes
Both boards unanimously approved the transaction. It is expected to close in the first half of 2027, pending approval from the OCC and the Federal Reserve. Stride was founded in 1913 and is based in Enid, Oklahoma, with about $5.4 billion in assets. Its leadership carries over, and Chairman and CEO Brud Baker will lead Chime Bank after closing.
According to Chime’s announcement, the price works out to roughly 1.5 times Stride’s tangible book value. Chime expects the deal to be accretive to earnings per share immediately on closing. It also projects more than $100 million in net synergies from sponsor-bank fee savings, new lending products and a lower cost of funds. Chime will pay from balance-sheet cash, with no new capital contribution expected. Morgan Stanley and Wachtell Lipton advise Chime, while Piper Sandler and McAfee & Taft advise Stride.
Chime paired the news with a stronger outlook. Third-quarter revenue guidance now sits at $705 million, up about 30% year over year. Full-year guidance moved to $2.76 billion to $2.77 billion. CEO Chris Britt framed the Chime Stride Bank deal as a step toward becoming “the largest provider of primary bank accounts in America.”
Fintechbits analysis
Why the Chime Stride Bank Mechanics Matter
The mechanics matter more than the marketing line. Most neobanks do not hold bank charters. Instead, they rent one, routing deposits and card issuance through partner banks such as Stride, Sutton or The Bancorp. They pay fees for the privilege and stay exposed to whatever that partner’s regulators decide. That rent is a real line in the true cost of capital for fintechs.
Varo took the harder path. It began pursuing its own national charter in 2017 and received it in 2020, a process of roughly three years and heavy capital spend. By contrast, the Chime Stride Bank route skips that slog. Chime is writing a check for a bank that is already chartered and already supervised. That also brings something Varo never had: a 113-year-old institution with its own OCC relationship and regulatory track record.
Chime Stride Bank Follows a SoFi Playbook
Chime is not the first fintech to buy its way in. SoFi agreed in March 2021 to acquire Golden Pacific Bancorp, a Sacramento bank with about $150 million in assets, for $22.3 million. It completed that deal in February 2022, close to a year after signing. However, Chime is buying something very different. Stride is a profitable, well-capitalized bank where Chime accounts already make up a significant share of deposits. That scale gap shows how far the challenger banking sector has matured since 2021.
Is $590 Million a Good Chime Stride Bank Price?
Whether $590 million is a good price depends on what sponsor-bank fees were costing Chime, and on how much the OCC slows the process. A 1.5x tangible book multiple is not outlandish for a small national bank. Moreover, Chime is growing fast enough to make the accretion math work, even if synergies land under $100 million.
One detail in the release deserves attention. Chime says it will keep bank assets below $10 billion for the foreseeable future. That is the threshold above which the Durbin Amendment caps debit interchange fees, a core revenue source for a card-led neobank. Put simply, the charter comes with a size ceiling Chime intends to respect.
The Compliance Trade in the Chime Stride Bank Deal
The bigger question cuts the other way. Chime becomes a bank holding company and takes on a national charter’s compliance obligations directly. The Bancorp still holds Chime member deposits today, but Chime plans to consolidate its banking at Stride after closing. It also inherits Stride’s other fintech partners. As Banking Dive reported, those include Affirm, which one analyst flagged as added execution risk.
That is the trade neobanks eventually make once they decide they are done paying rent. With the Chime Stride Bank agreement, Chime has decided the OCC’s blessing is worth the exposure.
What to Watch After Chime Stride Bank
Watch the OCC and Fed approval timeline. A clean first-half 2027 close would land within about ten months of signing. That would match SoFi’s pace on a bank a fraction of Stride’s size. Any delay will show how nervous regulators are about a neobank that listed in June 2025 taking over its own national charter.
Fintechbits covers neobanks, bank charters and fintech M&A. Nothing here constitutes financial or investment advice. All analysis represents the editorial views of Fintechbits.