5 mins read
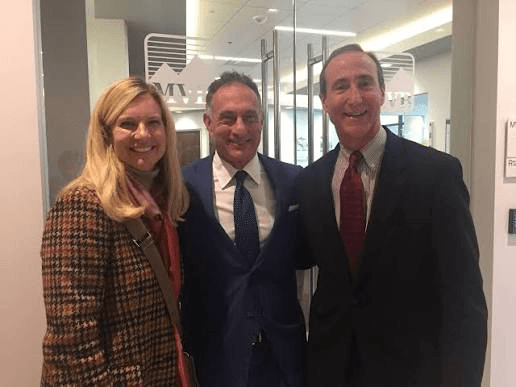
MVB Bank and DingoBlu Financial announced a strategic partnership on September 25, 2026. MVB will provide the regulated banking behind the planned DingoBlu mobile app. That covers checking and savings accounts and a Visa debit card program. Under the MVB Bank DingoBlu partnership, MVB holds the deposits and the regulatory relationship. DingoBlu builds the app customers will use.
DingoBlu, based in Charlotte, North Carolina, calls itself a financial technology company, not a bank. The release is explicit that banking services will come from MVB Bank, Member FDIC.
Nothing has launched yet. The release lists planned features, including account options, digital account tools and Visa debit access. Rates, fees, terms and availability will come closer to launch.
What the MVB Bank DingoBlu Partnership Covers
In the sponsor bank model, a fintech builds the app and the customer experience. A chartered bank holds the deposits and issues the card program on a network. It also carries the relationship with regulators such as the FDIC. DingoBlu is a Visa fintech partner. In the MVB Bank DingoBlu partnership, its debit cards will run on the Visa network through MVB, not through a charter of its own.
Many consumer fintechs, Chime among them, reached the market this way without becoming banks. The model has also drawn heavy regulatory scrutiny. In 2024 alone, regulators issued consent orders to several banks that serve fintechs. They included Sutton Bank, Piermont Bank, Lineage Bank and Thread Bank, according to a Banking Dive tracker. A sponsor bank answers for a partner’s compliance failures even when the partner built the customer experience.
MVB Built a Business Around Being the Sponsor
MVB has made fintech sponsorship a core line. It describes itself as powering fintech programs in payments, card issuance, sponsorship lending and online gaming. It also runs traditional retail and commercial banking. MVB Financial trades on Nasdaq under the ticker MVBF.
Larry Mazza, president and CEO of MVB Financial, called the bank’s fintech experience and regulatory capabilities the foundation for the MVB Bank DingoBlu partnership. MVB is also investing in automation behind that business. In August it said it had picked Bretton AI to run its back-office operations as it scales its fintech business.
DingoBlu is the newest name on the MVB roster. The deal adds a consumer deposit program at a time when sponsor banks are expected to police their partners closely. How MVB oversees DingoBlu will matter as much as the app itself.
What DingoBlu Is Betting On
A mobile app offering checking, savings and a debit card is not a differentiated pitch on its own. The MVB Bank DingoBlu partnership solves the banking side, not the question of why customers would come. Neobanks built on this model have launched in large numbers over the past decade. Many have struggled to give customers a reason to move their main account from an incumbent bank.
DingoBlu CEO Thomas Ulry said the deal brings the company “one step closer to introducing the DingoBlu experience.” He also stressed a simple and intuitive client experience. The release names no target customer, fee structure or feature that would pull customers from an existing account.
That is normal before launch. So the MVB Bank DingoBlu partnership is, for now, a sponsor bank deal described in neobank language. It is not yet a neobank with a clear wedge.
Why the Bank Relationship Matters First
What is verifiable in the MVB Bank DingoBlu partnership is the banking relationship itself. Getting a sponsor bank signed, priced and through compliance review is slower and more consequential than building an app. It determines whether DingoBlu can move money once the app is ready.
Some larger fintechs have chased their own charters to gain more control over that relationship. DingoBlu is taking the more common and more capital-efficient path for a company at its stage. It is leaning fully on a sponsor.
The trade-off in the MVB Bank DingoBlu partnership is dependence. If the sponsor tightens its risk appetite or faces supervisory pressure, the fintech has limited room to respond. For a pre-launch company, that is usually a price worth paying to get to market. A charter application can take years and needs far more capital than an early-stage fintech usually has.
What to Watch
As of September 28, DingoBlu had not announced a launch date, pricing or account terms since the partnership was signed.
The milestone to track is whether DingoBlu names a launch date, fee structure or target customer in the coming weeks. A signed sponsor bank relationship is a precondition for a neobank launch. It says nothing yet about whether DingoBlu has found a reason for anyone to switch. MVB investor updates are the most likely place for any follow-up on the scale of the MVB Bank DingoBlu partnership.
For related coverage, see how Eclipse Bank picked Lumin for its digital banking, how Tekion built banking into dealer software with a partner bank, and why CSI bought Qolo.
FintechBits covers payments, banking and fintech developments for readers in the US and UK. This article is for information only and is not financial advice. Views expressed are those of the FintechBits editorial team.