6 mins read
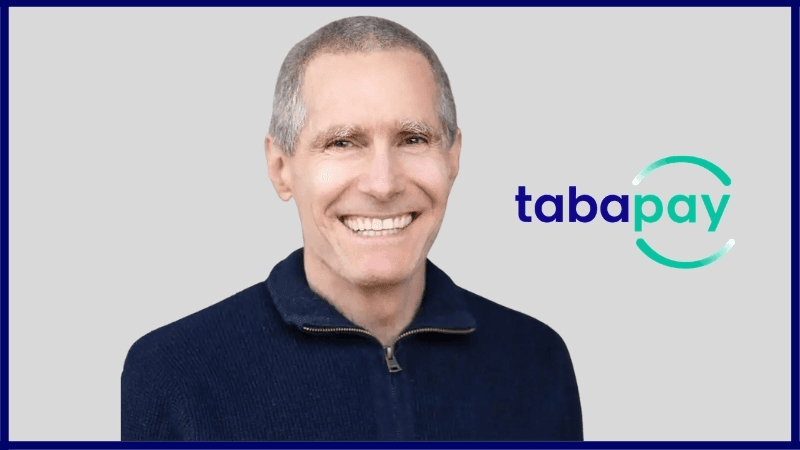
TabaPay bank charter ambitions stopped being theoretical on September 2. The payments processor closed a $155 million strategic growth financing round led by FTV Capital and confirmed plans to acquire Transact Bank, N.A., an OCC chartered and FDIC insured bank in Denver. Once the deal closes, Transact becomes TabaBank, N.A. and sits alongside TabaPay under a newly formed holding company, TabaHoldings, Inc. The round combined primary capital with a secondary sale of existing shares. Robert Anderson, a partner at FTV, has joined the board.
TabaPay built its business on instant payments and payouts, running a single API across card and bank rails that it says cuts client costs by as much as 75%. The company works with more than 20 partner banks across the U.S. and Canada. It expects to process over $100 billion in payment volume this year, and it claims fifth place among card not present processors in the U.S. by transaction count. Roughly a third of American households touch its rails in some form, according to the announcement.
Meanwhile the operational detail is unusually specific for a deal announced this early. CEO and co-founder Rodney Robinson framed the purchase as bringing “payments and banking capabilities under one roof.” TabaBank is expected to support RTP, FedNow, ACH, wire transfers, and card sponsorship across Visa, Mastercard, Discover, and regional networks. FT Partners advised TabaPay, Reed Smith served as its legal counsel, and Gibson, Dunn & Crutcher represented FTV. Closing is targeted for the fourth quarter of 2026.
What the TabaPay Bank Charter Deal Really Buys
Here is the detail that reframes everything. Transact Bank held roughly $6.4 million in assets, according to FDIC call reports cited by American Banker. That is not a bank being bought for its deposits, its branches, or its loan book. So the TabaPay bank charter play is better understood as a purchase of permission.
Then there is speed. A de novo charter application can run for years and frequently ends in nothing, while buying a small national bank converts the problem into a change of control review. Instead of asking supervisors to create something new, TabaPay is asking them to approve a new owner for something that already exists. That is a meaningfully easier question to put in front of a regulator.
Still, a small balance sheet does not make the licence cheap. What matters in the TabaPay bank charter transaction is what the permission unlocks, and that list is long: direct network access, deposit insurance, and sponsorship capability the company currently rents. TabaPay says it expects TabaBank to qualify as an acquirer across the major card networks, which would let it sponsor merchants, ISOs, and payment facilitators without a middleman. Anyone tracking the future of payments has watched this consolidation coming.
Fintechbits analysis
Why the TabaPay Bank Charter Ends Sponsor Dependency
This is the move that separates a payments company from a company that owns the rails it rides on. Fintechs have spent a decade renting bank relationships through sponsor banks, a model that works right up until the sponsor has a bad exam or decides your risk profile isn’t worth the hassle. A TabaPay bank charter removes that dependency and lets the company set its own underwriting standards instead of inheriting someone else’s compliance appetite.
And TabaPay knows the failure mode from the inside. Back in 2024 it agreed to buy the assets of Synapse Financial Technologies out of Chapter 11, a deal that fell apart and left the middleware layer between fintechs and their sponsor banks as the cautionary tale of the cycle. Seen against that history, the TabaPay bank charter reads as a structural answer rather than an opportunistic one.
By comparison, the precedent is well established among challenger banking innovators. SoFi acquired Golden Pacific Bancorp in February 2022 specifically to secure a national charter, and Cross River built an entire business model on being the bank behind other people’s fintech products. Yet the TabaPay bank charter ambition points somewhere slightly different. TabaPay wants to be both the infrastructure layer and the bank.
The TabaPay Bank Charter Faces a Capital Test
But the catch is capital. Banks are capital intensive in a way payment processors are not, and the SoFi comparison cuts both ways here. SoFi paid about $22.3 million for Golden Pacific, then committed $750 million in fresh capital to the resulting bank as a condition of OCC approval. Golden Pacific held roughly $150 million in assets at the time, more than twenty times what Transact holds today.
So TabaPay bank charter economics come down to how much of the $155 million supervisors expect to sit inside the bank. The raise has to cover the purchase, the capital TabaBank must hold, and the product roadmap the company says the money will fund. Meanwhile the true cost of capital looks very different once a balance sheet is involved. Processing $100 billion in volume is a different animal from taking deposits.
Regulators Will Decide the TabaPay Bank Charter Timeline
Buying a bank means TabaPay now answers to supervisors in ways a pure processor never had to. Banking Dive reported that the transaction needs sign off from the Office of the Comptroller of the Currency and, because TabaHoldings would become a bank holding company, from the Federal Reserve as well. That is two approvals rather than one, and the TabaPay bank charter cannot close until both land.
Even so, precedent suggests the answer is rarely a clean yes. SoFi received conditional approval carrying a capital floor and activity restrictions. Regulators have grown more comfortable with fintech ownership of banks since then, though comfort is not the same thing as speed. The one roof framing also tends to undersell how much integration work sits between signing and running a bank well.
FTV clearly likes the bet, and a board seat for one of its partners suggests it plans to stay close to the work. Analysts have made the point more politely. West Monroe’s Tom Collins told American Banker that mature fintechs are increasingly weighing whether to own more of the banking stack themselves, which is a question rather than a conclusion. Whether TabaPay can run a bank with the same discipline it has brought to payments is the real test, not the press release.
So watch the Federal Reserve and the OCC. The TabaPay bank charter timeline now rests on change of control approvals sitting with both agencies, and their pace will signal whether the targeted fourth quarter close holds or slips into 2027.
Fintechbits covers payments infrastructure, banking licences, and fintech capital markets. Nothing here constitutes financial or investment advice. All analysis represents the editorial views of Fintechbits.