6 mins read
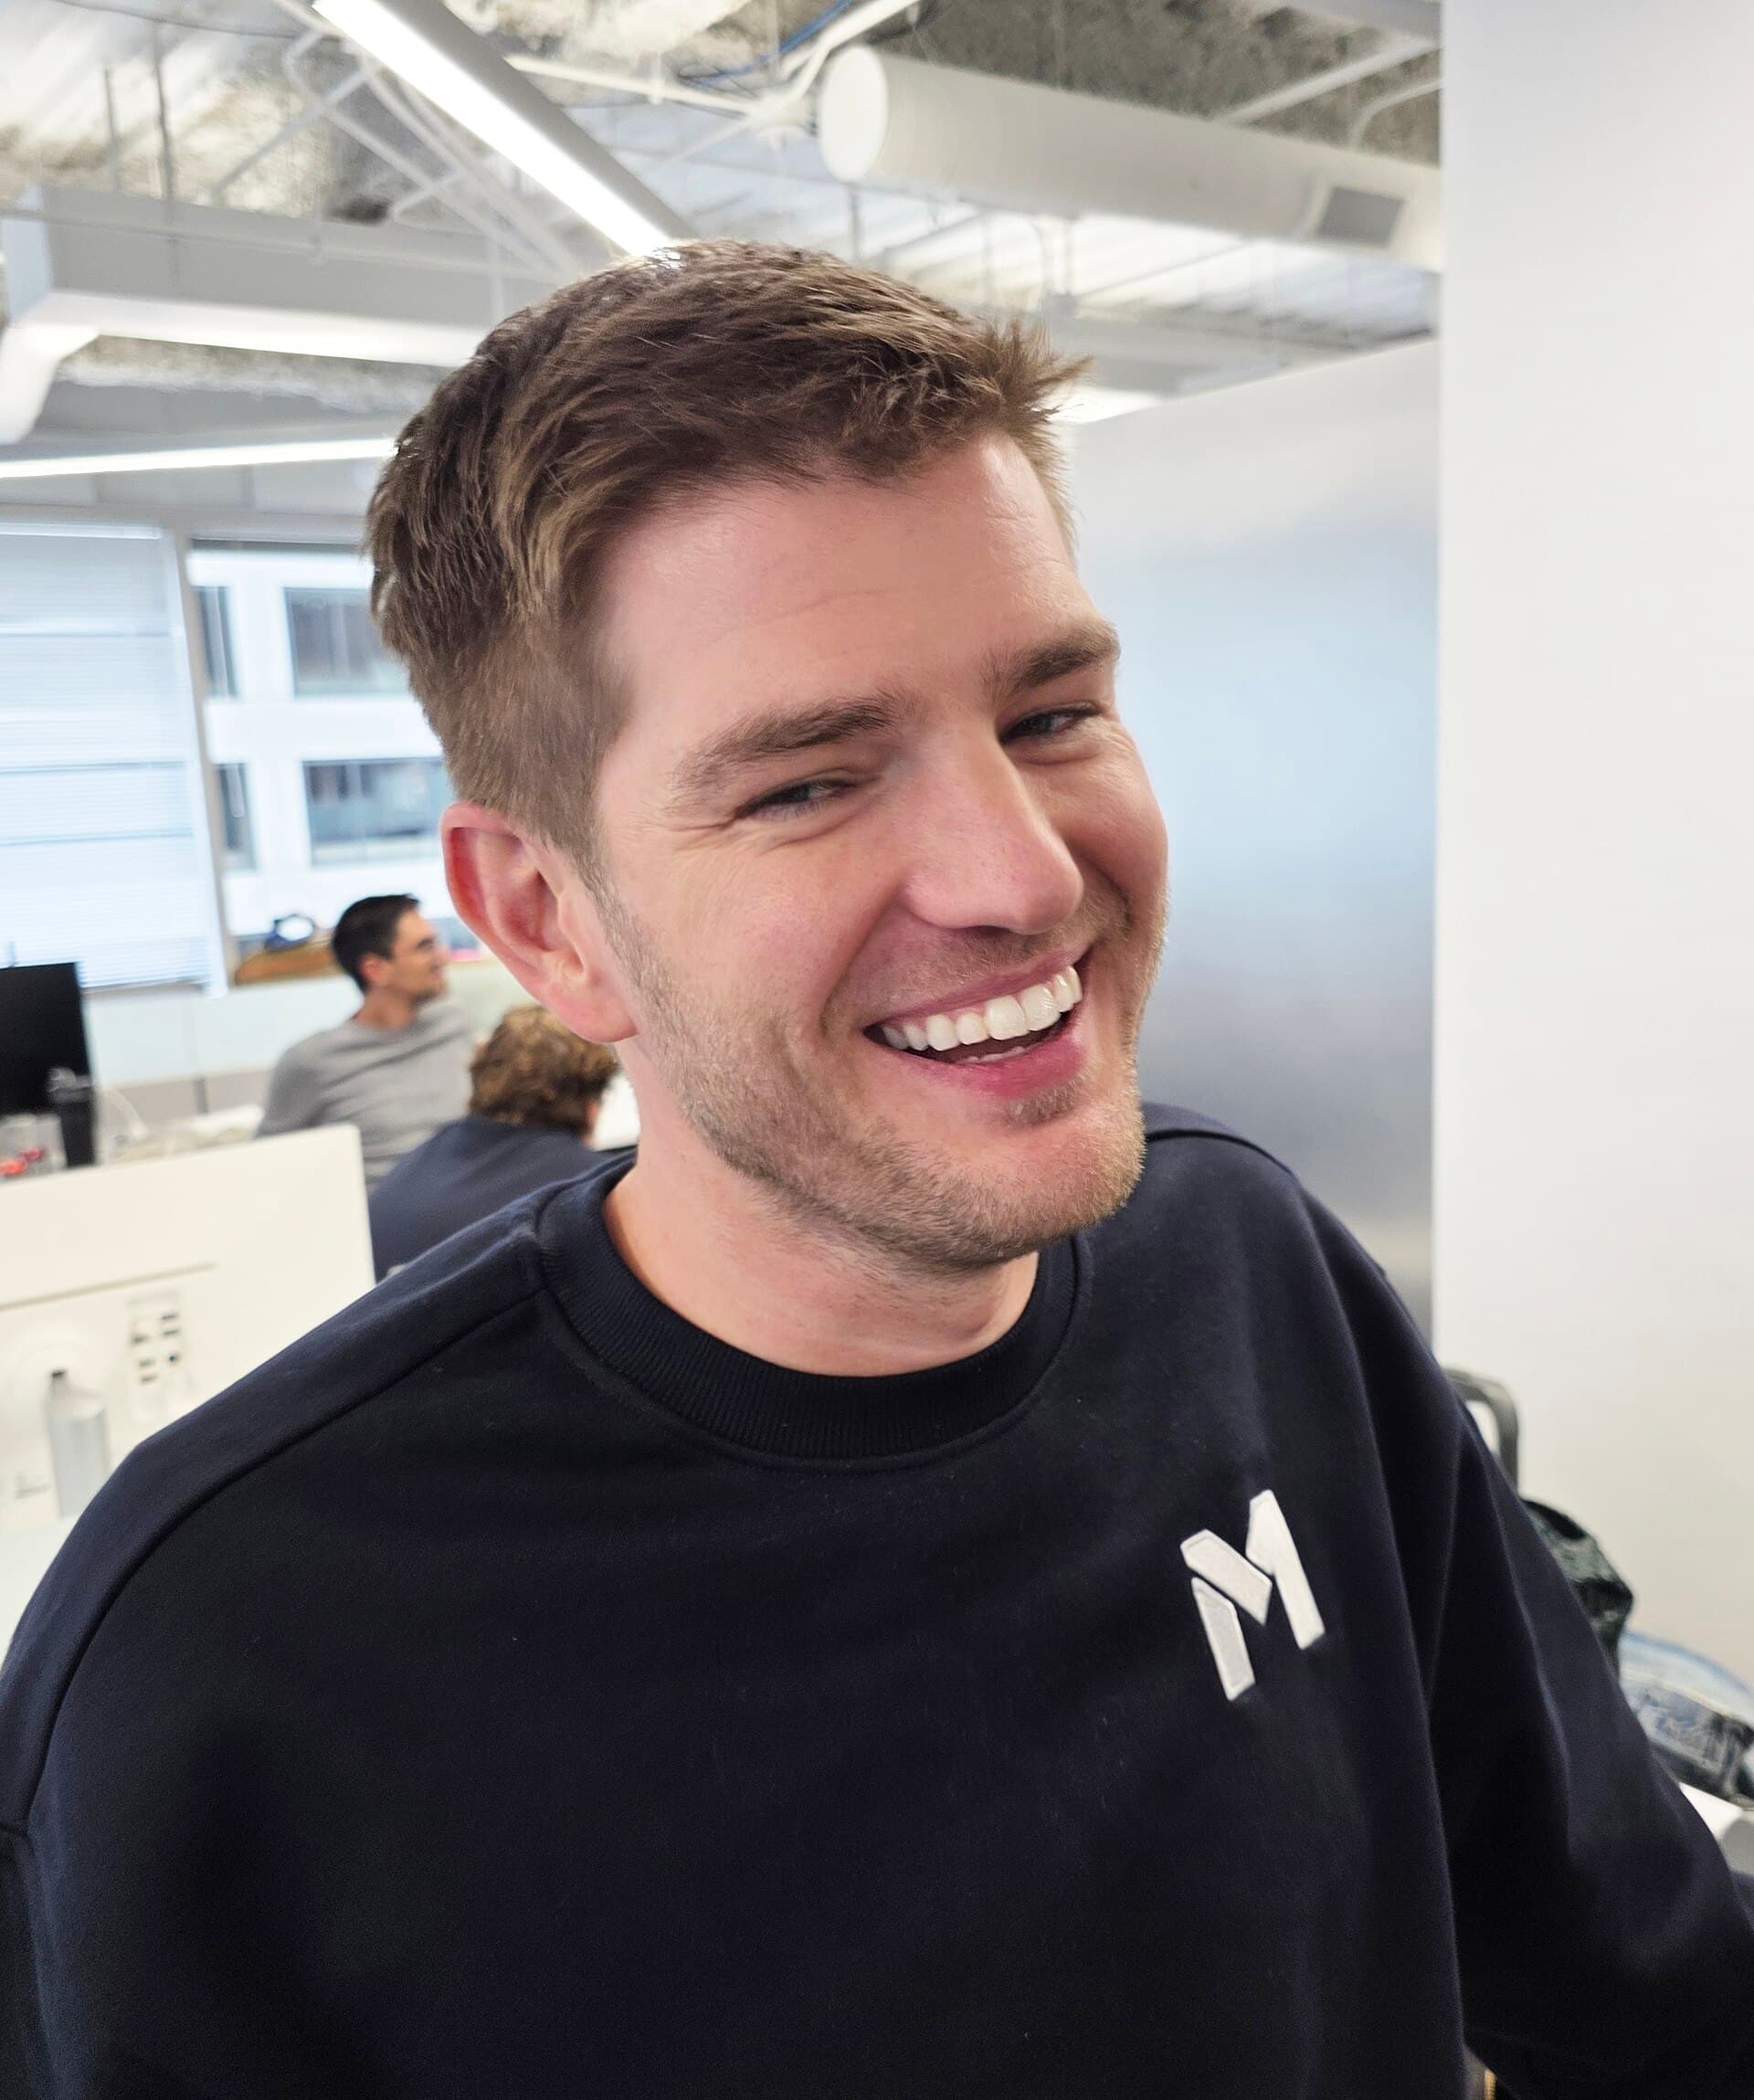
M1, the Chicago-based investing and borrowing platform, launched M1 Advisor on 6 October 2026. M1 Advisor is an AI financial adviser offered through M1 Advisory Services, LLC, which is registered with the SEC as an investment adviser and owes clients a fiduciary duty on the advice it gives. According to the company’s release, M1 Advisor costs M1 clients nothing until 31 December 2027, and enrollment is opt-in.
What M1 Advisor can and cannot do
M1 Advisor can see the balances, holdings and interest rates on every account a client has at M1, covering investing, cash and borrowing. Through Plaid, clients can link accounts held elsewhere, such as a mortgage, a loan, an IRA or a 401(k). M1 says the linked accounts help the adviser see the whole picture when it gives advice about a client’s M1 accounts.
The adviser is non-discretionary. It answers questions and gives advice, but it cannot act on its own, and the client decides whether to follow the advice. It remembers goals, constraints and past decisions across conversations, and clients can edit, save or delete that memory, or switch it off. M1 says client personal and financial data is not used for training AI models, whether M1’s own or third parties’.
M1 describes itself as an AI wealth management company. It says it has $14 billion in client assets on its platform and more than 400,000 clients, figures it gives as of September 2026. Brokerage is provided by M1 Finance LLC, a FINRA and SIPC member, which is a separate entity from the advisory firm.
Fintechbits analysis
Why the fiduciary label on M1 Advisor matters
Many AI money tools avoid giving advice. They describe themselves as education or guidance, and their terms of service make clear that nobody is responsible if the suggestion is wrong. M1 takes the opposite approach, and the details are on its product page. M1 Advisory Services owes clients duties of care and loyalty, and it discloses conflicts of interest in Form ADV Part 2A and Form CRS, keeps records of the advice given, and can be examined by the SEC.
That changes who is accountable. If the AI gives unsuitable advice, a registered adviser is responsible for it, and the records exist for regulators to review. Founder and CEO Brian Barnes framed the launch around this point, saying M1 Advisor gives “advice built on their actual accounts, under the same fiduciary duty a human advisor owes them.” Whether an AI system can meet that duty consistently is an open question, but M1 has chosen to be judged on it, which many AI money apps avoid.
Why the conflicts are the part to read closely
A fiduciary must put the client first, and M1 has products it would like clients to use. The platform offers margin loans and personal loans as well as investing and cash accounts. An AI adviser that knows a client’s mortgage rate, outside retirement savings and M1 cash balance will regularly face questions where an M1 product is one possible answer, such as borrowing against a portfolio or moving cash into an M1 account.
Being a fiduciary does not prohibit conflicts. It requires the adviser to disclose them and act in the client’s best interest anyway. Clients considering the service should read the Form ADV Part 2A section on conflicts, because that is where M1 explains how it handles them. The release also notes that the adviser advises on M1 accounts, with outside accounts used for context. A client looking for advice on their whole financial life, such as how to allocate a 401(k) held elsewhere, may find the scope narrower than the marketing suggests.
Why price is M1 Advisor’s strongest selling point
The release says human advisers usually charge about 1% of assets annually, and that the average flat-fee or retainer arrangement costs $6,815 a year, based on Envestnet’s 2026 fee study. The service costs nothing until the end of 2027, although M1’s existing $3 monthly platform fee still applies to clients holding under $10,000 at M1 and no active personal loan.
Other firms are making similar bets. Bill Harris launched the Evergreen.ai financial advice app, which is also free into 2028, as Fintechbits reported. Earlier waves of robo-advice cut costs without closing the advice gap, a history Fintechbits examined in why robo-advisory did not close the advice gap. The difference with M1 Advisor is conversation and context: the earlier robo-advisers ran model portfolios, while M1 is offering answers to specific questions based on a client’s actual balances and debts.
What to Watch Next on M1 Advisor
The first thing to watch is M1’s Form ADV filing for M1 Advisory Services, which should describe how the AI adviser handles recommendations that involve M1’s own lending products. The second is the pricing decision for 2028. M1 has promised at least 30 days’ written notice of any change and the right to cancel without penalty, so the move from free to paid will show what clients think the advice is worth. Regulators may get there first: an SEC examination of an AI adviser that owes a fiduciary duty would test whether that duty can be met in practice, and M1 Advisor is now an obvious candidate.
Questions and answers
What is M1 Advisor?
M1 Advisor is an AI financial adviser M1 launched on 6 October 2026. It is offered by M1 Advisory Services, an SEC-registered investment adviser that owes clients a fiduciary duty.
How much does M1 Advisor cost?
M1 clients pay nothing for the service until 31 December 2027. M1 has promised at least 30 days’ written notice of any price change.
Can M1 Advisor trade on my behalf?
No. The adviser is non-discretionary, so it answers questions and gives advice but cannot act on its own, and the M1 client decides whether to follow it.