5 mins read
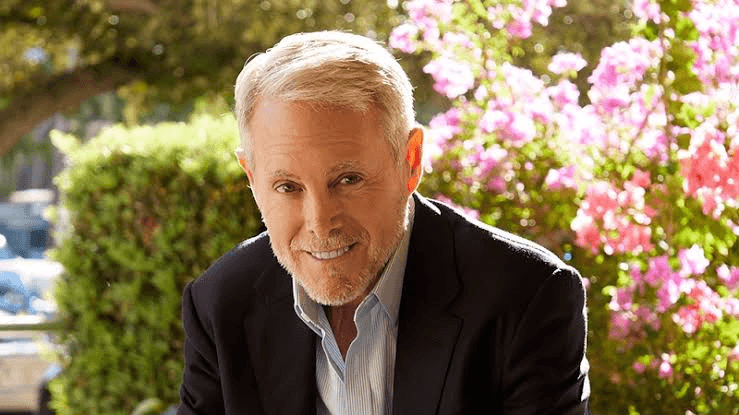
Bill Harris launched Evergreen.ai on September 21, 2026. He is the former chief executive of PayPal and Intuit and the founding chief executive of Personal Capital. The app runs on mobile and desktop browsers and answers questions on planning, retirement, equity compensation and tax. Consumers who register during the beta get it at no cost through January 1, 2028. The service is offered through Evergreen Wealth Advisors, an SEC-registered investment adviser.
Harris has founded eight financial technology companies. Personal Capital, the closest precedent to this one, grew to $23 billion in client assets under management, according to the release.
Where the Arithmetic Happens
The claim worth examining here has nothing to do with the chat interface. It concerns which part of the system produces the numbers.
Evergreen pairs a language model with what the company calls a deterministic calculation engine. The tax and financial math runs in the engine rather than in the model. Bryan Godwin, co-founder and chief technology officer, has seven pending patents on the platform. He frames it directly: probabilistic models handle communication, deterministic software produces the numbers.
This is the correct division of labor, and it is not the default in AI financial tools. A general-purpose chatbot asked to compare a Roth conversion across two tax years will produce a figure that looks authoritative, varies between sessions, and cannot be reconciled afterward. That is tolerable when someone is idly curious. It is a genuine problem when the answer feeds a decision with a filing deadline attached. Any advice that involves a number is only as good as whether that number is reproducible. Routing it outside the model is how you make it so.
Who Evergreen Is Aimed At
Harris cites a 2024 YouGov survey finding that 73% of American adults do not use a financial adviser. His read is that those people are not going without advice. They are getting it from general-purpose chatbots that lack their financial data, produce unreliable numbers, and carry no duty to them.
That read is right, and it is the part of this launch that matters beyond one app. The advice gap is not closing because advisers got cheaper. It is closing because free tools that will answer any question turned up. The quality bar those tools set has become the floor everyone else has to clear. We looked at the same dynamic in coverage of the hybrid model closing the advice gap and in Wealthstream’s voice AI adviser tool. Britain is attacking the same gap from the regulatory side through targeted support.
The Fiduciary Wrapper
The regulatory wrapper is the differentiator Harris can claim and a chatbot cannot. Evergreen Wealth Advisors is an SEC-registered investment adviser and a fiduciary. That is a real distinction, and the disclosure attached to the release is honest about its limits. The platform provides general education and calculators, and may provide personalized advice when a user shares enough about their finances.
The same disclosure states that the service is not tax counsel. That sits awkwardly beside an app whose headline feature is tax math, and it is worth reading before anyone acts on a Roth conversion figure.
What the App Covers
Evergreen’s tool set spans cash flow and retirement projections, securities prices and watchlists, and equity compensation including options, RSUs, founder stock and QSBS. It also covers net worth tracking across linked accounts, mortgage and rent-versus-buy analysis, and retirement account mechanics including Roth conversions. College savings and tax strategies such as loss harvesting and charitable giving round it out.
QSBS and founder stock in a consumer app aimed at everyday Americans is a revealing inclusion. Those are startup employee questions, and they are where free general-purpose tools fail most expensively. It suggests the early user Evergreen expects is more affluent and more technical than the framing implies. That fits the paid business Harris already runs. Evergreen Wealth, launched about a year ago, targets affluent and high-net-worth clients.
Account linking runs through Plaid, so bank credentials never reach the model. User data is encrypted, not sold, and not used to train public models.
Free Until 2028 Is a Real Bet
Giving Evergreen away for more than two years is not a promotional gesture. It is a cost decision that has to be defended internally. Inference on personalized financial queries, combined with Plaid aggregation fees on every linked account, produces a per-user cost that does not fall to zero at scale.
Harris is buying two things with that spend: a data set of real financial situations to tune against, and habit. The stated mission is “better advice to more people at lower cost,” and the unstated question is what happens on January 2, 2028. The release does not say whether that means a subscription, an advisory fee on assets, or a referral into the managed offering. Personal Capital ran free tools as the front of a managed money business. Here the managed business already exists, which makes that template look less like a guess.
What to Watch
The number that will tell you whether this works is not downloads. It is whether Evergreen publishes anything about accuracy, because the whole pitch rests on a claim of verifiable output that no competitor substantiates either.
A published benchmark of the Evergreen engine against known tax scenarios would be the strongest move available to Harris. The absence of one after a few months would suggest the architecture is more positioning than proof. Watch also for the first disclosure of post-beta pricing, which will say more about the business than the launch did. AI assistants for retail investors are multiplying, and verifiable accuracy is the one claim that would set this one apart.
Fintechbits covers AI in financial services, wealth technology and consumer finance. Nothing here constitutes financial or investment advice. All analysis represents the editorial views of Fintechbits.