6 mins read
In the middle of 2017, Chris Britt had six to nine months of cash left and an offer on the table. A large, publicly traded tech company had informally offered to buy Chime, the digital banking start-up he had co-founded five years earlier, for $60m to $70m. He and his co-founder, Ryan King, turned it down, according to a 2024 Forbes account of those years. Nine years on, Chime is a listed company with more than 10 million active members, and in September it agreed to buy Stride Bank, one of the banks behind its accounts.
A working-class start in Mount Vernon
Chris Britt grew up in an apartment in Mount Vernon, New York, just north of the Bronx, with his mother and two siblings, he told ICONIQ in 2025. His parents divorced when he was five, and neither had been to college. His mother sold Electrolux vacuum cleaners door to door and sent him into Manhattan on his own to audition for adverts, and he appeared in a 1977 Burger King commercial.
The man who changed his path lived in the flat downstairs. Joe Sonneborn, a Second World War veteran, looked after him after school. “He took me under his wing, like a grandfather would,” Chris Britt told American Banker in September. Sonneborn paid the part of his fees at Rye Country Day School that a scholarship did not cover, and later put tens of thousands of dollars towards Tulane University, where Britt graduated in 1995 with a history degree.
Chris Britt and the direct deposit idea
His early career ran through Accenture, the ad tech start-up Flycast, Comscore and Visa. In 2007 he joined Green Dot, the prepaid debit card company, and was its chief product officer when it went public in 2010.
Green Dot is where he found the idea behind Chime. Customers whose wages were paid straight onto its cards used them for nearly everything. “The people on direct deposit were clearly the whales of the business,” he told Forbes. Then Wells Fargo said it would start charging $7 a month on checking accounts that had been free, unless customers kept a minimum balance or set up direct deposit. As Forbes later put it, the message was that the big banks did not want the kind of people Chris Britt grew up with, the ones living pay cheque to pay cheque. That year, 2012, he founded Chime with King, a software engineer who had spent a decade at Plaxo.
A hundred rejections and an offer to sell
The first version missed. Chime launched its debit card in April 2014 with shopping rewards and coupons as the hook, and told investors it would have 150,000 cardholders by the end of 2015. Research by Melissa Alvarado, an analytics hire who later became chief marketing officer, showed that new cardholders were not setting up direct deposit. Chris Britt changed course, but the detour cost more than a year, and by the end of 2015 Chime had about 7,000 active users.
In early 2016 the founders tried to raise an extension to their Series A and, King told TechCrunch, heard no from about 100 investors. Lauren Kolodny, then at Aspect Ventures, led a $9m round at a flat $34m valuation; King says hers was the only term sheet they had. The following year brought the cash squeeze and the offer they declined, before Cathay Innovation led an $18m round.
The features that made Chime click
From 2018, Forbes reported, the product began to catch on. Members could get their pay up to two days early, something banks had little reason to offer because it cost them float. Chime also had no overdraft fees, and in 2019 it launched SpotMe, which lets members overdraw by up to $200 with no interest or late fees. The same year an outage at its payment processor left about 500,000 members without access to their money for several hours. Chris Britt has said that episode is what convinced Chime to run its own core technology.
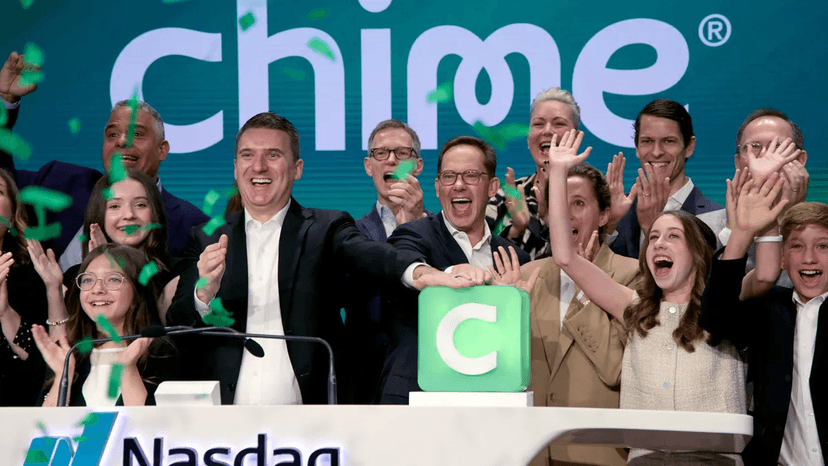
Chime priced its shares at $27 on 11 June 2025, according to its IPO announcement, and began trading on Nasdaq under the ticker CHYM the next day, closing at $37. In the first quarter of 2026 it reported net income of $53m, its first quarter of GAAP profit as a public company.
How Chris Britt thinks about running Chime
Peers and investors often describe him as humble, and Forbes found that he considers himself an outsider: he did not go to Stanford or an Ivy League university. He told American Banker in September 2026 that the mission has never really changed, and that Chime was built from the start for everyday consumers like the people he grew up with in Mount Vernon.
In an interview with ICONIQ released the day Chime listed, Chris Britt said the job starts with hiring very talented people, being clear about the mission early even when survival seems more pressing, and being ready to make tough calls, including moving quickly when a hire is not working out.
He told Forbes that the early struggles helped in the long run, and that nobody would out-hustle Chime. He also founded the Chime Scholars Foundation, through which the company has pledged 1 per cent of its equity to pay for college and other education, according to its investor relations site.
What to Watch Next for Chris Britt and Chime
On 8 September Chime agreed to buy Stride, its partner bank for more than seven years, for $590m in cash, as Fintechbits reported. Stride was founded in 1913, is based in Enid, Oklahoma, and will become Chime Bank, N.A. “We are at a size and a scale when we need to have complete control of our destiny,” Chris Britt said that week, according to Banking Dive. Fintechbits has looked at what breaks when a fintech switches partner bank; owning the bank changes that relationship entirely.
The deal is expected to close in the first half of 2027, subject to approval by the Office of the Comptroller of the Currency and the Federal Reserve, according to Chime’s announcement. Those two approvals are the thing to watch. If they come through, Chime moves beyond the partner bank model described in our guide to neobanks, and Chris Britt, who started it after a big bank began charging people like the ones he grew up with, will be running a bank of his own.