5 mins read
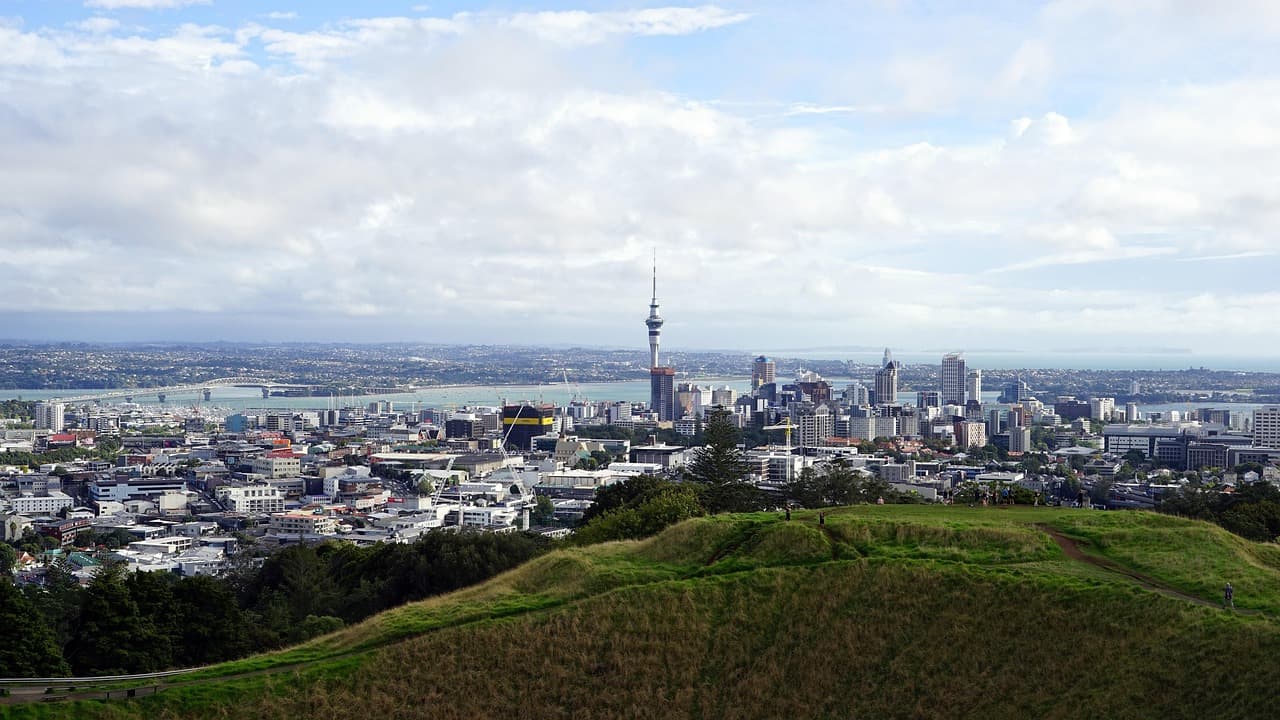
Revolut New Zealand was registered as a bank by the Reserve Bank of New Zealand on 3 November 2026, and Revolut has committed NZ$120 million to its local operations over five years. Fintechbits read the Reserve Bank of New Zealand notice in full: it makes Revolut Bank New Zealand Limited the country’s 27th registered bank, granted under the Banking (Prudential Supervision) Act 1989, which the Deposit Takers Act 2023 replaces on 1 December 2028 (RBNZ notice). Revolut’s own announcement mentions neither the bank count nor the change of regime.
What the Revolut New Zealand Registration Covers
Revolut New Zealand has operated as a financial services provider since July 2023, according to the central bank. Bank registration changes what that business can hold. Revolut says eligible deposits up to NZ$100,000 are covered by the New Zealand Depositor Compensation Scheme, and existing customers move across without having to do anything.
The first Revolut New Zealand product is a savings account rather than a lending book. Instant Access Savings pays a variable introductory rate of 3.50% a year for a new retail customer’s first four months, with daily interest and no withdrawal penalty. Revolut calls itself New Zealand’s first digital bank. That is the company’s description, and the central bank notice does not use it.
Nik Storonsky, Revolut’s founder and chief executive, called the registration the company’s seventh bank licence and its fifth of 2026. “Launching our New Zealand bank marks another significant step in our mission to build the world’s first truly global bank,” he said in the announcement. Ryan Brosnahan runs Revolut Bank New Zealand as chief executive.
The pace is real. Fintechbits covered Revolut’s full Australian banking licence in August, which came with a AUD $400 million commitment, and the Gibraltar crypto licence in October. The Revolut New Zealand commitment is smaller than both in money terms.
A 3.50% Rate Against a 2.75% Cash Rate
The launch rate is the hook, and it is priced aggressively. The Reserve Bank of New Zealand held the official cash rate at 2.75% on 27 October, so Revolut New Zealand is paying 75 basis points above the policy rate on new money.
That margin is affordable for four months on a small book. It is harder to sustain once the promotional period ends, and the release does not say what the rate falls to afterwards. A teaser that drops sharply after four months gathers deposits that leave again just as quickly.
Fintechbits analysis
Why the 1989 Act Matters for Revolut New Zealand
The registration is a genuine competitive step. New Zealand banking is concentrated, and a deposit-taking entrant with depositor compensation behind it gives savers a credible alternative to the incumbents. On that point Revolut’s competition claim holds up.
The less noticed detail is the legal basis. Revolut New Zealand was registered under the 1989 Act, and the central bank says the licensing regime for deposit takers will soon be replaced by the Deposit Takers Act 2023, in force from 1 December 2028. Every existing bank faces that transition, so it is not a mark against Revolut. It does mean the company’s first two years as a New Zealand bank double as preparation for a second licensing process under new prudential standards.
The NZ$120 million pledge also needs context. Spread over five years it averages NZ$24 million a year, which funds a product and operations team. It does not fund a balance sheet, and that will come from deposits. The savings rate exists to collect those deposits.
Revolut’s pattern in Australia was similar: a licence, a large investment number and a deposit-led launch. The test in both markets is what the bank does with the money once it holds it.
Frequently asked questions
Is Revolut New Zealand a fully registered bank?
Yes. The Reserve Bank of New Zealand registered Revolut Bank New Zealand Limited on 3 November 2026 under the Banking (Prudential Supervision) Act 1989. Eligible deposits up to NZ$100,000 are protected by the Depositor Compensation Scheme, according to Revolut.
What savings rate does Revolut offer in New Zealand?
Revolut launched Instant Access Savings with a variable introductory rate of 3.50% a year for new retail customers for their first four months. Interest is paid daily and there are no withdrawal penalties, according to the company.
How many bank licences does Revolut hold?
Nik Storonsky said the New Zealand registration is Revolut’s seventh bank licence and its fifth of 2026. Revolut says it operates as a licensed bank in 34 markets, which includes countries covered by its European licence.
What to Watch Next
The number to watch is the rate Revolut New Zealand pays once the four-month introductory window closes for the first cohort, at the start of March 2027. If it stays close to the cash rate, the deposits probably stay too. If it drops well below, Revolut will have bought customers for a season. Lending products and a timetable for Deposit Takers Act licensing are the next markers after that.