5 mins read
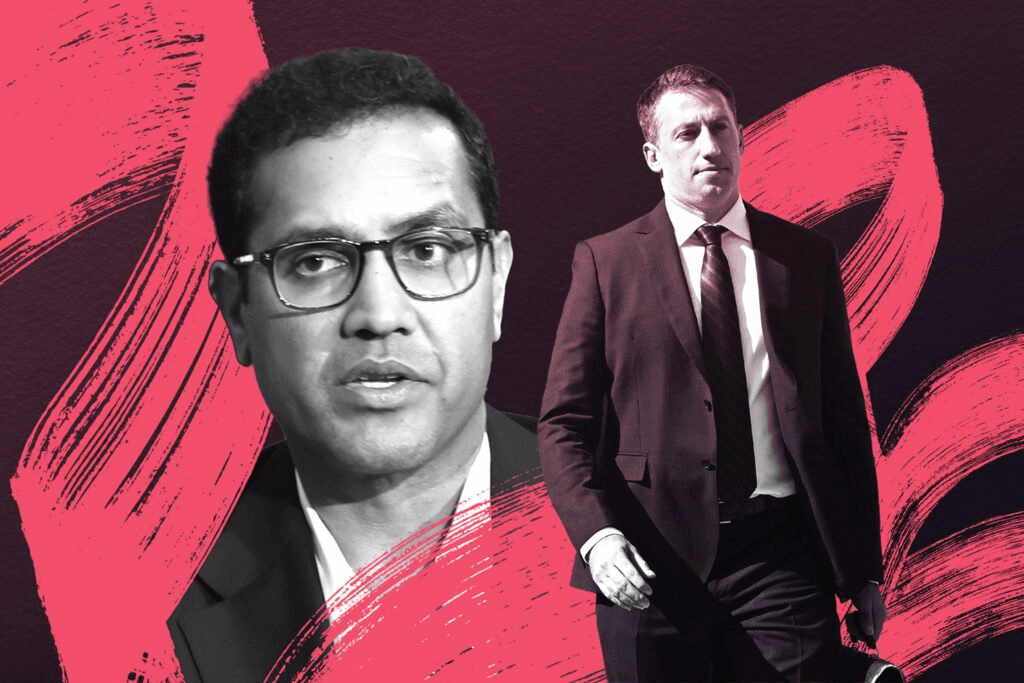
Better poison pill defences and the board that adopted them went before two courts in two states within days, and the outcome split. A federal judge in New York declined to block founder Vishal Garg from soliciting shareholder consents. Delaware’s Court of Chancery, hearing Garg’s own challenge, declined to suspend the rights plan or the special committee. So Garg keeps campaigning, and the board keeps its defences.
What the Better Poison Pill Rulings Really Decided
Neither Better poison pill ruling touched the merits. U.S. District Judge Margaret Garnett denied Better’s request for a temporary restraining order on 28 August, finding the company had not demonstrated irreparable harm, which requires an injury that is actual and imminent rather than remote or speculative. She pointed to Garg’s amended SEC filings, which incorporated Better’s own complaint, as giving shareholders enough of the factual dispute to judge it themselves.
Garnett was explicit that she made no finding on whether Garg’s filings comply with securities regulations, and noted this was not a case where the eggs would be hard to unscramble, signalling that corporate actions taken during the contest could still be unwound later. A denied restraining order means the solicitation continues. It does not mean the filings are clean.
In Delaware, Garg lost his attempt to disable the board’s defences. The Better poison pill and the special committee both stand.
How the Better Poison Pill Fight Reached Two Courts
The sequence is compressed. The board removed Garg as chief executive on 3 August, installing director Daniel Lewis as interim CEO. Garg began seeking written consents to remove five of eight directors and reinstate himself. Better sued him in the Southern District of New York on 18 August, alleging unlawful solicitation and disclosure violations tied to an undisclosed shareholder group.
The special committee adopted the rights plan on 20 August with Computershare as rights agent. It triggers if a person or group acquires 15% of any class of common stock or 15% of voting power, at which point other holders may buy shares at a discount and dilute whoever crossed. Garg sued in Chancery on 25 August, bringing breach of fiduciary duty and two declaratory judgment counts, arguing the Better poison pill and the committee were pretextual devices to thwart voting rights. He attacked the plan as overly broad, singling out a provision aggregating shares of anyone with an undefined arrangement or understanding, written or not.
Fintechbits analysis
Why the Better Poison Pill Survived in Delaware
This is where the popular reading of these rulings goes wrong. A narrative took hold that two courts in two states refused to let procedural defences substitute for a shareholder vote. Only one court ruled against the board. Delaware left the Better poison pill intact, and no court has found the rights plan improper.
That matters for how the contest proceeds, because the Better poison pill is the binding constraint now. Garg can solicit, but a 15% trigger still constrains how much voting power he or any aligned group can accumulate without dilution. The board lost the ability to pause his campaign and kept the instrument that limits its ceiling. Calling that a rout in either direction misreads the docket.
What the Better Poison Pill Battle Turns On Now
The company underneath the Better poison pill fight is not itself in dispute. Better’s board says the business accumulated more than $2 billion in net losses and lost over 90% of its value as a public mortgage lender during Garg’s tenure, and its shareholder letter characterises his campaign as self-serving and his slate as hand-picked.
Garg’s filings argue the reverse case: the stock fell 41.6% the trading day after his removal and roughly 60% by 21 August. He has proposed a $30 million buyback, a personal stock purchase, and a $1 salary until the company is profitable. He also says he was offered a role he considered without authority, and reporting on a $15 million offer from the company has complicated Better’s own case against him.
Then there is the arithmetic problem. Garg initially claimed his group held 51.65% of voting power, then revised it downward, attributing the gap to an administrative error based on data the company itself supplied. Reporting puts the corrected consent figure near 45%. Anyone citing a smaller number should check which measure it describes, because consents gathered and group beneficial ownership are different quantities and the two get conflated constantly in coverage of this fight.
So the Better poison pill contest returns to arithmetic rather than argument. Whoever assembles a genuine majority of voting shares wins, and both the governance credibility of the board and the accuracy of the founder’s own vote counting are now part of what shareholders are being asked to weigh, alongside an AI mortgage platform that neither side disputes has value.
Fintechbits covers mortgage technology, fintech governance and consumer lending. Nothing here constitutes financial or investment advice. All analysis represents the editorial views of Fintechbits.