6 mins read
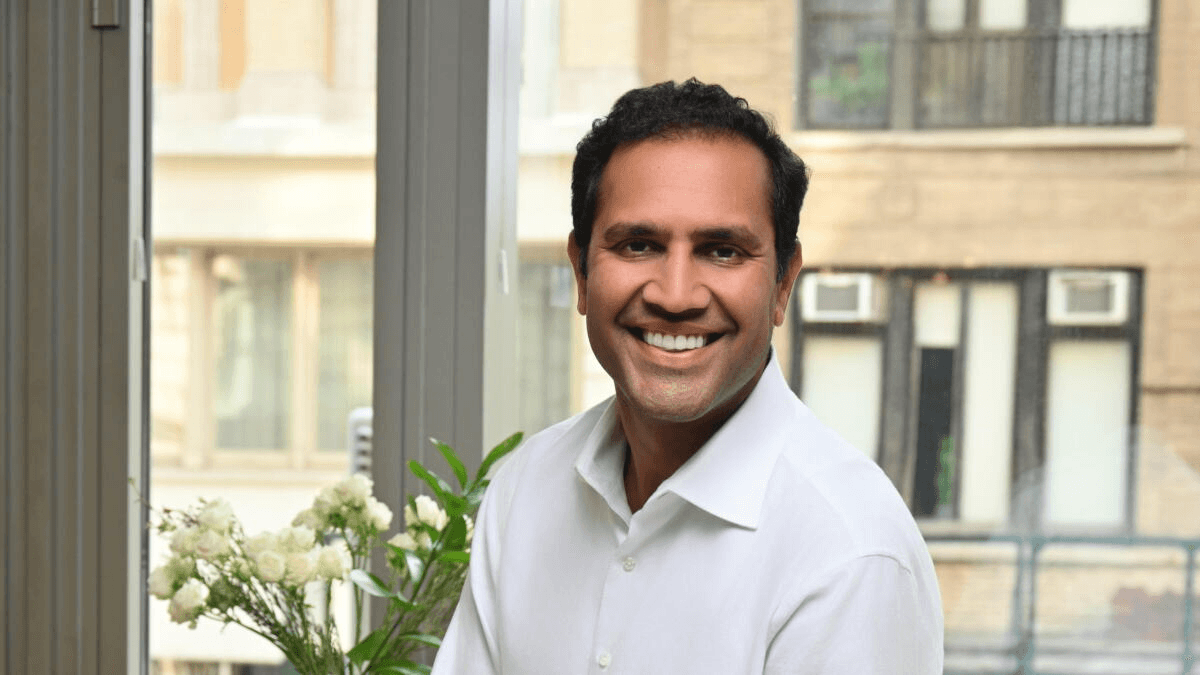
Vishal Garg says more than 46% of Better Home & Finance voting power now backs his campaign to remove five directors. Garg, the founder and former chief executive of the Nasdaq-listed digital mortgage lender, made the claim on September 21, 2026. The Better consent solicitation is working toward a target date of October 2. It needs a majority of outstanding voting power, not a majority of votes cast.
The five directors named for removal include Daniel Lewis, Better’s interim chief executive, alongside Harit Talwar, Arnaud Massenet, Bhaskar Menon and Prabhu Narasimhan. Garg has put forward Bing Gordon, David Heidecorn and Steve Sarracino as potential replacements.
Why 46% Is a Harder Number Than It Sounds
Consent solicitations are unforgiving in a way proxy contests are not. In a normal contested election, abstentions and unreturned cards mostly fall away, and the contest is decided among shares that vote. Here, every share that does not return a green card counts as opposition by default.
Garg also started well ahead. His group entered the consent solicitation holding about 13.7% of the voting power. Much of that sits in Class B shares, which carry three votes each on these proposals. Roughly 32 points of the 46% therefore came from other holders in about two weeks, which is fast. It also makes the remaining distance steeper than the arithmetic suggests.
The consents that come back first are the ones from holders who already agreed. The last few percentage points have to come from retail holders who do not open mail from a transfer agent. They also have to come from institutions that route everything through a proxy adviser.
Read the Footnote Before the Headline
The release carries a disclosure that deserves more attention than it will get. The 46% figure is “a preliminary tabulation of consents received by the Garg Group.” No independent inspector has verified it, and it can still change, including through revocations, until the consents are formally delivered.
None of that makes the number wrong. It does mean the number is self-reported by the side that benefits from it being high, counted by that side, and revocable. Consents can be withdrawn at any point before delivery, which is precisely why incumbent boards run revocation campaigns.
The consent solicitation also comes with a precedent. In August, Garg said he had support from a majority of Better’s voting power. His amended SEC filing later acknowledged that the consents delivered on August 17 did not represent a majority. He attributed the shortfall to an administrative error by Better’s in-house counsel. The Better consent solicitation will produce an audited figure eventually, and this is not that figure.
Garg Is Bidding to Reshape the Board He Sits On
This is not a conventional consent solicitation by an outside fund. Garg founded Better.com, ran it through its SPAC listing and its aftermath, and still sits on its board. As a director and a 13.7% holder, he is now pushing to reconstitute the board around him. The company says he wants his old job back.
His record is what the campaign runs on. His materials describe Better.com as an AI mortgage platform that has provided more than $110 billion in home financing. They say it raised more than $1.75 billion in equity from backers including SoftBank, L Catterton, Kleiner Perkins, Goldman Sachs, Ally Bank, American Express and Citi. Before Better, Garg co-founded MyRichUncle, an early online student lender, and ran 1/0 Capital, whose seed investments included Ramp and Creditas.
How the Fight Has Gone So Far
The company has contested the consent solicitation at every stage. Better sued Garg after his August claim fell short and sought a temporary restraining order to stop the solicitation. Judge Margaret Garnett of the Southern District of New York denied that motion, finding the company had not shown irreparable harm.
The proxy advisers have split. ISS, the largest, recommended that shareholders oppose the consent solicitation, according to Better. Egan-Jones has backed the consent solicitation. Egan-Jones is a legitimate adviser with a smaller institutional following than ISS or Glass Lewis, and its recommendation moves fewer shares. With ISS on the other side, institutions that follow an adviser are the hardest consents for Garg to win.
Better’s special committee, which excludes Garg, is running a revocation campaign on a white card. Its latest statement urged him to abandon the effort and said he has shown little support from public shareholders beyond a few longtime allies. Garg, for his part, has accused the company of not being fully candid with the court.
What the Better Consent Solicitation Can and Cannot Achieve
The release states one important limitation clearly rather than burying it. Removing five directors does not install Gordon, Heidecorn and Sarracino. The three have expressed willingness to serve, but no agreement has been reached with them. Their appointment would need approval from a majority of the board at that time.
So a successful consent solicitation produces a smaller board, not a new one. Reconstitution is a second step that depends on the directors who survive the first. Garg himself sits on the board and is not among the five targets. He would be one of those survivors, voting on his own nominees. Shareholders weighing the green card should still understand which of the two steps they are voting for.
What to Watch
Three things will settle this. First, whether the Garg Group announces crossing 50% of outstanding voting power, and whether that comes with independent verification rather than another preliminary tabulation. After August, that distinction matters more here than usual.
Second, whether the revocation campaign dents the tally. Better has been soliciting revocations since August, before the 46% claim. Its existence therefore says nothing new about how the incumbents read the figure. Movement in the number from here will.
Third, what happens around October 2. That date is a target the soliciting party set for itself, and it has already moved at least once, from September 18. The binding constraint is Delaware law. A consent solicitation there succeeds only if valid consents reach the company within 60 days of the earliest-dated consent it receives.
Fintechbits covers fintech governance, mortgage technology and capital markets. Nothing here constitutes financial or investment advice. All analysis represents the editorial views of Fintechbits.