5 mins read
Helcim Series C funding closed at $53 million CAD in August, led by BDC Capital’s Growth Venture Fund. The Calgary payments company builds for small and mid-sized merchants, and the round lifts its valuation to $250 million CAD from $97 million CAD at the 2024 Series B. Total equity raised since the 2022 Series A now stands at $100 million CAD.
What the Helcim Series C Numbers Really Show
The numbers behind the raise are the part worth reading closely. Helcim says it crossed $150 million CAD in annual revenue this year, grew to 200 employees, now serves more than 22,000 active merchants across Canada and the U.S., and is on pace to process close to $10 billion CAD in annual payment volume.
Here the arithmetic deserves a second look. The valuation stepped up roughly 2.6x from the last round, which is healthy, but a step-up is not a revenue multiple. Set the $250 million valuation against $150 million in revenue and the company priced at under 1.7x. That is a strikingly low number for a payments business growing this fast.
The explanation almost certainly sits in how the revenue figure is built. Processors that report gross revenue include the interchange and network fees passed straight through to card issuers, so the portion the company keeps is a fraction of the headline. Note too that Helcim’s own announcement calls the figure annual revenue, while the press release and much of the coverage call it ARR. Whatever the Helcim Series C investors underwrote, it was not a 1.7x business at face value, and the step-up is the more honest signal of how they scored the growth.
Fintechbits analysis
Why the Helcim Series C Investor List Matters More
The more telling detail in the Helcim Series C is who showed up. Curql, a fintech investment collective backed by more than 160 North American credit unions, joined the Helcim Series C alongside new investor Gold House Ventures and existing backers including Headline, Aquiline, Information Venture Partners and Vesey Ventures. Curql does not write checks for novelty. Its whole reason for existing is finding vendors that credit unions can plug into to compete with bigger banks.
President and CEO Nick Evens said Helcim’s payment hub is the best his fund has seen, and tied that to a blunt argument about deposits: credit unions that fail to upgrade what they offer small business members will struggle to stay relevant in their own communities. Coming from a fund that has made more than 50 fintech investments on behalf of its members, that is a procurement signal rather than a venture one.
The Helcim Series C Bet on a Bank Retreat
That matters because of what Helcim and its investors say is happening on the other side of the market. Banks have been stepping back from small business merchant services, which leaves smaller institutions without a modern option to offer their business customers. Helcim built its payments infrastructure in-house rather than reselling a third party’s processing stack. That decision is what lets it price on volume-based interchange plus rather than the flat rates that often run 2.9% or higher. So the Helcim Series C is meant to fund both halves of the response, selling directly to merchants and partnering with the regional banks and credit unions now shopping for a replacement.
The clearest evidence the bet is landing arrived in January. Helcim released a browser-based Payment Extension that lets merchants self-integrate its processing into the software they already run, instead of accepting whichever processor their platform bundles in. It launched supporting more than 20 software platforms, with a stated target of over 100 by year end. BDC partner Jack Fraser singled that tool out as the kind of innovation his fund is backing, which suggests it featured in the underwriting and not just the press release.
What the Helcim Series C Has to Prove Upmarket
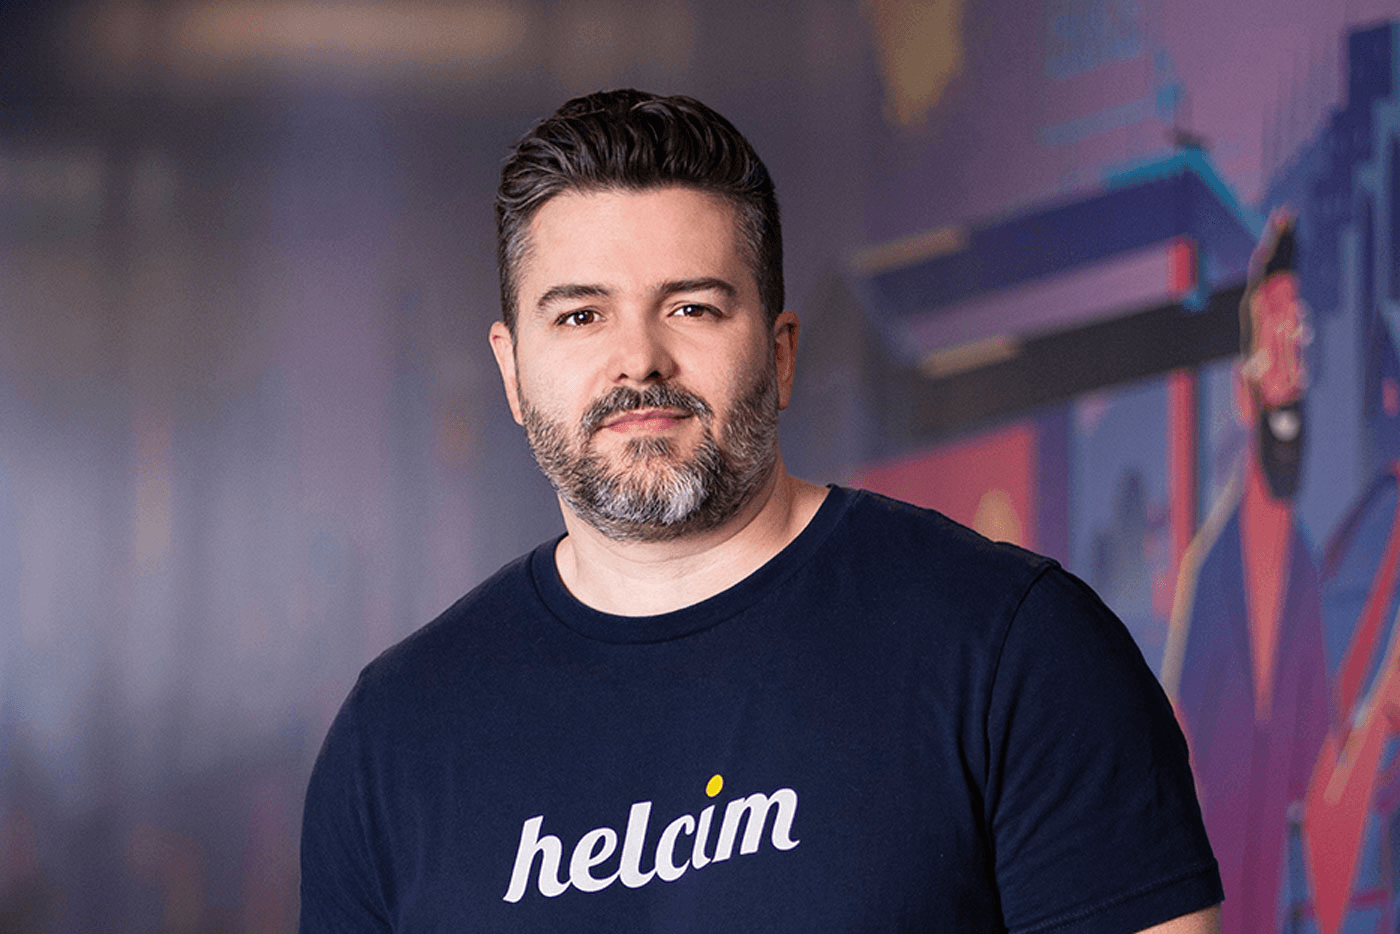
None of this makes Helcim a lock to win the space. Payments is littered with companies that found good product-market fit at small retailers and then struggled to move upmarket, into the segment where Stripe, Adyen and Square already hold entrenched relationships. Founder and CEO Nic Beique says the mid-market is exactly where this capital is going. So that is the part to watch, rather than the Helcim Series C headline itself.
Transparent, volume-based pricing is a fine pitch to a five-person retailer. Whether it wins a 200-person regional chain away from an incumbent processor is a different question entirely. Mid-market buyers weigh switching costs, integration depth and account management in ways a sole proprietor never does, and those are the areas where entrenched challengers have spent a decade building moats.
The credit union channel still gives Helcim a distribution advantage most challengers lack. More than 160 institutions with existing small business relationships is a far warmer start than a cold sales motion, and it is the one asset in this round that competitors cannot simply outspend. Converting that advantage into mid-market wins over the next year is the number that will tell the story, and it is the measure the Helcim Series C will ultimately be judged on.
Fintechbits covers payments infrastructure, small business banking and fintech funding. Nothing here constitutes financial or investment advice. All analysis represents the editorial views of Fintechbits.