7 mins read
Author: Nuwan Liyanage, Senior Manager – Corporate Banking, DFCC Bank PLC
Emerging markets fintech loves a headline number. Mobile money moved more than $2 trillion in 2025, and registered accounts reached 2.3 billion. So investors read that as a land grab. Operators read it differently. In Lagos, Dakar, Jakarta and Sao Paulo, the companies that win rarely sell a slicker app. Instead, they sell cash access, liquidity and trust. That gap explains why so many imported playbooks stall within a year of launch. Yet the failures are rarely about ambition or capital. Rather, they follow from assumptions that quietly stop holding once the plane lands. Here are the emerging markets fintech assumptions that travel badly, and what regional operators do instead.
Cash is the product in emerging markets fintech, not the enemy
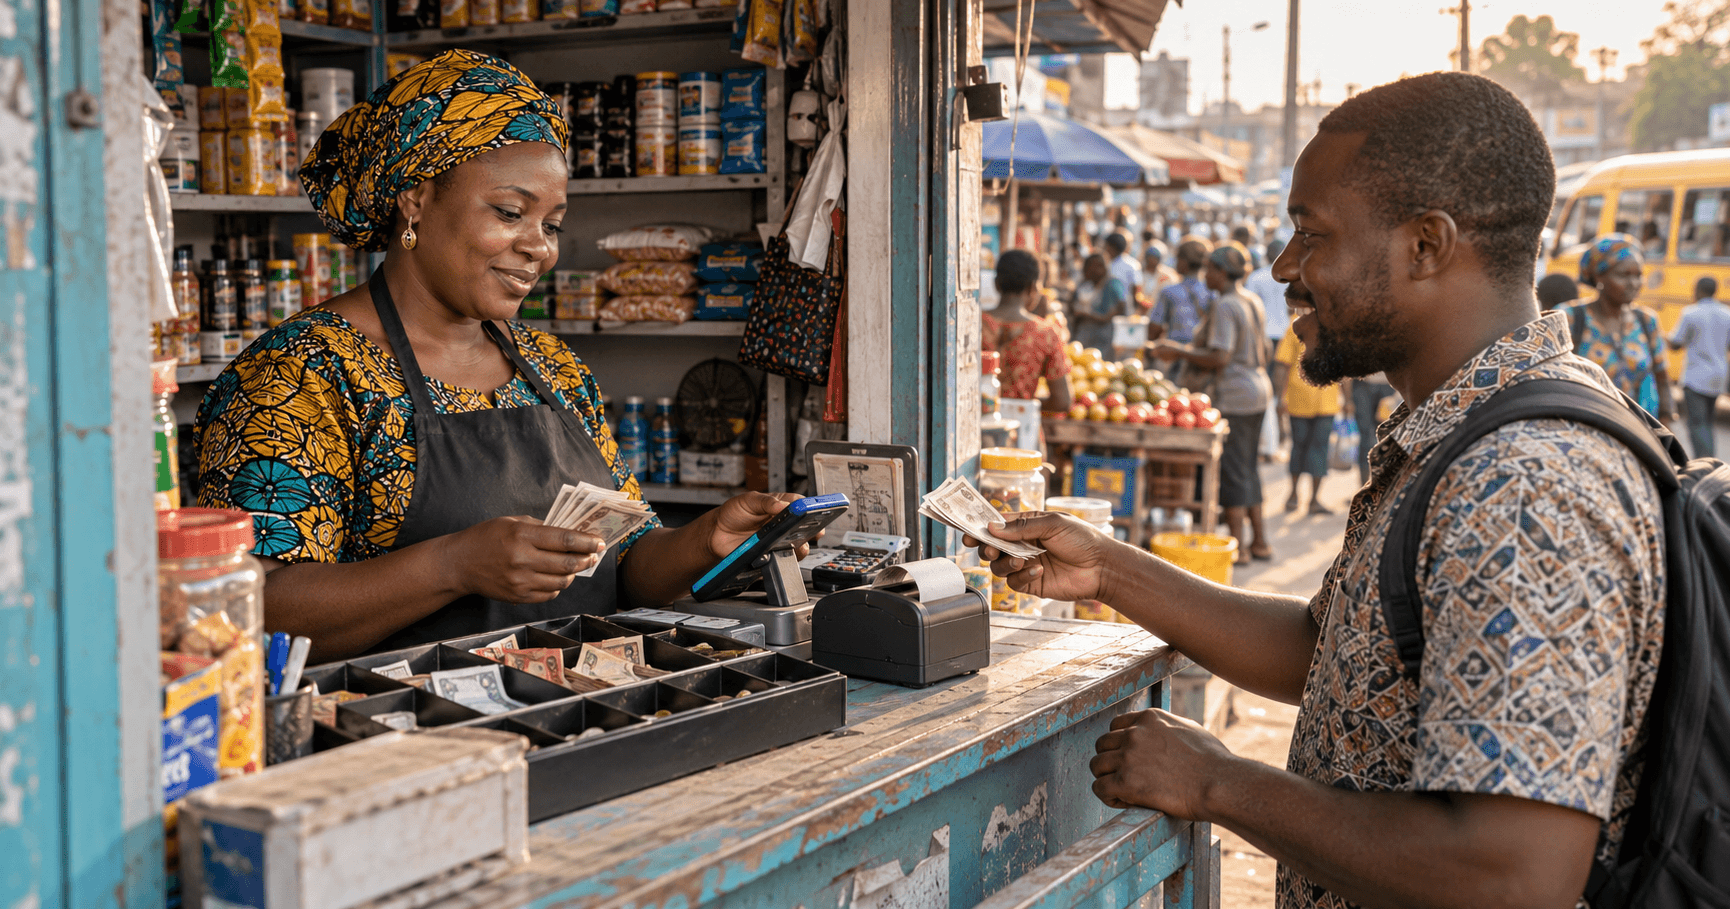
Imported decks treat cash as a problem to delete. Instead, operators treat it as inventory to manage. M-PESA runs on roughly 600,000 agents across its eight African markets, of which Safaricom reported close to 299,000 inside Kenya in its 2025 financial year. Counting every provider, the Central Bank of Kenya recorded 507,383 active mobile money agents in February 2026, up 28.5% in a year. Similarly, Nigeria counts close to two million banking agents. Those people are the network’s ATMs, branches and onboarding desks all at once.
The economics are physical, not digital. In practice, an agent must hold cash and electronic float at the same time. When either runs dry, the customer walks to the kiosk next door. Rebalancing liquidity therefore becomes the daily operating job, well ahead of user acquisition. Product teams that never model float will misprice the entire emerging markets fintech business.
Emerging markets fintech regulators now treat agents as infrastructure
Nigeria gives the sharpest example. On 6 October 2025, the Central Bank of Nigeria issued new agent banking guidelines. Now agents must be exclusive to one principal. Also, devices must be geo-fenced to a registered location. Each agent faces a cumulative daily cash-out cap of 1.2 million naira, and customers face a 100,000 naira daily limit. The exclusivity and location rules took effect from 1 April 2026.
Consequently, asset-light distribution stops working as an emerging markets fintech strategy. An agent becomes a contracted, monitored and capital-hungry channel. Besides that, super agents can no longer serve customers directly, terminals must be registered through aggregators, and principals face fines reaching ten million naira. Entrants who budgeted for marketing rather than compliance discover that difference late, and usually expensively.
The app is not the interface in emerging markets fintech
Product teams from richer markets assume a smartphone, cheap data and a confident user. GSMA counts a usage gap of 3.1 billion people who live under mobile broadband coverage yet stay offline. Roughly two thirds of them own no internet-enabled device at all. An entry-level handset costs 16% of average monthly income across low and middle income countries. For the poorest fifth, it costs 48%. In sub-Saharan Africa, that figure reaches 87%.
Emerging markets fintech interfaces therefore stay plural. So USSD menus, agent-assisted transactions and printed QR codes still carry enormous volume. In the Philippines, the central bank’s 2025 Consumer Finance and Inclusion Survey found half of adults hold a formal account, down from 56% in 2021. Notably, e-money accounts at 36% now outrank bank accounts at 23%. A separate survey for the central bank widened that gap further in early 2026, with 43% holding e-money against 21% holding a bank account.
Pricing travels worst of all in emerging markets fintech
Card-style pricing assumes large tickets and merchant interchange. By contrast, emerging market tickets are small, frequent and fiercely compared. Wave attacked exactly that gap in Senegal and Cote d’Ivoire, and now operates across six West and East African markets. Its public promise stays blunt: send for 1%, then deposit, withdraw and pay bills for free.
However, that model punishes anyone carrying an imported cost structure. Percentage ladders and withdrawal charges look sensible in a spreadsheet. Yet beside a flat 1%, they look predatory. Pricing is an emerging markets fintech product decision, not a finance department afterthought.
Emerging markets fintech credit models break at the border
Underwriting assumptions fail even faster than pricing does. Imported credit models expect bureau files, payslips and stable addresses. Here, most customers carry none of the three. Their income arrives daily, in cash, from several small activities at once.
Operators therefore underwrite from behaviour they can already see. Wallet turnover, airtime top-ups, agent deposit patterns and merchant settlement history become the credit file. GSMA notes that credit is now the most widely offered service sitting alongside core mobile money.
Yet the risk hides somewhere unfamiliar. Because loan books sit in local currency, they face high inflation and sudden devaluation. Nigeria and Egypt both delivered that lesson recently. A model tuned on stable currencies will understate loss severity. Ignore that, and the book grows straight into trouble.
Local rails already won in emerging markets fintech
Many entrants still plan proprietary rails. Meanwhile, public infrastructure moved first and moved fast. Pix processed 79.8 billion transactions worth 35.36 trillion reais in 2025, a third more than the year before, and now reaches roughly 93% of Brazilian adults. Indonesia’s QRIS reported 65.77 million users and 44.86 million merchants by June 2026. Almost 97% of those merchants are micro, small or medium enterprises.
Because acceptance is already cheap and universal, a closed wallet has little left to sell in emerging markets fintech. Smart operators plug into the national rail and compete above it. They win on credit, savings, insurance, payroll and merchant tools instead.
Distribution is a relationship in emerging markets fintech, not a funnel
Trust here is local and personal. People hand cash to an agent they know by name, often in the same street market every week. GCash grew into the dominant Philippine wallet by building around neighbourhood retail. Similarly, Nigerian agents work from kiosks, pharmacies and shopfronts rather than branches.
Growth therefore hangs on agent economics. Commission splits, float credit and terminal costs decide whether an agent recommends you or a rival. Nigeria’s new exclusivity rule makes that decision sticky, which sharply raises the cost of arriving late.
Then there is agent churn, which carries a hidden bill. Every departing agent takes a customer list, a location and a reputation with them. And rebuilding that presence costs far more than a paid install ever does.
What the big emerging markets fintech numbers hide
Headline totals flatter the whole industry. GSMA reports 2.3 billion registered mobile money accounts, yet only 593 million were active monthly during 2025. Roughly three quarters of accounts sit idle in any given month.
In emerging markets fintech, the real contest is usage rather than signups. Operators chase repeatable behaviour: wages, remittances, school fees, transport and merchant payments. Vanity metrics cross borders easily. Habits do not.
Emerging markets fintech takeaways
Cash-in and cash-out remain the core service, and agent liquidity rather than app design decides retention. Regulators now treat agent networks as infrastructure, with Nigeria imposing exclusivity, geo-fencing and hard caps. Handset and data costs keep USSD, QR and assisted channels relevant for billions of people. Meanwhile flat, transparent pricing beats imported percentage ladders in low-ticket markets. Public rails such as Pix and QRIS have already won acceptance, so build above them rather than against them. Credit files start from wallet behaviour, and currency risk sits inside the loan book. Above all, active usage rather than registered accounts is the only metric worth defending.
Fintechbits covers emerging markets fintech, mobile money, and payments infrastructure. Nothing here constitutes financial or investment advice. All analysis represents the editorial views of Fintechbits.