5 mins read
Guest column by Pratik Singh Raguwanshi of LiveHelpIndia.
Emerging market fintech expansion often starts with a simple idea: take a product that worked in the West and replicate it in high-growth regions. Companies assume mobile-first infrastructure is an easy gateway to scale across Africa, Southeast Asia or Latin America.
That assumption ignores the hidden costs of fragmented financial systems. For emerging market fintech, those frictions add up to a latency tax. It erodes operating margins and cuts customer lifetime value, and it rarely shows up in the original business case.
The Operational Weight of Agent Networks
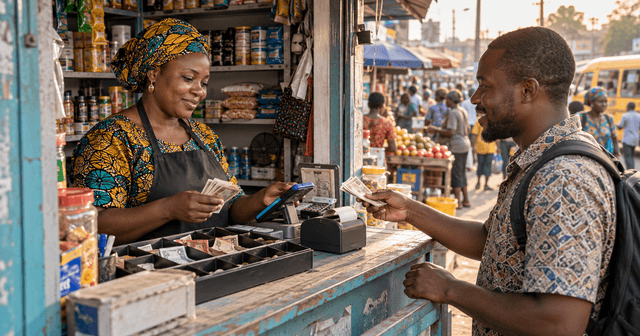
Digital-only emerging market fintech strategies struggle where cash remains the main way people pay. Scaling there usually requires a physical presence through agent networks, and managing those networks is a heavy administrative job that western platforms often underestimate. You have to handle local logistics, consistent training and constant fraud monitoring.
Kenya shows the scale involved. The Central Bank of Kenya counted about 572,000 active mobile money agents in June 2026, according to TechTrends Kenya. The same report found the value of deposits made through agents fell 10.1% in 2025, as more activity moved to phones. Agents still matter, but the mix is shifting.
Agents often work in areas with weak connectivity and poor transport. Teams must manage liquidity and oversight where standard automation struggles, and reconciliation gaps between digital ledgers and physical cash are common. Effective business process outsourcing can ease that load by handling agent oversight and back-office reconciliation.
Fraud also behaves differently than in card-based western systems. Static, algorithm-only detection is not enough. Where credit bureaus are thin and digital ID coverage is uneven, human verification and local presence remain part of how trust is built.
Emerging Market Fintech Support Must Fit Every User
Clean, minimal interfaces are not always the right choice. Emerging market fintech products have to work for a wide range of digital literacy and for low-end or shared devices. Support must handle users with intermittent network access, and generic chatbot flows can push them away.
New users often value stability and a human point of contact over speed. A mobile money service without clear, reachable support will see high churn. Make every fee visible, especially on cross-border transfers, where exchange rates and partner fees can stack up out of view. Hidden costs are one of the fastest ways for an emerging market fintech brand to lose trust it took months to build.
Good service usually blends SMS, voice and in-app messaging, adapted to local languages and expectations. Scaling those layers takes real expertise in customer experience management, so that each touchpoint builds trust rather than erodes it.
Local Rails Are Often Faster, Not Slower
Interoperability remains a major hurdle for emerging market fintech teams. Teams may juggle dozens of payment rails, local wallets and national clearing systems, and forcing them into one rigid architecture creates technical debt. Modular middleware that translates between local protocols and your core ledger is the better approach. It also stops a local outage from taking down the whole platform.
The latency problem is rarely the rails themselves, though. Many emerging markets now run some of the fastest payment systems in the world. India’s UPI processed a record 24.51 billion transactions in August 2026, according to Business Standard, citing NPCI. Brazil’s Pix handled a record 318 million transactions on September 4, 2026, as reported by The Rio Times.
So the tax usually comes from the gaps between systems: older bank links, cash-out points and cross-border legs. Build for asynchronous confirmation where those gaps exist, or your platform will report failures that are only delays. Data rules add another layer. Localization requirements vary by country, so compliance workflows should adjust to the jurisdiction of each transaction.
Build for the Informal Economy
Western product design assumes high financial literacy and standard identity checks. Many emerging market fintech customers instead rely on informal credit, social collateral and community lending. A product built strictly on western banking logic will lose the customers it was meant to serve.
Small merchants and street vendors run on different cycles than formal companies. Features should offer flexible settlement times and access to small amounts of working capital. Standard KYC rules can shut out the informal workforce, so where regulators allow it, build verification paths that use other data, such as utility payment history.
For an emerging market fintech, ignoring local context leads to high acquisition costs that never turn into steady revenue. You end up paying for customers who cannot use the product reliably. Lasting growth comes from fitting into the daily routines of local agents and users.
Partnerships and the Right Metrics
Emerging market fintech growth takes a large investment in people. Building that capacity in-house is often slower and more expensive than working with specialist operations partners, who bring local knowledge and workforce capacity. That frees your engineers to focus on the product.
Speed matters. If localizing your stack takes eighteen months, competitors may already hold the market. Partners can handle the people-heavy parts of the model while your team stays focused on the product.
Measure progress with local metrics. Look beyond churn to wallet share in specific corridors. Emerging market fintech succeeds when the service works as reliably in a rural village as in a capital city. Companies that treat local friction as part of the product, not something to route around, build advantages that are hard to copy.
For related coverage, see how Alipay+ plugged into the Argentina national QR network and how Revolut added a Colombia banking license.
FintechBits covers payments, banking and fintech developments for readers in the US and UK. This article is for information only and is not financial advice. Views expressed in guest columns are those of the author.