6 mins read
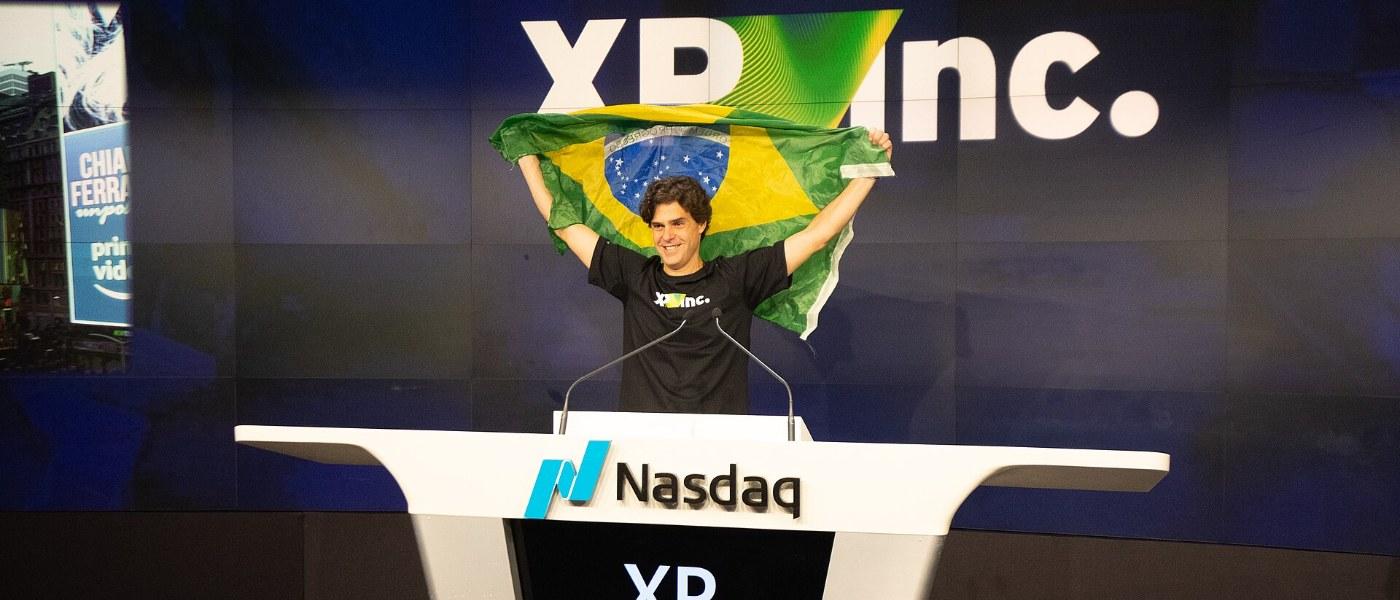
XP Inc, the Brazilian investment platform listed on Nasdaq, reported net income of R$1,382 million for the third quarter of 2026 on 16 November 2026, up 4% from a year earlier on gross revenue of R$5,339 million. Fintechbits checked XP’s 17 August 2026 second-quarter filing with the SEC, which said the company was comfortable taking its BIS ratio to a target range of 16% to 19% toward the end of 2026 through capital distributions, so the 20.3% ratio reported for the third quarter of 2026 still sits 1.3 points above the top of that range.
The XP Inc Q3 2026 release also announced R$1.3 billion of new dividends and a R$1.5 billion buyback, while quarterly net inflow fell to R$22 billion from R$29 billion in the third quarter of 2025.
XP Inc Q3 2026 Results: Profit Up 4%, Assets Up 11%
In the XP Inc Q3 2026 figures, client assets reached R$1,574 billion, up 11% on the year and 3% on the second quarter of 2026. XP credits the annual gain to R$95 billion of net inflow plus R$54 billion in market gains. Active clients numbered 4.8 million, up 1%, so growth came from larger balances per client and not from a bigger customer base.
Net revenue rose 9% to R$5,139 million and earnings before tax rose 13% to R$1,580 million, but net income grew only 4%. The gap reflects tax expense of R$199 million against R$74 million a year earlier. Diluted earnings per share climbed 9% to R$2.69, which is the buyback at work, because a smaller share count lets profit per share outrun profit. Return on average equity was 21.7% and return on tangible equity 26.2%. XP blamed the softer returns on “capital generation without a corresponding distribution throughout the quarter”, an admission that the balance sheet is carrying more equity than the business needs.
Where XP Inc Q3 2026 Revenue Grew and Where It Did Not
Retail revenue was R$4,127 million, up 11%, with equities at R$1,206 million and fixed income at R$903 million, down 2%. Retail net inflow was R$17.5 billion. The annualised retail take rate was 1.25%, up 1 basis point on the year, so XP is earning slightly more per real of client assets and not discounting to win deposits.
The wholesale bank earned R$1,212 million, up 13%. Corporate revenue jumped 55% to R$631 million, while issuer services fell 40% to R$194 million. The expanded loan book grew 28% to R$86.2 billion, and expected credit losses were R$108 million, up 20%. Risk-weighted assets rose 23% to R$132.2 billion, which is the real reason the capital ratio is not falling faster: XP is using capital on lending as well as returning it.
Costs ran ahead of income. Selling, general and administrative expenses were R$1,873 million, up 12% on the year against net revenue growth of 9%. XP Inc Q3 2026 lending growth offers a regional yardstick. Fintechbits covered Mercado Pago’s third-quarter 2026 results, where the credit portfolio grew 62% in dollars to $17.9 billion, a faster build than XP’s 28%, although the two figures sit in different currencies and different business models.
Why the Payout Matters More Than the 4% Profit Growth
The argument is simple. Operating momentum at XP slowed in XP Inc Q3 2026, with net inflow at R$22 billion against R$28 billion in the second quarter and R$29 billion a year earlier, and costs grew faster than revenue. What held the equity story together was capital return: R$1.3 billion of dividends plus R$1.5 billion of buybacks adds up to R$2.8 billion, and XP will also cancel about 11.7 million treasury shares, roughly 2.3% of shares outstanding.
XP Inc Q3 2026 shows a sensible response to an overcapitalised balance sheet, but it is not enough on the evidence. The ratio XP said it wanted below 19% was 20.3% after the quarter, only 6 basis points higher than in the second quarter. A R$2.8 billion distribution has to be paid before it lowers anything, and loan growth is consuming capital in parallel.
After XP Inc Q3 2026, the lasting question for a Brazilian wealth platform with 4.8 million active clients is whether corporate banking and credit can replace slower inflow as the earnings engine. A 55% jump in corporate revenue and a 28% larger loan book suggest management is trying exactly that. Digital rivals such as Nu Holdings, which said on 30 September 2026 that it was not pursuing a transaction with Monzo, are the obvious alternatives for Brazilian savers, so slower inflow is the number to take seriously.
Frequently asked questions
How much did XP Inc earn in Q3 2026?
XP Inc Q3 2026 net income was R$1,382 million, up 4% on the third quarter of 2025. Diluted earnings per share were R$2.69, up 9%.
What capital return did XP Inc announce with its Q3 2026 results?
XP Inc announced R$1.3 billion of new dividends, to be paid in 2026, and a new share buyback programme of R$1.5 billion. It also plans to cancel about 11.7 million treasury shares.
Is XP Inc still above its capital target after Q3 2026?
Yes. XP Inc Q3 2026 data show a BIS ratio of 20.3%, against a target range of 16% to 19% set out in its second-quarter filing. The announced payout is the lever XP named for closing that gap.
What to Watch Next
The fourth-quarter 2026 results, the next after XP Inc Q3 2026, will show whether the R$1.3 billion of dividends, which XP said would be paid in 2026, pulls the BIS ratio inside 16% to 19%. Watch also whether net inflow returns toward the R$28 billion of the second quarter, whether selling, general and administrative costs stop outgrowing revenue, and whether issuer services revenue keeps falling after a 40% drop.