5 mins read
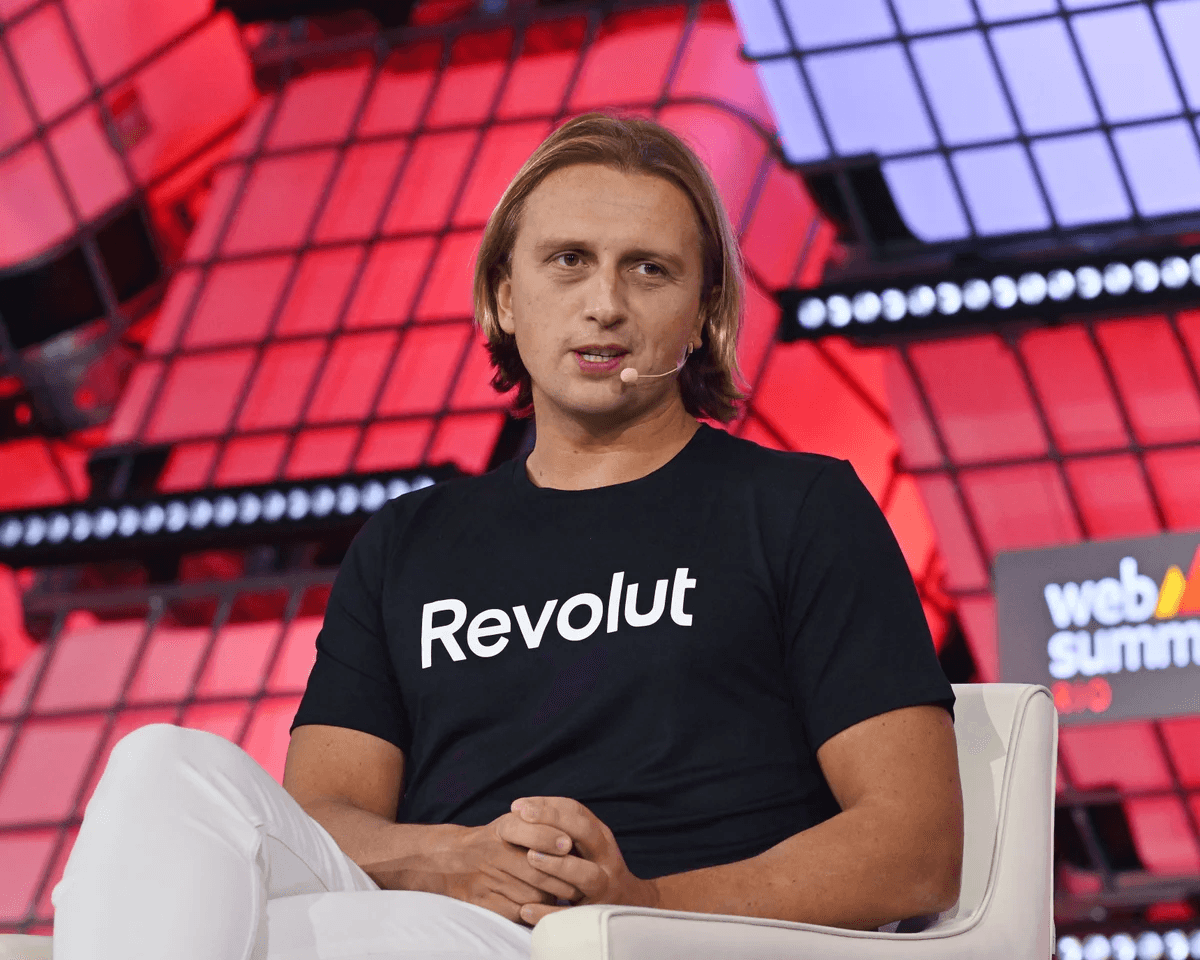
Revolut Bank Australia launched on July 21 after APRA granted the company an independent Authorised Deposit-taking Institution license. Notably, Revolut says the approval makes it the first global fintech to secure a full unrestricted ADI. In practice, the entity becomes its first banking operation anywhere in the Asia Pacific region.
More than one million Australian retail customers transfer across automatically, along with thousands of business customers. No action is required from any of them. Meanwhile, balances carry protection up to A$250,000 under the Financial Claims Scheme. Revolut Bank Australia therefore opens with scale most new banks never reach. Alongside the license, Revolut committed close to A$400 million to the Australian market over five years, covering product development, operations and local headcount.
Revolut Bank Australia Cleared a Strict Regulator
Take this one seriously, and not because the press office says so. Here APRA ranks among the tougher prudential regulators in the developed world, and it does not issue unrestricted ADI licenses as a courtesy. A restricted pathway would have capped deposits while the applicant built risk and compliance infrastructure under closer supervision.
Instead, Revolut Bank Australia went straight to unrestricted status. That means the regulator judged the company capable of running a full retail bank now rather than at some later phase. Notably, the process took roughly three years, since Revolut first applied in 2023. Baxby says the company entered Australia in 2020 with three people.
Local history sharpens the point. Australia produced a cohort of digital challengers including Judo Bank, Volt, Xinja and 86400, and their outcomes varied widely. So a license alone has never guaranteed survival in this market. What separates Revolut Bank Australia is that it arrives with a customer base already built rather than hunting for one after authorisation.
The $400 Million Behind Revolut Bank Australia
The Revolut Bank Australia commitment figure matters more than the customer count. Because vague pledges to invest in growth cost nothing, a specific number carries weight. A five year, currency denominated number attached to one market is a balance sheet decision, and it signals that Revolut expects Australia to generate profit rather than headlines.
That reading holds up against the wider business. For scale, Revolut serves more than 75 million customers globally, and group revenue rose 46 percent to around $6 billion in its 2025 financial year. Against that base, A$400 million represents a deliberate allocation to a single mid sized market. Consequently, the number reads as conviction rather than a rounding error dressed as commitment.
Revolut Bank Australia Caps a Seven Month Charter Run
One correction is needed on the timeline, because it changes the story. Revolut did not begin full banking operations in Mexico in 2023. It started them in January 2026, after completing a beta phase, and that was its first bank outside European borders.
The UK full banking license followed in March 2026, closing a process that ran roughly four years. Revolut applied to the Office of the Comptroller of the Currency and the FDIC for a US national bank charter in the same month. It is also pursuing a French license and picked Paris as its western European headquarters in April.
So the pattern is not patient accumulation over many years. Mexico, the UK and now Revolut Bank Australia all landed inside seven months. Storonsky has explained why. Regulators in the US, Australia, New Zealand and Switzerland were largely waiting on the full UK license before advancing their own reviews. One approval unblocked a queue, and the rest followed quickly.
The strategic logic still stands, and it is the real story. Many neobanks operate indefinitely as e-money institutions, limited in what they can offer and how they fund a balance sheet. Charters like the Revolut Bank Australia license cost more and take longer. Yet they are the only route to savings, lending and the deposit funding that makes those products profitable.
What Revolut Bank Australia Has to Prove Next
Shipping is the test. Baxby points to savings and credit as next on the roadmap, and Revolut Bank Australia now has the license to deliver both. Without visible product launches on a stated timeline, the charter amounts to a costlier version of what the company already ran.
Watch the sequencing rather than the announcements. First, deposit gathering matters, because cheap funding is the entire economic argument for holding a charter. Then lending follows, and that is where an untested credit book carries genuine risk. In that market, competition is fierce, and the incumbent majors defend primary banking relationships hard.
The five year clock on that A$400 million provides a useful measuring stick. If savings and credit products arrive within the first year and deposits follow, the investment thesis works. If the money goes largely to compliance and headcount while the product suite stays close to what existed before, the license will have been the easy part.
For related reading, our analysis of Revolut wealth management covers the product expansion strategy behind this move. Our guide to challenger banking innovators maps the wider neobank field, while our piece on digital banking for smaller businesses covers the business customers moving across. Revolut published the launch announcement on its newsroom. Coverage also ran at Retail Banker International and PYMNTS.
Fintechbits covers digital banking, licensing and global fintech expansion. Nothing here constitutes financial or investment advice. All analysis represents the editorial views of Fintechbits.