3 mins read
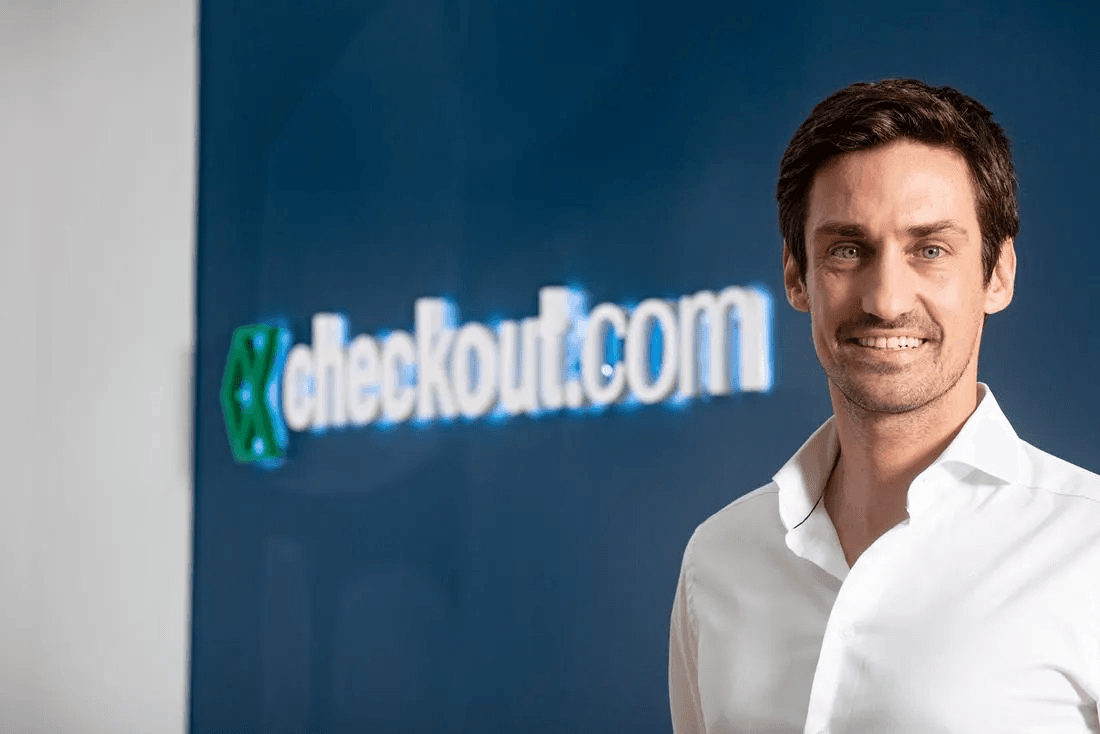
The Checkout.com MALPB charter is now live and processing volume. Granted by the Georgia Department of Banking and Finance, it gives the company direct access to Visa and Mastercard for its US enterprise merchants. That removes the third-party acquiring bank most processors route through.
Inside the Checkout.com MALPB charter launch
The Checkout.com MALPB charter timeline is tighter than multi-year suggests. Checkout.com applied in October 2025, won approval on 12 January 2026, and went live on 9 September. So application to operation took roughly eleven months.
Meanwhile Jordan Reynolds, who runs the entity as MALPB CEO and heads North American banking, called it “a defining step in our US journey.” He came from Elavon, SunTrust and PwC. Georgia’s banking commissioner Bo Fears framed the milestone around the preparation and governance the state’s framework demands.
Founder and CEO Guillaume Pousaz has put a date on the ambition. He compared the charter to Checkout.com’s 2012 UK acquiring licence, called the US the company’s fastest-growing region, and said he expects it to become the single biggest globally by the end of 2027.
Fintechbits analysis
Why the Checkout.com MALPB charter has a hiring clock
The continued hiring is not a signal of ambition. It is a licence condition.
Notably, approval requires employing no fewer than 50 people in Georgia devoted to merchant acquiring within one year of beginning operations. That clock started this month. So the nearest measurable test of the Checkout.com MALPB charter is a headcount figure due by September 2027.
What the Checkout.com MALPB charter does not change
Checkout.com is not the second major processor down this road. It is at least the third. Georgia created the MALPB in 2012, and it sat largely unused for over a decade before Fiserv began processing under it in April 2025 and Stripe won approval that July. Finaro held one earlier and never used it.
Besides, roughly 70% of US payment transactions already flow through companies with operations in Georgia. That is why the state calls itself Transaction Alley.
The restrictions run broader than the shorthand implies. A MALPB cannot conduct general banking, solicit or accept public deposits, sponsor ATMs, or issue payment cards. It is an acquiring licence, full stop.
One nuance on the fee argument. When Stripe took its charter, it said network membership was additive to existing processing and settlement activity rather than a replacement for its banking relationships. So cutting out a sponsor bank is less binary than it sounds, and the margin effect is likely gradual rather than dramatic.
What to watch next for the Checkout.com MALPB charter
The strategic signal is the interesting part. Large processors increasingly want to own pieces of banking infrastructure rather than lease them from partners who can change terms, get acquired, or develop their own regulatory problems. Rented infrastructure carries someone else’s risk.
Still, Reynolds also promised stronger performance, greater resilience and AI-powered payment optimisation. The release offers no detail on the last of those.
So watch whether Checkout.com names US enterprise merchants running live volume through the new setup. Above all, watch the Georgia headcount, because that is the one commitment with a published deadline attached.
Fintechbits covers payments infrastructure, bank charters, and merchant acquiring. Nothing here constitutes financial or investment advice. All analysis represents the editorial views of Fintechbits.