6 mins read
New rules in the US, UK and EU have turned stablecoins from a product experiment into a regulated business. Two industry voices explain what changed, from investor diligence to the balance sheet.
A year ago, most stablecoin plans started with the product. Teams picked a chain, found a partner bank and worked out compliance later. That order no longer works. Stablecoin regulation now decides who can issue, which banks will hold reserves and how a finance team records the coins.
So we asked industry leaders one question: how has new stablecoin regulation changed your product roadmap or your banking partnerships over the past year? We wanted first-hand experience over commentary. Two respondents answered. Below, we set their replies against the rules now coming into force.
A year of stablecoin regulation in three markets
The US moved first. The GENIUS Act became law in July 2025 and takes effect on 18 January 2027. On 21 October 2026, the OCC became the first federal banking agency to finalise a rule under the Act, setting reserve, redemption and custody standards. However, the wider CLARITY Act market structure bill failed a Senate vote in September.
Europe followed with a hard deadline under its own stablecoin regulation. MiCA’s transition period ended on 1 July 2026, and exchanges began removing coins without an EU licence. Coinbase now restricts USDT and PayPal’s PYUSD in the EEA. Meanwhile, the UK set its own timetable. The FCA published final rules in June, and its authorisation gateway opened on 30 September 2026 ahead of an October 2027 start.
Investors now test the banking model early
Our first respondent advises startups on fundraising. He sees stablecoin regulation shaping how investors judge a business before it launches.
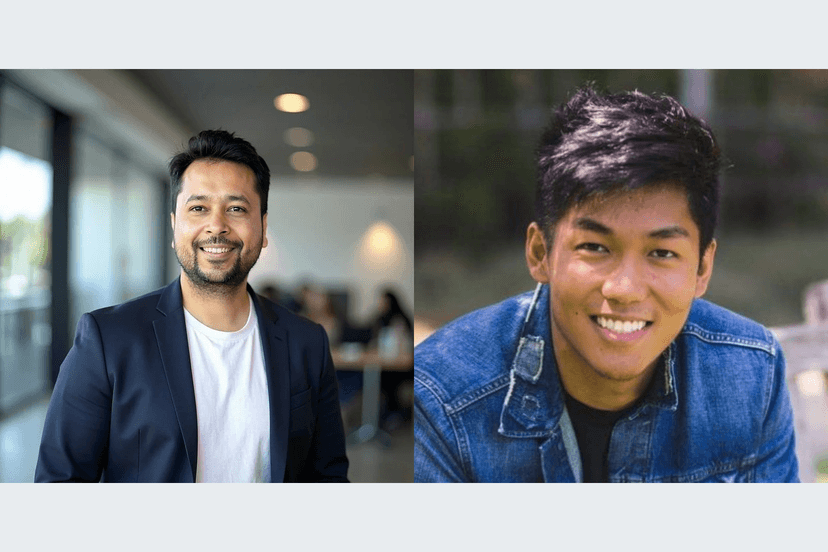
“From where I sit in capital advisory, regulation now shapes how investors read fintech business models. For stablecoin companies, the question is simple: can your banking relationships, reserves, redemption process and compliance controls hold up as you grow?
Founders shouldn’t treat compliance as a sign-off at the end of product work. Decide early which markets you’ll serve, what rules apply to your model, and whether your banking partners can support them. Those choices affect your launch date, your costs and whether the business works at all.”
Niclas Schlopsna, Managing Partner, spectup
His point matches what US stablecoin regulation now demands. The OCC rule requires one-to-one reserves and redemption within two business days. As a result, a stablecoin startup’s bank is now part of its regulated structure, not just a vendor. Still, his view comes from fundraising work, not from running a stablecoin business.
Banks and issuers are moving inside the perimeter
The bigger shift is structural, and stablecoin regulation is driving it. Rather than rent a partner bank, several issuers have applied for their own charters. Circle won final OCC approval for a national trust bank in July, and Ripple followed in October, as we reported on Ripple National Trust Bank. Stripe’s Bridge won conditional approval in February. Payments software firms are trying the same route, as our piece on the Modern Treasury trust bank application showed.
Banks are also building their own tokens. U.S. Bancorp piloted its own dollar stablecoin in a cross-border payment between group entities, according to its third-quarter results. In Europe, the Qivalis consortium has grown to 37 banks working on a euro stablecoin. BBVA dropped its own plan to join it. Therefore, stablecoin regulation is pulling issuance towards regulated balance sheets.
The accounting question finance teams face
Our second respondent, a chartered accountant, pointed to a change that reaches beyond issuers to any business accepting stablecoins.
“For businesses accepting stablecoins, the biggest change this year is in accounting. In August, FASB, the US accounting standard-setter, released a proposal setting out when qualifying stablecoins can count as cash equivalents. Comments are open until 19 November 2026.
The key point is that it depends on whether you can redeem the stablecoin directly with the issuer. We also know from the GENIUS Act that stablecoins not issued by an approved issuer won’t count as cash at all.
So decide which stablecoins you’ll accept, and which ones you can redeem with the issuer, before the first payment arrives. That makes life much easier for your finance team.”
Ankit Sarawagi, Curator, CFO Matrix
The details hold up, and they show how far stablecoin regulation now reaches into accounting. FASB’s proposed update, issued on 18 August 2026, clarifies how the existing definition of cash equivalents applies, rather than creating a new category. A holder needs its own right to redeem with the issuer. So a merchant that receives USDC through a processor, with no account at Circle, would likely not qualify. The GENIUS Act ban on cash treatment for coins from non-permitted issuers also only applies from 18 January 2027.
How stablecoin regulation reshapes roadmaps
Taken together, three changes stand out. First, jurisdiction now comes before product. A coin that is legal in the US may be delisted in the EU, so launch plans start with a licence map. Second, banking partners carry more weight under each new stablecoin regulation regime. Reserve custody, redemption speed and audit rights now sit in the regulated core of the business.
Third, distribution depends on compliance. Visa now settles in USDC with US banks such as Cross River and Lead Bank. Similarly, ACI Worldwide and Circle are bringing USDC to Colombia. In Europe, firms such as Flowdesk have taken their own payment licences to hold and move stablecoins.
What to watch next
Several dates will test stablecoin regulation in the months ahead. FASB’s comment period closes on 19 November 2026. The GENIUS Act and the OCC rule take effect on 18 January 2027, while Treasury’s limits on offering non-permitted coins follow in July 2028. In the UK, the FCA gateway closes on 28 February 2027, and the Bank of England expects to finalise its systemic stablecoin code by the end of 2026.
Above all, the lesson for founders and CFOs is consistent. Stablecoin regulation is no longer a final check before launch. It now shapes the product, the bank and the balance sheet from day one.
FintechBits covers payments, banking and fintech developments for readers in the US and UK. This article is for information only and is not financial, legal or investment advice. Views expressed are those of the FintechBits editorial team.