4 mins read
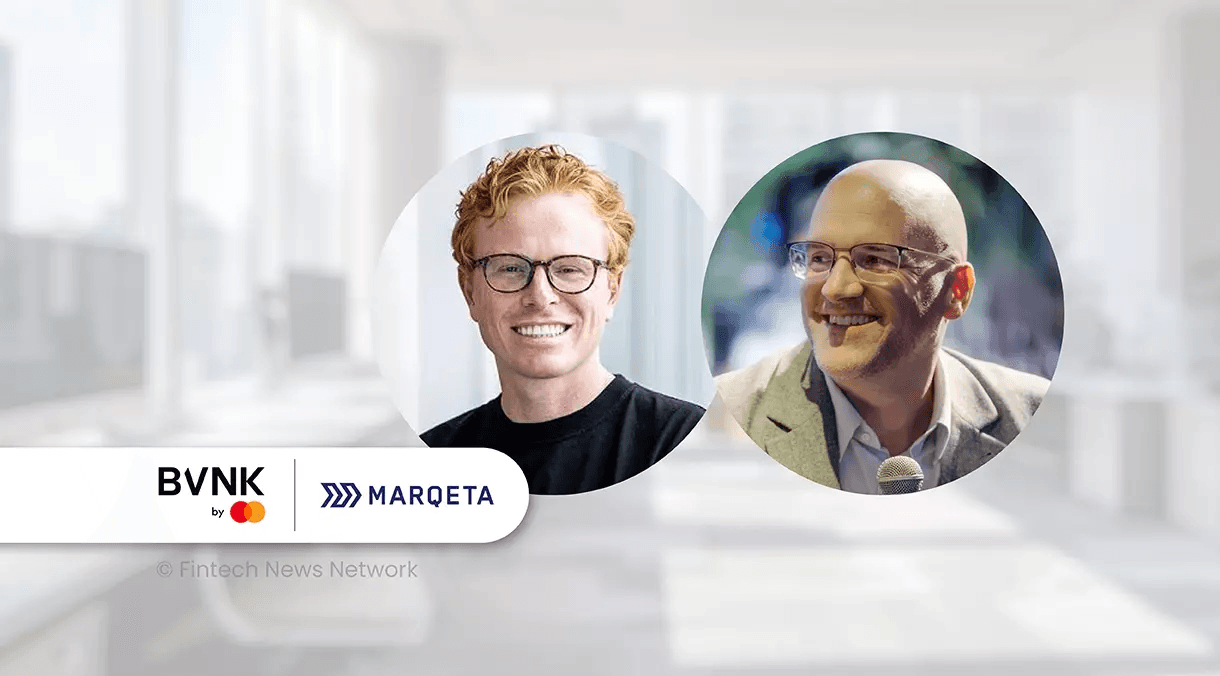
Marqeta BVNK stablecoin cards are the product of a partnership announced Wednesday. It lets Marqeta card-issuing customers embed stablecoin-backed cards into their programmes. Marqeta processed nearly $400 billion in payments volume during 2025. Meanwhile BVNK runs more than $39 billion in annualised stablecoin volume.
Inside the Marqeta BVNK stablecoin deal
The Marqeta BVNK stablecoin integration lets fintech and bank customers offer cards funded by stablecoins. So nobody has to build the settlement plumbing themselves. BVNK supplies the conversion and custody layer between crypto balances and card spend. In turn Marqeta handles issuance, acceptance and the bank and network relationships.
Meanwhile Anthony Peculic, Marqeta’s Chief Strategy Officer, framed it around merchants needing to change nothing. Chris Harmse, BVNK co-founder and Chief Business Officer, made the developer version of the same point.
Notably, the timing is not incidental. Mastercard agreed to buy BVNK for as much as $1.8 billion, including $300 million in contingent payments. That business became part of Mastercard in August 2026. Marqeta has long run card programmes on Mastercard rails. All three now back Open USD, a standard meant to make stablecoin payments interoperable across issuers and networks.
Fintechbits analysis
Why the Marqeta BVNK stablecoin tie-up is a Mastercard story
Mastercard bought the plumbing last month. Now Marqeta BVNK stablecoin rails sit inside its issuing stack. So this looks less like two independent companies discovering synergy. Instead it reads as a network seeding its own acquisition across a partner it already touches.
Open USD carries the word open in its name. Still, a standard whose founding members include the network that just bought the infrastructure is not neutral the way an internet protocol is. It is a Mastercard-aligned standard competing for mindshare against Visa’s stablecoin settlement work. Besides, the label does not change who benefits most if it wins.
One fact complicates that reading, though. Marqeta announced a parallel stablecoin partnership with Zero Hash in the same quarter, and Mastercard does not own Zero Hash. So Marqeta is running a multi-vendor stablecoin strategy rather than being steered into a single Mastercard-owned supplier. The positioning point stands. The exclusivity implication does not.
What the Marqeta BVNK stablecoin numbers do not prove
BVNK also released survey data alongside the announcement. Some 77% of polled crypto holders would open a stablecoin wallet through their bank or fintech app. It is a big number. However, BVNK has an obvious commercial interest in showing exactly that. A self-reported survey from the company selling the infrastructure is not independent research.
Marqeta’s own management is more candid than the release. At an investor conference this week, the company said stablecoins remain early. It described the near-term opportunity as card transacting with a stablecoin balance underneath, while spending still settles in fiat. That is a narrower claim than everyday digital dollar spending, and it is the honest version.
What to watch next for Marqeta BVNK stablecoin cards
None of this makes the deal hollow. Card-embedded stablecoin spend has been a genuine gap. Holders have had few easy ways to spend balances at a point of sale without converting through an exchange first.
Yet Marqeta already issues for Coinbase and Bitpanda, so the gap is narrower than it looks. Watch whether a Marqeta issuing customer ships a live Marqeta BVNK stablecoin product in the next two quarters. Citing the partnership as a roadmap item does not count. Above all, watch whether any of it settles in stablecoins rather than converting to fiat before the merchant ever sees it.
Fintechbits covers stablecoins, card issuing, and payments infrastructure. Nothing here constitutes financial or investment advice. All analysis represents the editorial views of Fintechbits.