6 mins read
Dateline: Cross River, acquisition, 20 October 2026
Cross River Bank, the New Jersey bank that provides embedded finance infrastructure to fintechs and brands, said on 20 October 2026 that its parent company, CRB Group, has agreed to acquire Accrue, a fintech that runs branded wallets, stored value and rewards for merchants. The release, Fintechbits notes, gives no purchase price, no expected closing date and no count of the merchants or wallet users Accrue brings, and the Cross River Accrue deal is the third Cross River announcement Fintechbits has covered since 4 October 2026. Read together, those announcements tell you more about where Cross River is heading than this one does on its own.
Deal: Agreement to acquire Accrue (Accrue Money, Inc.), subject to customary closing conditionsProduct: Branded wallet, stored value and incentive tracking for merchants
Amount: Not disclosed
What the Cross River Accrue deal includes
Accrue describes its product as loyalty at the payment layer. A merchant using it can give customers a wallet under the merchant’s own brand, with stored value, payments and rewards in one place. In the Cross River release, the bank says Accrue lets it offer partners a complete embedded finance stack. That stack already covers accounts, cards, payments, lending, digital assets and agentic commerce, and wallets and loyalty would sit on top.
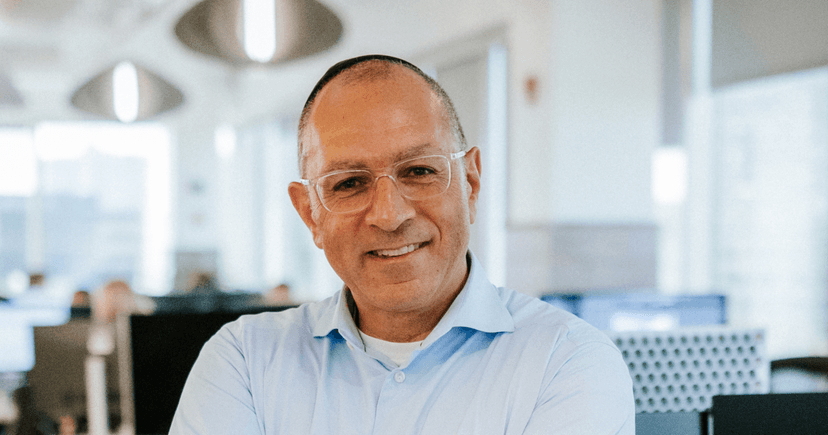
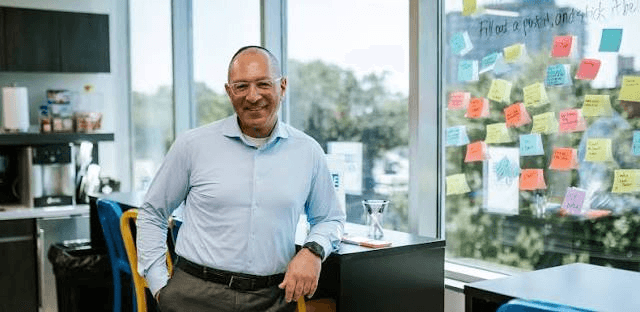
Accrue’s team will join Cross River. Michael Hershfield, Accrue’s founder and chief executive, will take a leadership role building out Cross River’s embedded finance products.
Gilles Gade, Cross River’s founder and chief executive, summed up the Cross River Accrue rationale in five words: “Payments and loyalty are becoming one.” He went further: “Every brand wants its own wallet, and with Accrue, all of our clients can now build one on our platform.”
A busy October for Cross River
The Cross River Accrue agreement follows two other Cross River announcements in quick succession. On 4 October 2026, Fintechbits covered the GoodLeap Home Card, which Cross River issues and backs with a $50 million revolving credit facility. On 16 October 2026, Fintechbits covered Cross River’s integration of Ripple’s RLUSD stablecoin into its core banking system.
Put side by side, these are the moves of a bank trying to sell brands a card, a credit line, stablecoin rails and, with Accrue, a wallet that holds customer balances. Cross River has long been one of the main US partner banks behind fintech lending and payments. It now wants partners to buy the whole product set from it, not just borrow its charter.
Where Accrue fits in embedded finance
Branded wallets are an old idea. Large retailers and restaurant chains have run stored value programmes for years, usually on their own technology or through specialist vendors. What Cross River is pitching is a version any of its partners can switch on through a single bank relationship.
Hershfield said: “I started Accrue with the belief that financial products would increasingly live inside the brands and experiences customers use every day.” For a brand, the appeal of a Cross River Accrue wallet is that customer balances and repeat visits stay inside its own app, instead of passing through a card network or someone else’s wallet.
Fintechbits analysis
Fintechbits analysis
Why the Cross River Accrue Deal Matters More for Banks Than Brands
We think the Cross River Accrue deal makes sense as a bolt-on, but the disclosure leaves out what anyone would need to value it.
Start with why it makes sense. Partner banks compete on how much they can offer fintechs without making them stitch together five vendors. A bank that holds the deposits, issues the card, settles in stablecoins and runs the brand’s wallet has a stronger hold on that relationship than one renting out its charter. Cross River is building that position one deal at a time.
Then look at what is missing. With no price, there is no way to tell whether Cross River is buying a real business or a team and some software. There is no Accrue merchant count, no wallet balance figure and no transaction volume. The release also does not explain how stored value balances will be held once Accrue is part of a bank, and both regulators and brands will want that answer. Balances held at an FDIC member bank are a different proposition from balances held by a fintech through a partner bank, and the announcement does not describe the structure.
For brands, the open question is demand. Gade says every brand wants its own wallet. Plenty of merchants have found that customers would rather pay with the card or wallet already on their phone. The Cross River Accrue bet only pays off if Cross River can show brands that a branded wallet brings in more spending and does not just add a step at checkout.
Frequently asked questions
What is Accrue and why is Cross River buying it?
Accrue is a fintech whose platform lets merchants offer branded wallets that combine stored value, payments and rewards. Cross River says the purchase completes its embedded finance stack, so partners can offer payments and loyalty together. Accrue’s team, including founder Michael Hershfield, will join Cross River.
Has the Cross River Accrue acquisition closed?
No closing was announced with the agreement on 20 October 2026. Cross River said the transaction is subject to customary closing conditions and gave no target date.
What does the Cross River Accrue release leave out?
Fintechbits notes that the release gives no purchase price, no closing date and no figures for Accrue’s merchants, users or wallet balances. It also does not explain how stored value will be held once Accrue sits inside a bank. Those details separate a strategic purchase from an acqui-hire.
What to Watch Next
The first named brand will be the real test. If Cross River announces a recognisable merchant running an Accrue wallet on its platform, with user or balance figures attached, the deal will look like a product expansion. If the next news is mostly about Hershfield’s wider embedded finance role, Accrue will start to look more like a talent acquisition.
Why this matters
Fintechbits notes that the Cross River Accrue release gives no price, closing date or Accrue user numbers, and that it is the third Cross River announcement Fintechbits has covered since 4 October 2026, after the GoodLeap Home Card and the RLUSD integration. Cross River is assembling wallets, cards, credit and stablecoin rails for brands under one charter. The open questions are whether merchants want branded wallets at scale and how stored value balances will be held inside the bank.
Primary sources
businesswire.com | PRESS RELEASE | https://www.businesswire.com/news/home/20261020941746/en/Cross-River-to-Acquire-Accrue-Expanding-Financial-Infrastructure-with-Integrated-Wallet-Capabilities
crossriver.com | COMPANY WEBSITE | https://www.crossriver.com