6 mins read
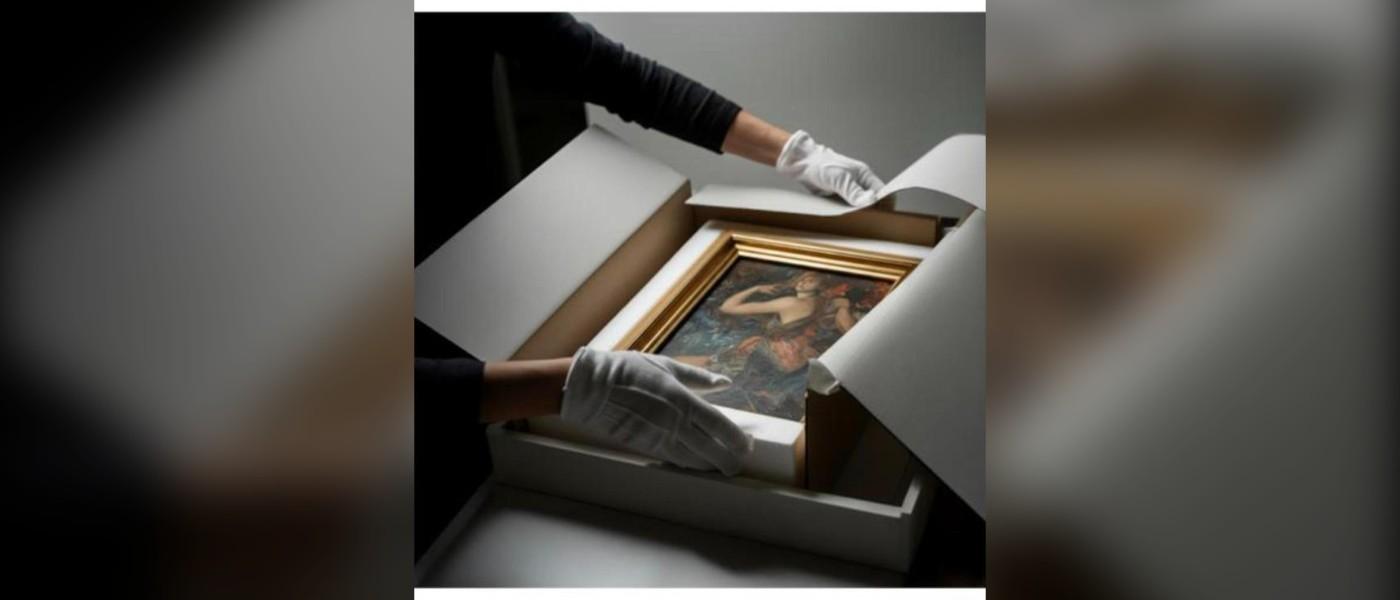
Arta, the New York commerce technology company for art, luxury and collectibles sellers, launched Arta Pay on 19 November 2026, a US personal credit line with limits from $1,000 to above $100,000 that lets collectors split a purchase into a deposit and nine monthly payments. Fintechbits checked the Arta Pay terms and found the finance charge is a flat 12.5% premium on whatever is financed, which Arta discloses as a 0% purchase APR. Sellers such as the auction house Rago Wright and the watch dealer SwissWatchExpo are said to be live, and Arta pays them in full within five business days.
Arta Pay terms: what the 12.5% premium costs a collector
The product charges a one-off premium rather than interest, and the arithmetic is easy to run on the company’s own disclosure. On a $10,000 purchase, the collector pays a $1,000 deposit, which is the 10% minimum, and finances $9,000. The premium is $1,125, so nine payments of $1,125 follow, and the buyer hands over $11,125 in total.
Fintechbits calculated the annualised cost of that schedule, assuming the first monthly payment falls one month after purchase. It comes to roughly 29% a year, with a monthly rate of about 2.4%. Arta decides most applications in real time after a soft credit check, which is fast, but about 29% a year is not the free money that a 0% label suggests.
Arta’s fine print calls the premium a precomputed finance charge and states the purchase APR as 0%. The disclosure follows habits common to pay-over-time products, which Fintechbits has covered in the Affirm and Sam’s Club deal. The difference here is the ticket size and the length of the plan. Arta’s marketing speaks of 10 monthly payments, but the terms page counts the deposit as the first and nine instalments after it.
Lead Bank originates the line, and Arta carries the risk
The fine print states that Arta is not a bank and that Lead Bank originates the line of credit. FDIC data show Lead Bank, based in Kansas City, Missouri, with about $2.76 billion in assets and $2.46 billion in deposits at 30 June 2026. That is a small bank carrying a new consumer credit program for a niche platform.
The structure puts credit exposure on the bank sponsor and Arta, not the gallery. Arta says it assumes both fraud and repayment risk once a buyer is approved. Fintechbits has not found loss rates, a funding source for the receivables or a statement on whether Arta or Lead Bank keeps the loans, and the release does not give them.
Seller terms: payment in full and no fees
The seller page promises settlement of the whole sale amount inside five business days, no chargebacks and no processing fees. A seller can add it at checkout through an API call or send an invoice for a single sale. Adam Fields, Arta’s founder and chief executive, said the product aims at “making it possible for collectors to pay over time while sellers receive payment in full without taking on the financing risk.”
Richard Wright, chief executive of Rago Wright, put the seller case more plainly: “offering that flexibility without taking on credit risk or managing the financing ourselves.” Arta says it launched in 2021, although the release also cites more than a decade of experience, and reports activity in 65 countries and more than $1 billion of item value handled. The credit line, though, is open only to US citizens and residents, and the terms page warns that state restrictions apply.
Fintechbits sees the seller economics as the real engine. A zero-fee promise means Arta earns its return from the 12.5% premium, paid by the collector, rather than from the seller.
Fintechbits analysis
Why Arta Pay fills a gap, and where it could disappoint
The product targets purchases from a few thousand dollars up to about $100,000, a band that card limits and private bank lending serve badly. That is a sensible place to build, and a platform that already handles shipping and insurance for the sale has data that a generic lender lacks. On the evidence available, the launch matters more to sellers than to buyers, because sellers get cash upfront without carrying credit risk.
The buyer deal is harder to defend. A cost near 29% annualised is steep, and a collector with a strong credit score may well have cheaper options elsewhere. The product wins on convenience and on a fixed schedule, not on price, and the 0% APR wording should not be read as a bargain.
Frequently asked questions
How much does Arta Pay cost a collector?
The cost is a 12.5% purchase premium on the amount financed, after a 10% minimum deposit. On a $10,000 purchase that is $1,125 in finance charges, spread across nine payments.
Who lends the money behind Arta Pay?
Lead Bank originates the line of credit, according to the terms Arta publishes. Arta says it is a financial technology company and not a bank.
Can collectors outside the US use Arta Pay?
Not at launch. The line is open to US citizens and residents only, subject to eligibility, credit approval and state restrictions, though Arta sellers operate in more than 65 countries.
What to Watch Next
Three things will show whether the credit line works. First, Arta needs to publish approval rates and the share of collectors who take the maximum line, since a $100,000+ ceiling is only useful if it is granted. Second, regulators in states with licensing rules may question a 0% APR label attached to a 12.5% charge. Third, rivals in pay-over-time credit, which Fintechbits tracked in its Zip survey coverage, may bring cheaper plans to the same price band.
Primary sources
Arta \| COMPANY WEBSITE \| https\://arta.io/arta-pay-collectors
Arta \| COMPANY WEBSITE \| https\://arta.io/arta-pay-sellers
FDIC \| REGULATOR \| https\://api.fdic.gov/banks/institutions?filters=NAME%3A%22Lead%20Bank%22&fields=NAME,CERT,CITY,STALP,ASSET,DEP,REPDTE,ACTIVE&limit=5
Business Wire \| PRESS RELEASE \| https\://www.businesswire.com/news/home/20261119020792/en/