6 mins read
AI chatbots can answer simple banking questions well, but complaints, disputes and hardship still need a person. The hard part is spotting a complaint when the customer never calls it one.
AI chatbots now handle a large share of routine banking questions. Bank of America said its Erica assistant had 20.6 million users and nearly 700 million interactions in 2025, CMSWire reported. Still, regulated firms face a harder question than how much a bot can do. They need to know when it should stop. For a related look at how firms tell AI agents from people, see our report on Socure’s agent tools.
We asked one question: how far do you let AI chatbots go in handling customer queries in a regulated financial business, and where do you hand over to a human? We wanted customer experience, compliance and product leads at banks, neobanks, lenders and insurers. Ideally, they would share resolution rates or complaint figures. Two people answered in this round, and we used one. The other answer did not address customer chatbots and made claims we could not verify. Our one respondent does not work at a regulated firm, so we’ve set his advice against what regulators expect.
What regulators expect
The UK regulator has set out its view in detail. On 19 October 2026, the FCA published a page of good and poor practice on AI in financial services, as Norton Rose Fulbright summarises. It wants clear human oversight and escalation triggers. It also wants firms to tell consumers how they use AI and its limits. In addition, good practice includes letting customers choose AI or human support for simple tasks, and switching channels without repeating themselves.
US concerns came earlier. In 2023, the Consumer Financial Protection Bureau estimated that about 37% of the US population used a bank’s chatbot in 2022, in its report on chatbots in consumer finance. It warned of “doom loops” with no clear route to a human. It also found that chatbots may fail to recognise a dispute.
Europe now has a hard rule too. Since 2 August 2026, the EU AI Act has required AI chatbots to tell people they are dealing with AI, unless that is already obvious, Jones Walker explains. The EU delayed its high-risk AI rules, but not this duty.
Let bots answer questions with one right answer
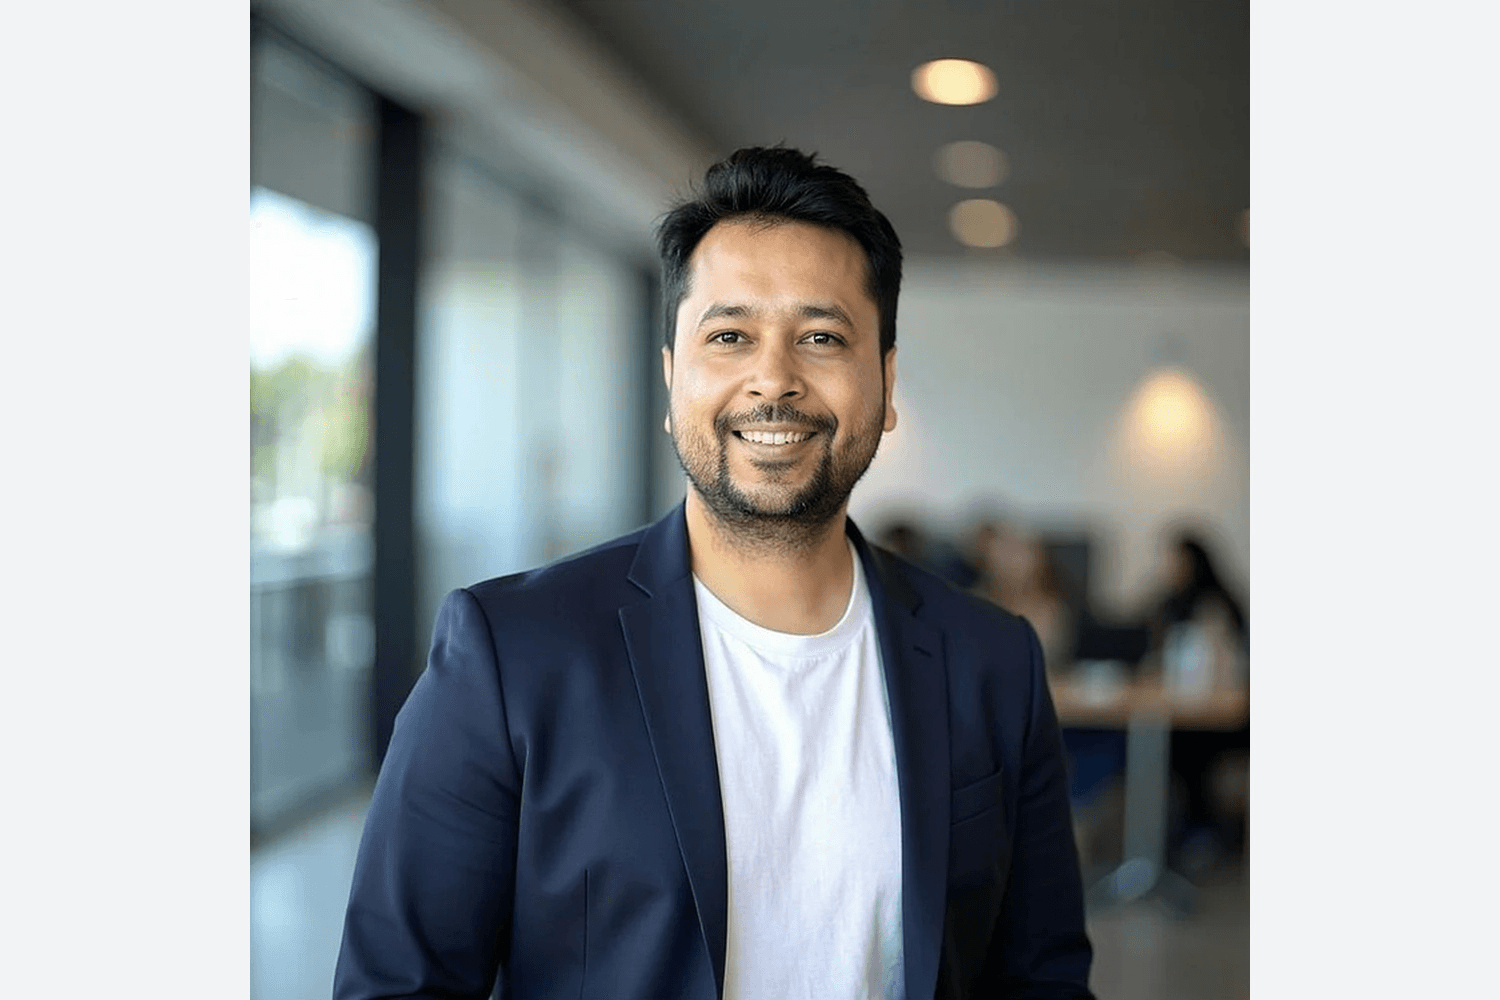
Ankit Sarawagi curates CFO Matrix, a finance resource, and set out a simple dividing line.
“Chatbots can handle any question that has a pre-approved answer. That includes where a payment is, what the fees are, which documents are needed and how to reset access. Each of those has one correct answer, so a chatbot can speed things up with little added risk.
If a customer mentions a complaint, a dispute, financial hardship or vulnerability, or suspected fraud, or asks for a recommendation, the chatbot should hand over to a person. The same goes for anyone asking the same question a second time. And it should pass on the whole conversation, so the customer doesn’t have to tell their story again.
Spotting complaints is the hardest part to test. Customers rarely use the word ‘complaint’. They’re more likely to say something like ‘this is the third time’. So define what counts as a complaint before you try to measure it.”
Ankit Sarawagi, Curator, CFO Matrix
His dividing line fits the FCA’s direction. The regulator’s good practice includes escalation triggers, and it cites a customer mentioning financial distress as one firms used to refine them. It also wants customers to switch channels without repeating information, which is his point about passing on the whole conversation. So the handover is part of the service, not a failure of AI chatbots.
His warning about complaints is the sharpest point. Under FCA rules, a complaint is any expression of dissatisfaction, whether or not the customer uses the word. Therefore, keyword lists alone will miss phrases like “this is the third time”. The CFPB’s finding that AI chatbots can miss a dispute points the same way.
However, his original claim that simple queries add no risk went too far. Even a fixed answer from AI chatbots can go wrong if the bot pulls the wrong account data. So we’ve softened that line. He gives no resolution or complaint figures, and CFO Matrix is not a regulated firm. His answer is guidance rather than a case study.
Where AI chatbots should hand over
Taken together, the rules and his answer point to a clear set of triggers. AI chatbots should pass the customer to a person when they complain or show frustration, dispute a transaction, mention money worries or signs of vulnerability, or report fraud. It should also hand over when someone asks for a recommendation, since that can stray into advice. Finally, a repeated question is a trigger in its own right, because it suggests the bot has already failed.
The handover itself matters as much as the trigger. If AI chatbots drop the customer into a queue with no record, the customer repeats everything, which is what the FCA wants firms to avoid. As a result, the best handovers pass the full transcript and the reason for escalation to the agent. Meanwhile, firms need to watch the other risk: a bot that escalates too little because it was tuned to cut call volumes.
What works for firms using AI chatbots
The evidence points to a simple order of work. First, list the queries that have one approved answer, such as fees, payment status and password resets, and keep AI chatbots to those at launch. Next, tell customers they are talking to a bot, which EU law now requires and the FCA expects. Then set escalation triggers for complaints, disputes, hardship, fraud and advice requests, and treat repeat questions as a trigger too. Finally, test outcomes across different customer groups before launch, and track how many complaints began in the chatbot. Firms adding AI agents to back-office work, such as Intuit’s bookkeeping tools, face similar questions about where people stay in the loop.
What to watch next
The next test is evidence. Watch how the FCA follows up its October review, and whether it asks firms for outcome data on AI chatbots. In the EU, also watch how national authorities enforce the disclosure duty that applied from August. In addition, few firms publish how many complaints start in a chatbot, so any bank that does will set a useful benchmark.
Above all, the value of AI chatbots in finance depends on how well they stop. A bot that answers fee questions in seconds helps everyone, but one that traps an upset customer creates a complaint of its own.
FintechBits covers payments, banking and fintech developments for readers in the US and UK. This article is for information only and is not financial or legal advice. Views expressed are those of the FintechBits editorial team.