5 mins read
Valley National Bancorp agreed on 28 September 2026 to acquire Bluevine, the Jersey City-based small-business banking platform, for total consideration of about $340 million, roughly 75% cash and 25% Valley stock. The Valley Bluevine acquisition brings $2.1 billion of deposits, about 175,000 active small-business customers and about 180 research and development staff and engineers. Closing is targeted for early 2027 and depends on regulatory approvals, according to the joint release.
The Terms Valley Disclosed for the Valley Bluevine Acquisition
Valley says the deal, including expected synergies, should add about 8% to estimated 2028 earnings per share. It expects about 5% dilution to tangible book value at closing and an earn-back period of about three years. After closing, Eyal Lifshitz, Bluevine’s co-founder and chief executive, moves into the head of small business banking role at Valley. Cantor Fitzgerald advised Valley, with Wachtell, Lipton, Rosen & Katz as counsel, and Financial Technology Partners advised Bluevine, with Sidley Austin as counsel.
The release says Bluevine’s platform-generated deposits grew at about a 35% compound annual rate between 2023 and the second quarter of 2026, and that about 99% of them come from customers who do not borrow. Bluevine was founded in 2013 and, as of June 2026, had served more than 415,000 businesses. Banking Dive added that the deposits sit at partner bank Coastal Community Bank and will move to Valley, which has $66 billion of assets, in the first half of 2027.
The Funding-Cost Arithmetic Behind the Valley Bluevine Acquisition
Banking Dive, citing an investor presentation, reported that Bluevine’s cost of deposits is 1.44% against 2.28% at Valley. The gap is 0.84 percentage points, and applied to $2.1 billion it comes to about $17.6 million a year. The $340 million price is roughly 19 times that saving. These are Fintechbits’ calculations from reported figures, and they assume the deposits keep their reported cost after they move onto Valley’s balance sheet, which is uncertain.
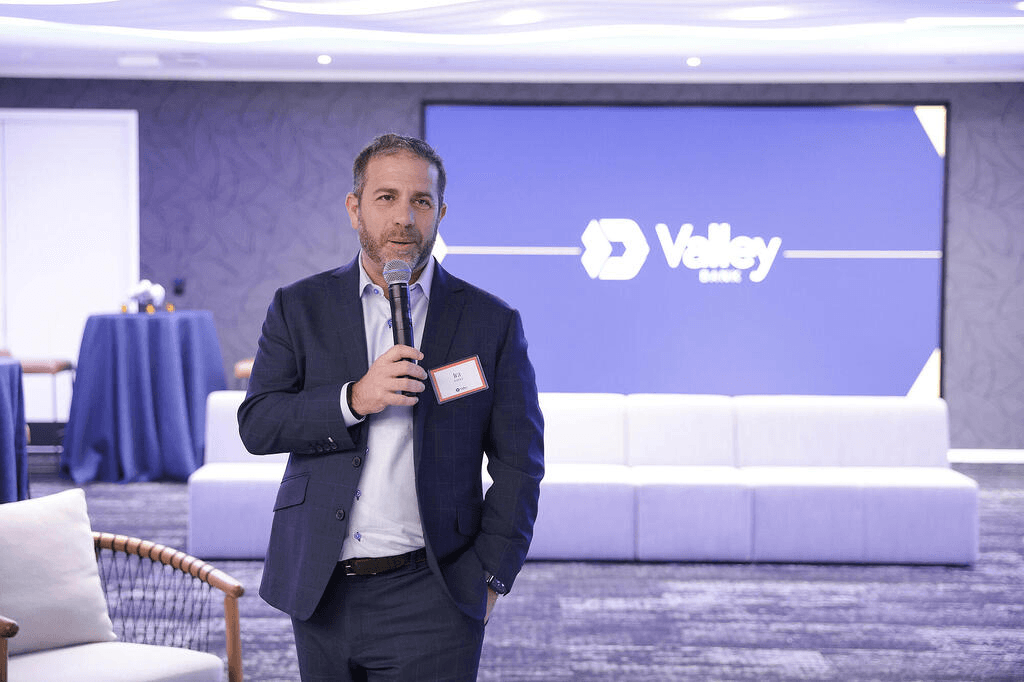
The sum shows that cheaper funding is not what justifies the price. The 8% earnings accretion has to come from somewhere else: expense synergies, growth in the deposit base, and cross-sell. Valley chief executive Ira Robbins said on the conference call that about 40% of Bluevine’s customers are inside Valley’s footprint, where treasury management, wealth and other products could be sold to them, and that the deal would grow Valley’s small-business customer base twentyfold.
Fintechbits analysis
Why a Regional Bank Bought Instead of Applying for a Charter
Robbins framed the deal as a choice not to wait: “Rather than waiting for chartered fintechs to compete with us for small business banking relationships”, he said, Valley would combine its banking foundation with Bluevine’s digital growth engine. Trade coverage has carried a run of fintech charter stories, with Banking Dive headlines on Mission Lane’s conditional approval from the Office of the Comptroller of the Currency and on Avant’s application. Fintechbits covered the charter route in Block’s trust charter filing, a different instrument from a bank charter but the same instinct.
My view is that the Valley Bluevine acquisition is a funding purchase dressed in the language of technology. Robbins described the aim as addressing the “core funding challenge” at Valley, and the bank announced Providence Financial for $247 million in August 2026. Executives said on 28 September that they do not expect more acquisitions for the foreseeable future. For Valley, Bluevine is the second of two deals aimed at the same gap. Small-business operating accounts are sticky funding, which is why the 99% non-borrowing share matters. Fintechbits’ guide to SMB digital banking explains why those accounts are valued.
What Valley Has Not Shown
Bluevine’s revenue, profit and loan performance are absent from the release. So is any estimate of deposit run-off when customers move from a fintech brand to a regional bank. Robbins told Banking Dive that most of Bluevine’s code is written by AI and AI handles about 80% of inbound client queries. Lifshitz said account opening takes about five minutes and put Bluevine’s own platform spending at close to $200 million. All of these are company statements without independent testing. The investor presentation behind the deposit cost figures has not been reviewed by Fintechbits, which means the Valley Bluevine acquisition arithmetic above rests on a trade-press summary.
What to Watch Next on the Valley Bluevine Acquisition
The test comes after the deposit transfer in the first half of 2027. If Valley reports Bluevine deposit balances in its quarterly results and they hold near $2.1 billion at a cost close to 1.44%, the funding case holds. If balances fall or costs climb, the Valley Bluevine acquisition starts to look like a premium paid for engineers and a customer list.
Questions and answers
How much is Valley National Bancorp paying for Bluevine?
Valley agreed on 28 September 2026 to pay about $340 million for Bluevine, roughly 75% in cash and 25% in Valley stock.
How many deposits and customers does Bluevine bring to Valley?
Bluevine brings $2.1 billion of deposits and about 175,000 active small-business customers to Valley National Bancorp.
When will the Valley Bluevine acquisition close?
Valley says closing is targeted for early 2027 pending regulatory approvals, and Banking Dive reports the deposits will move from Coastal Community Bank to Valley in the first half of 2027.
Does cheaper funding justify the Valley Bluevine acquisition price?
On Fintechbits’ arithmetic it does not, because Bluevine’s 1.44% deposit cost against Valley’s 2.28% saves about $17.6 million a year on $2.1 billion, and the $340 million price is roughly 19 times that.