5 mins read
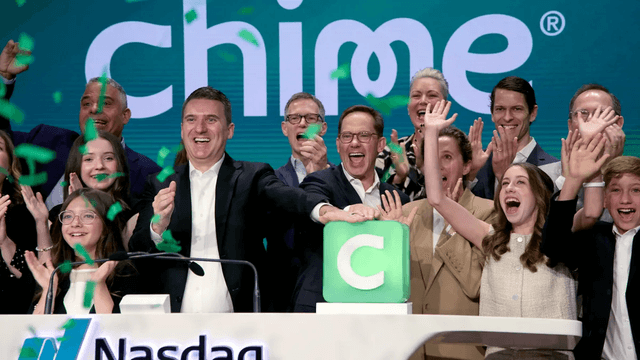
Chime Q2 earnings landed on Wednesday, August 5, with revenue of $670 million, up 27 percent year over year and ahead of the $640.4 million analysts expected. Meanwhile, net income reached $28 million. That marks a second consecutive quarter of GAAP profitability since the June 2025 listing on Nasdaq.
Buried in the same Chime Q2 earnings filing, Chief Financial Officer Matthew Newcomb stepped down on August 7 after a decade at the company. In his place, President Mark Troughton took the role on an interim basis while an executive search runs. Newcomb stays on as an adviser under a transition agreement.
Chime Q2 Earnings Came With a 10% Workforce Cut
One element belongs in any honest summary of that day. Alongside the results, management approved a reorganisation plan reducing headcount by roughly 10 percent.
The charges are disclosed. In the third quarter, Chime estimates $16 million to $20 million in net cash restructuring costs. Net income takes a $6 million to $9 million hit, partly offset by a $9 million to $12 million reduction in stock-based compensation.
So the Chime Q2 earnings filing carried three things at once. A revenue beat, a workforce reduction and a change of finance chief all arrived together. For context, chief executive Chris Britt frames the efficiency drive as long-running. He notes the company has cut its average cost to serve by 10 percent in each of the last four years through a digital-first model and AI-driven efficiency. Even so, three simultaneous disclosures form a different picture than strong results plus a departure.
The Chime Q2 Earnings Reaction Answers the Question
Market response to the Chime Q2 earnings settles the interpretive question rather than leaving it open. Shares rose roughly 8 to 9 percent in extended trading that evening.
Investors weighted the beat and the raised guidance far above the executive change. Full-year revenue growth guidance moved to 25 to 26 percent, above the 22.7 percent analysts had modelled. That takes the top line to around $2.745 billion. Similarly, third-quarter guidance sits at $680 million to $690 million with adjusted EBITDA of $105 million to $110 million. Full-year adjusted EBITDA runs to $465 million to $475 million.
Notably, the departure disclosure is formal rather than ambiguous. The 8-K filing states that Newcomb’s resignation was not due to any disagreement regarding the company or any matter relating to its operations, policies or practices. That is standard language, though it is the legally required statement and it exists on the record.
Troughton is not a stopgap either. Because he already serves as president and takes the finance role alongside those duties, continuity is not the concern.
Chime Q2 Earnings Show a Widening Product Stack
Underneath the Chime Q2 earnings headline, operations look genuinely stronger. Adjusted EBITDA reached $102 million at a 15 percent margin, expanding more than 12 percentage points year over year. Beyond that, gross profit hit $595 million on an 89 percent gross margin, with transaction profit of $492 million.
Members and monetisation both moved. Active members rose 20 percent to 10.4 million. In parallel, average revenue per active member climbed 6 percent to $260. Then purchase volume reached $38 billion, up 17 percent, or $39.4 billion including outbound instant transfers. Payments revenue grew 21 percent.
Lending carried real weight in the Chime Q2 earnings mix. MyPay generated $73 million in transaction profit on $4.5 billion of originations.
Meanwhile, the customer mix is shifting. Chime says its fastest-growing segment is people earning $75,000 or more annually, and it credits Chime Prime, the membership tier launched this year, with accelerating both member acquisition and revenue per member. Seaport Research Partners analysts flagged Prime as an increasingly central driver. Consequently, growth is coming from products that resemble a full financial stack rather than a checking account, spanning lending, investing and a subscription layer above both.
What to Watch After Chime Q2 Earnings
The permanent hire is the first signal. Watch whether Troughton keeps the interim label, and what profile Chime recruits. An operator suggests continuity, while a capital markets hire suggests different ambitions.
Then watch the restructuring. A 10 percent reduction and a finance transition running simultaneously is a demanding combination. Third-quarter results will show whether cost discipline held without denting growth.
Finally, watch Prime economics specifically. Should membership revenue keep compounding while acquisition costs fall, the Chime Q2 earnings pattern repeats. After all, that combination separates Chime from neobanks chasing the same playbook without reaching profitability.
For related reading, our guide to challenger banking innovators maps the competitive field. Our analysis of Revolut wealth management covers comparable product expansion, while our piece on the true cost of capital examines lending economics. Reuters reported the results and share reaction. CFO Dive covered the finance transition, and the 8-K filing carries the formal disclosure.
Fintechbits covers digital banking, consumer fintech and financial results. Nothing here constitutes financial or investment advice. All analysis represents the editorial views of Fintechbits.