4 mins read
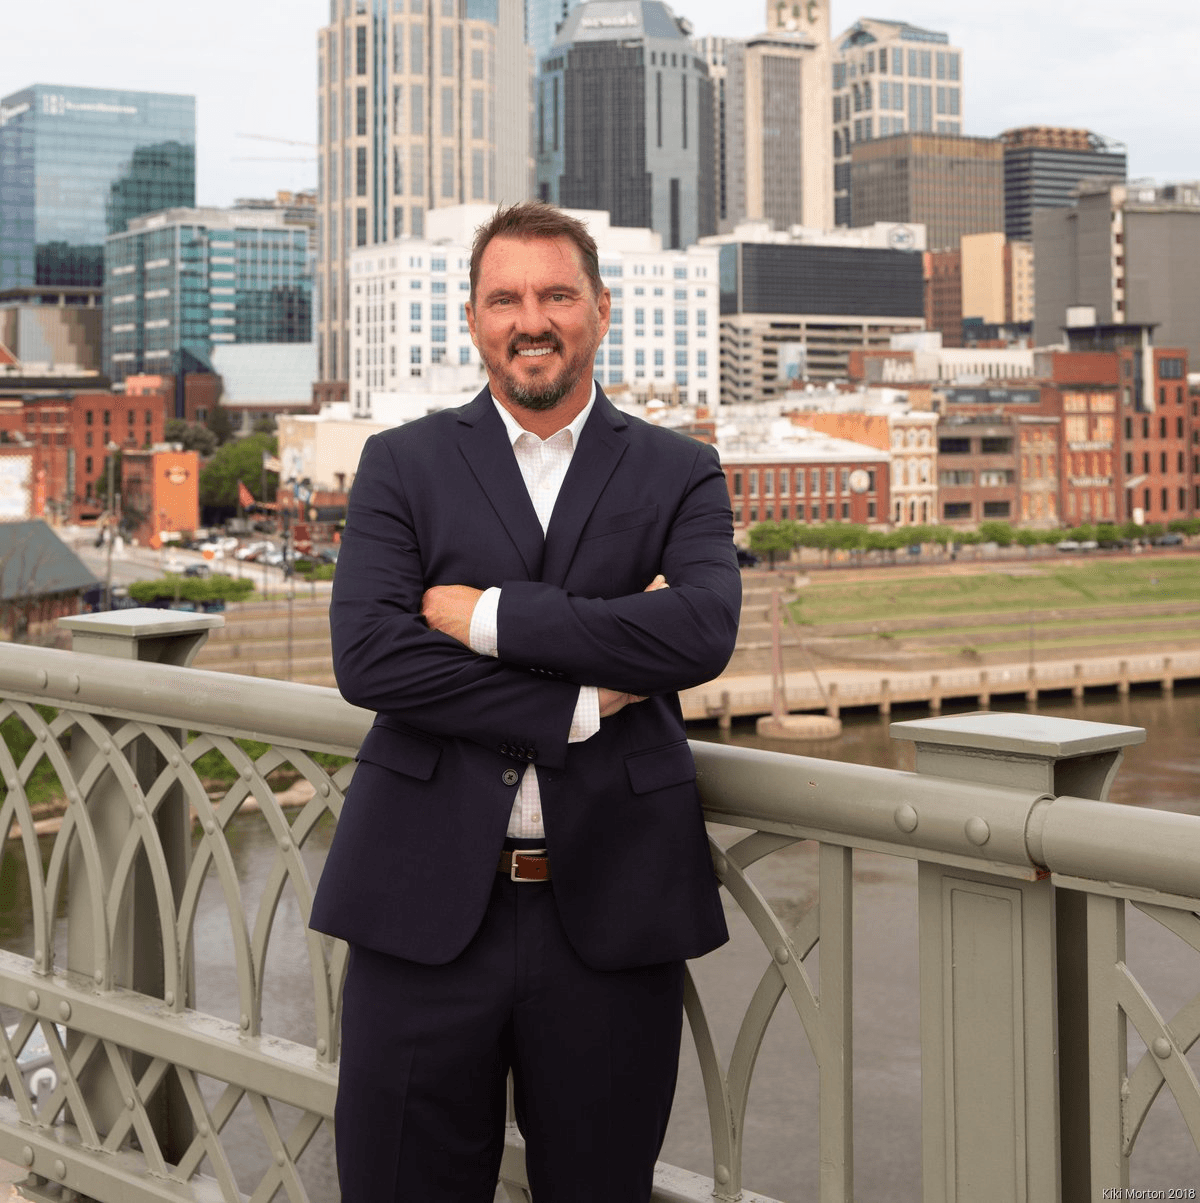
Deluxe Merchant Services will now be led by Kevin Jones, the founder whose company Deluxe bought weeks earlier. Specifically, on August 17, Deluxe named Jones president of the division after closing its Celero Commerce acquisition at the end of July. Therefore, this is more than a routine executive appointment. Jones will run the combined merchant acquiring operation he just sold into.
Meanwhile, under Jones, Celero grew to process more than $28 billion annually across 175 banking partners and 55,000 small business customers. In turn, the combined Deluxe Merchant Services platform is expected to process more than $70 billion in annual gross transaction volume. Deluxe says that scale places it among the ten largest US non-bank merchant acquirers, based on Nilson reporting.
Deluxe Merchant Services Has a Founder Precedent
Jones brings a useful history, but the sequence matters. Before founding Celero in 2018, he led the strategic partner channel at First American Payment Systems. He had also founded Anovia Payments, where Deluxe says he delivered an 8.5-times investment return. However, that Anovia exit was separate from Deluxe. Later, Deluxe bought First American, Jones’s former employer, for $960 million in 2021.
More importantly, the cleaner precedent is First American founder Neil Randel. When Deluxe completed that deal, Randel moved into the role of managing director for merchant services. Contemporary coverage of the First American acquisition confirms that founder-to-operator handover. Consequently, Deluxe Merchant Services has now used this structure twice: retain the founder after buying the platform, then put that operator close to the acquired engine.
Still, that does not prove the structure worked the first time or will work now. Deluxe has not published a controlled comparison between founder-led integration and conventional corporate management. The appointment instead shows what management values. Specifically, CEO Barry McCarthy emphasised Jones’s experience creating new ventures in a changing payments market, which suggests Deluxe wants entrepreneurial execution inside a legacy organisation.
That choice fits Deluxe’s larger repositioning. Historically, the company has spent more than a century serving businesses through checks and related services. Yet its Celero acquisition case projected that Payments and Data would reach 57% of 2026 pro forma revenue, up from 31% in 2020. For readers tracking the future of payments, the appointment makes the people strategy behind that revenue shift unusually visible.
Deluxe Merchant Services Makes Integration the Test
Deluxe Merchant Services now carries a clear founder-retention risk. Jones has already proved that he can build payments companies. However, running an acquired division inside a public company demands different incentives, reporting lines and decision speed. If those constraints weaken his authority, Deluxe could keep the platform while losing part of the operating judgement it intended to buy.
Crucially, the numbers also require care. Deluxe processes more than $2 trillion in annual payment volume across its entire business, while the combined merchant platform expects more than $70 billion in gross transaction volume. Therefore, the larger figure should not be presented as the scale of Deluxe Merchant Services. The narrower number is the relevant benchmark for merchant-acquiring consolidation.
Nor does this acquisition prove that Deluxe cannot build technology internally or that buying innovation is cheaper. Instead, it shows that Deluxe was willing to buy customer relationships, distribution and an operating team to accelerate its shift. More broadly, that distinction matters because the hidden work begins after closing. As our analysis of financial product integration costs argues, combining platforms can create expenses and organisational friction that the deal headline misses.
For now, the strongest evidence will come from execution. Deluxe Merchant Services must retain Celero’s banking partners and merchants, realise more than $15 million in expected cost synergies, and give Jones enough room to operate. Moreover, investors should watch whether Deluxe repeats the acquire-and-install model in its next merchant deal. Ultimately, two founder handovers since 2021 establish a pattern. A third would make it a playbook.
Fintechbits covers merchant acquiring, payments consolidation and fintech strategy. Nothing here constitutes financial or investment advice. All analysis represents the editorial views of Fintechbits.